Header and translation note
The name of taxpayer field, the note on English translations, and the line asking for copies of the items, not originals.
14815
Supporting Documents to Prove Eligibility for the Child Tax Credit (CTC) and Credit for Other Dependents (ODC)
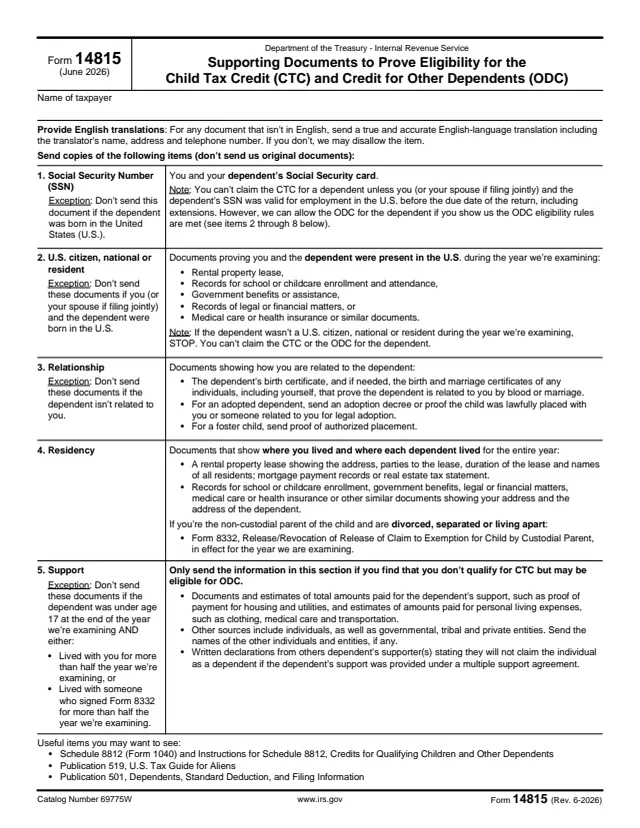
Form 14815, Supporting Documents to Prove Eligibility for the Child Tax Credit (CTC) and Credit for Other Dependents (ODC), is a one-page IRS list of the documents to send for a dependent claimed for those credits. It refers to "the year we're examining" and says to send copies of the listed items, not original documents.
The top of the form has one field, the name of the taxpayer. The rest is a numbered list of five items: Social Security number (SSN), U.S. citizen, national or resident, relationship, residency, and support. Most items carry an exception that says when not to send them, for example when the dependent was born in the United States.
The form says a document not in English needs a true and accurate English-language translation with the translator's name, address and telephone number. You can fill in the name free in your browser on this page and download the form without an account.
The name of taxpayer field, the note on English translations, and the line asking for copies of the items, not originals.
The taxpayer's and the dependent's Social Security cards. The note says the CTC needs an SSN valid for employment before the return's due date, including extensions, while the ODC can still be allowed.
Proof the taxpayer and the dependent were present in the U.S. during the year examined, such as a lease, school or childcare records, government benefits, legal or financial records, or medical records.
The dependent's birth certificate and any birth and marriage certificates that prove the relationship, an adoption decree or placement proof, or proof of authorized foster placement.
Documents showing where the taxpayer and each dependent lived for the entire year, such as a lease, mortgage records or a real estate tax statement, plus Form 8332 for a non-custodial parent.
Documents and estimates of amounts paid for the dependent's support, the names of other supporters, and written declarations under a multiple support agreement.
Enter the name of the taxpayer at the top of the page. It is the only field on the form.
The left column says when not to send an item: item 1 when the dependent was born in the U.S., item 2 when the taxpayer and dependent were born in the U.S., item 3 when the dependent isn't related.
Collect copies of the items that apply for the dependent. The form says not to send original documents.
The form says to send item 5 only if the taxpayer doesn't qualify for the CTC but may be eligible for the ODC, and not when its under age 17 exception applies.
Attach an English translation with the translator's name, address and telephone number to any document not in English. The form says otherwise the IRS may disallow the item.
The form lists Schedule 8812 (Form 1040) and its instructions, Publication 519, U.S. Tax Guide for Aliens, and Publication 501 as useful items.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to send the copies to the IRS ("send us"). It prints no mailing address.
The form says "don't send us original documents."
A document not in English needs a true and accurate English-language translation, or the form says the IRS may disallow the item.
The form says "STOP" if the dependent wasn't a U.S. citizen, national or resident during the year examined, and that neither the CTC nor the ODC can then be claimed for that dependent.
The header prints June 2026 and the footer prints Form 14815 (Rev. 6-2026).
8332
11 fields, 2 pages
1040
41 fields, 2 pages
14815-A
2 fields, 2 pages
14819
3 fields, 2 pages
14820
8 fields, 2 pages
14824
3 fields, 2 pages
The form is addressed to a taxpayer whose CTC or ODC claim the IRS is examining. The taxpayer gathers the copies and sends them to the IRS.
No tool matches that search.
The IRS. The form asks the taxpayer to send copies of the listed documents for the year being examined.
No. The form says "don't send us original documents."
The exception for item 1 says not to send it if the dependent was born in the United States.
The form says to send it only if the taxpayer finds they don't qualify for the CTC but may be eligible for the ODC. Its exception covers a dependent under age 17 at the end of the year who lived with the taxpayer, or with someone who signed Form 8332, for more than half the year.
The form asks for a true and accurate English-language translation with the translator's name, address and telephone number, and says the IRS may otherwise disallow the item.
Item 4 lists Form 8332, Release/Revocation of Release of Claim to Exemption for Child by Custodial Parent, in effect for the year examined, for a non-custodial parent who is divorced, separated or living apart.