Header
The return period, name, employer identification number, address, daytime phone, business address, and any alias, style or trade name, plus boxes for a first return, renewal return or supplemental registration.
11-C
Occupational Tax and Registration Return for Wagering
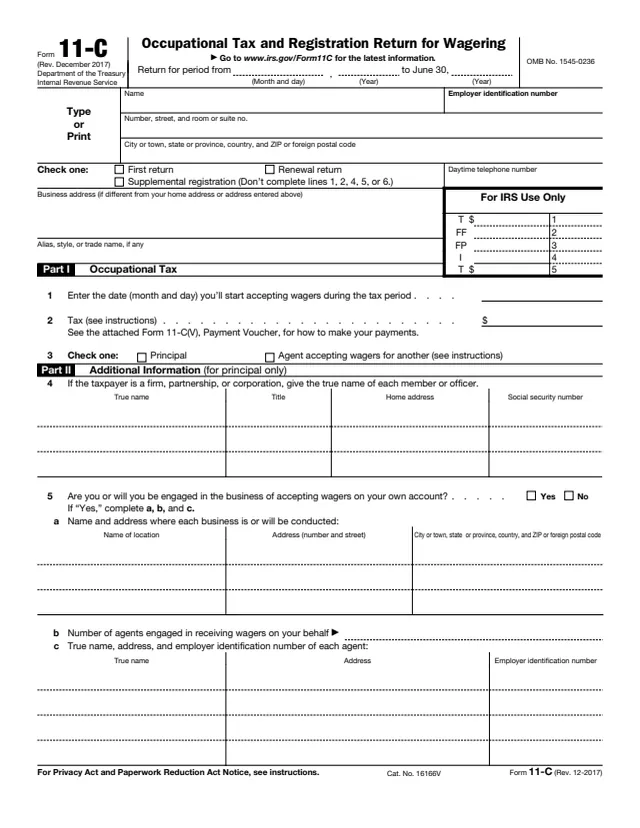
Form 11-C, Occupational Tax and Registration Return for Wagering, is a business return. The IRS About page says it is used by principals or agents who accept taxable wagers to register certain information with the IRS and to pay the occupational tax on wagering.
The instructions on the form say there are two amounts of occupational tax ($50 or $500). Which one applies depends on whether the wagers accepted are authorized by the laws of the state in which they are accepted. The instructions also say "Your cancelled check is proof of registration and payment."
The PDF includes the instructions and Form 11-C(V), Payment Voucher, which is sent with the return and payment. This page has the December 2017 revision. The PDF can be filled out free in the browser on this page and downloaded without an account.
The return period, name, employer identification number, address, daytime phone, business address, and any alias, style or trade name, plus boxes for a first return, renewal return or supplemental registration.
Line 1 is the date wagers start being accepted, line 2 is the tax, and line 3 has two boxes: Principal, or Agent accepting wagers for another.
Line 4 lists the true name, title, home address and Social Security number of each member or officer of a firm, partnership or corporation. Line 5 covers business locations and the agents who receive wagers.
Line 6 lists the true name, address and employer identification number of each person on whose behalf the agent receives wagers.
Line 7 explains why a supplemental registration is filed and the date of the event. The return is signed under penalties of perjury, with a Paid Preparer Use Only section below.
Boxes for the EIN, the amount paid, the year and month from the return period line, and the business name and address.
Enter the month, day and year the return period begins and the ending year, as four-digit years. Enter the EIN. The instructions say an individual enters a home address.
Enter the day and month wagers will start being accepted. The instructions say a full month's tax is due regardless of which day in the month wagers start.
Use the table in the instructions. The $50 tax applies if all wagers are authorized under the laws of the state where accepted, otherwise the $500 tax applies. The instructions say the tax is prorated for the first year if wagers start after July 31.
Check one box, Principal or Agent. The instructions say principals are liable for the excise tax on wagers, which is reported and filed monthly on Form 730.
Principals complete lines 4 and 5 with officers or partners, each business location, the number of agents and each agent's name, address and EIN. Agents complete line 6 with each person or company they accept wagers for.
Complete the name, address, EIN, business address and alias lines, check the supplemental registration box and line 3, and describe the change and its date on line 7. Lines 1, 2, 4, 5 and 6 are left blank.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to send Form 11-C, the check or money order, and Form 11-C(V) to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0101.
The instructions say to file the first return before wagers are accepted, then a renewal return by July 1 for each year wagers are accepted. Some ownership changes call for a new first return within 30 days.
The instructions say a principal's address change is registered before accepting wagers at the new address or within 30 days, whichever occurs first. Certain other events allow 30 days, and a new agent 10 days. The tax is not paid a second time.
Make the check or money order payable to "United States Treasury" with the EIN, "Form 11-C" and the tax period on it. The voucher says not to staple or attach it to the payment or the return.
The instructions say an overpayment may be claimed on Form 8849 using Schedule 6 (Form 8849), and list penalties for late filing, accepting wagers before paying the tax and willful failure to file.
730
45 fields, 4 pages
8849
27 fields, 4 pages
8849 Sch. 6
26 fields, 1 page
SS-4
89 fields, 2 pages
W-12
85 fields, 3 pages
The instructions say "File Form 11-C if you're a principal or an agent." It is filed with the IRS by the person or business that accepts taxable wagers.
No tool matches that search.
The instructions say it is used to register certain information with the IRS and to pay the occupational tax on wagering.
The instructions say there are two amounts, $50 or $500, depending on whether the wagers accepted are authorized by the laws of the state where they are accepted. Starting after July 31 means a prorated amount for the first year.
The instructions say the first return is filed before wagers are accepted, and a renewal return by July 1 for each year wagers are accepted.
No. The instructions say principals are liable for the excise tax on wagers, which is reported and filed monthly on Form 730. Form 11-C covers registration and the occupational tax.
The instructions give Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0101, sent with the payment and Form 11-C(V).
The instructions say it is signed by a person who has authority to sign for the taxpayer. A paid preparer who is not an employee of the filing entity also signs and completes the Paid Preparer Use Only section.