Header
The entity's name and employer identification number, and the note that the form is completed only if total receipts are $500,000 or more.
1125-E
Compensation of Officers
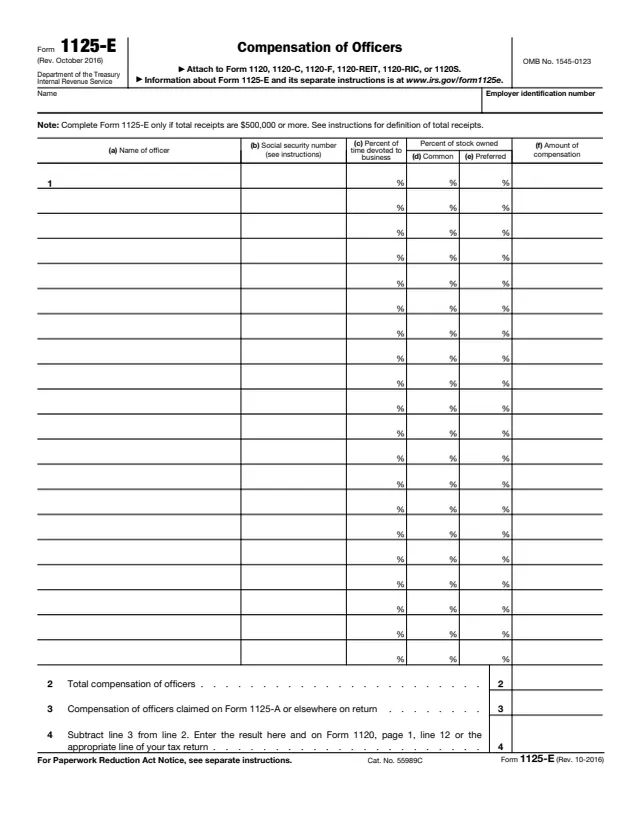
Form 1125-E, Compensation of Officers, is a one-page attachment to a corporate income tax return. The instructions say certain entities with total receipts of $500,000 or more use it to provide a detailed report of the deduction for compensation of officers.
The form lists each officer with a Social Security number, the percent of time devoted to the business, the percent of common and preferred stock owned, and the amount of compensation. The total, less officer pay claimed elsewhere on the return, carries to Form 1120, page 1, line 12 or the matching line of the return it is attached to. The form says "Attach to Form 1120, 1120-C, 1120-F, 1120-REIT, 1120-RIC, or 1120S."
This page has the October 2016 revision. You can fill out the PDF free in your browser on this page and download it without an account.
The entity's name and employer identification number, and the note that the form is completed only if total receipts are $500,000 or more.
Name of officer, Social Security number and percent of time devoted to the business, with 20 rows on the form.
Percent of common stock owned, percent of preferred stock owned, and the amount of compensation for each officer.
Total compensation of officers, compensation claimed on Form 1125-A or elsewhere on the return, and the difference that carries to the tax return.
Figure total receipts with the formula in the instructions for the return being filed, for example Form 1120, page 1, line 1a, plus lines 4 through 10.
Complete columns (a) through (f) for all officers. The instructions say a corporation determines who is an officer under the laws of the state or country where it is incorporated.
Enter each officer's Social Security number. The instructions say filers may elect to provide only the last four digits.
Enter total deductible compensation such as salaries, commissions, bonuses and taxable fringe benefits. For an S corporation, include fringe benefits of officers owning more than 2% of the stock.
Add column (f) on line 2. On line 3 enter officer pay deducted elsewhere, such as in cost of goods sold or 401(k) elective contributions. Subtract and carry line 4 to Form 1120, page 1, line 12 or the matching line.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1120, 1120-C, 1120-F, 1120-REIT, 1120-RIC or 1120S. It is filed with that return, with no separate due date or address on the form.
The instructions say publicly held corporations cannot deduct compensation to a covered employee to the extent it exceeds $1 million. The definition of covered employee changed for tax years beginning after 2017.
The instructions say a portion of payments to key personnel above their usual compensation may not be deductible when tied to a change in control. See section 280G.
For entities that received financial assistance under TARP, the instructions say the $1 million limit is reduced to $500,000 for covered executives.
The instructions say a corporation that claims a credit for wages paid may need to reduce its deduction for officers' compensation. See section 280C.

1120
481 fields, 6 pages

1120-S
390 fields, 5 pages
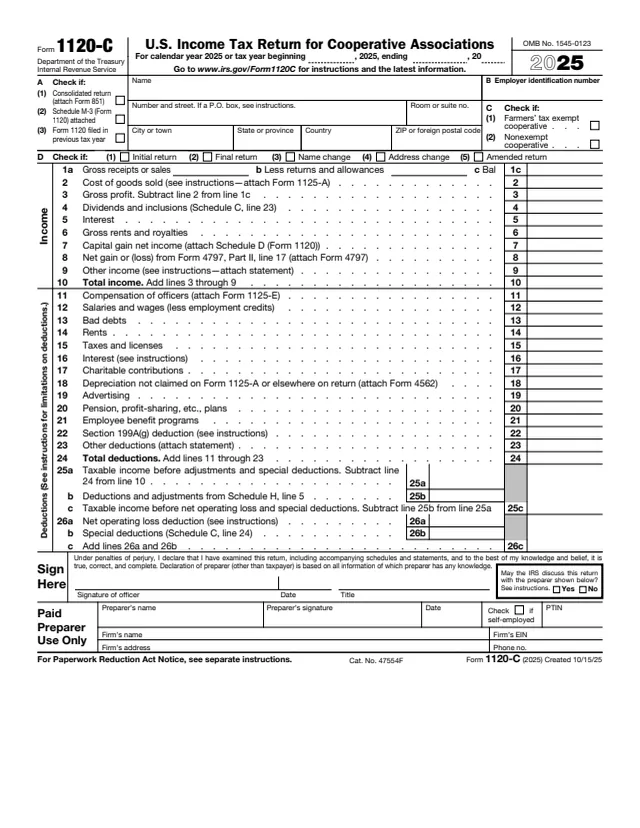
1120-C
449 fields, 5 pages
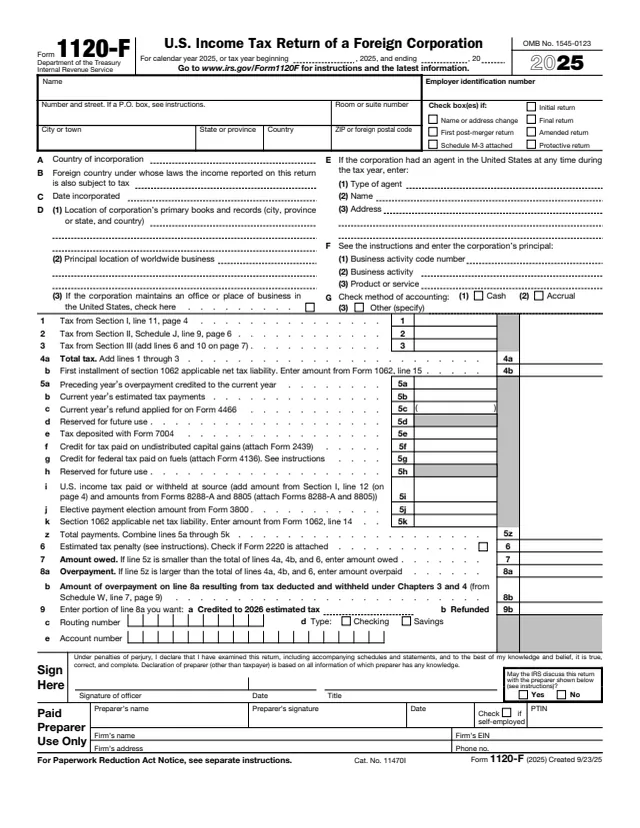
1120-F
527 fields, 9 pages
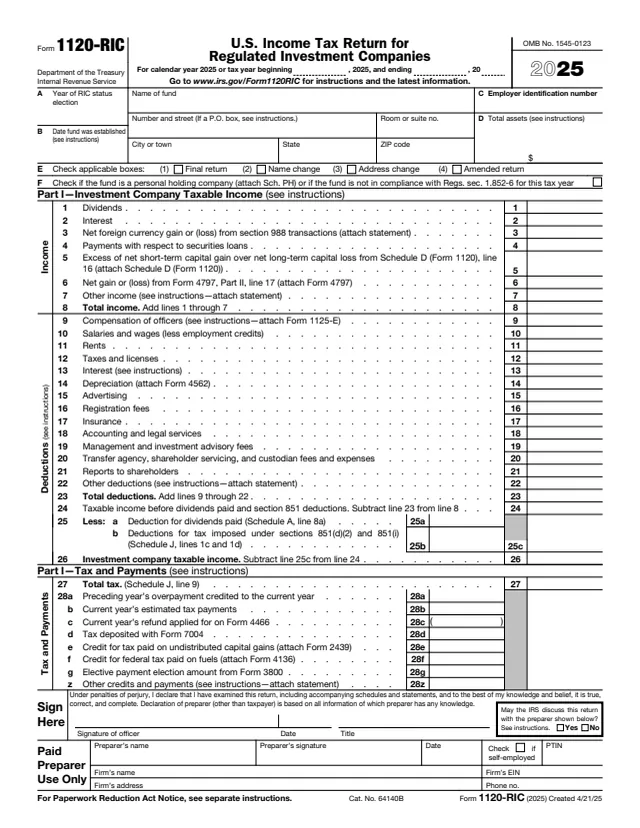
1120-RIC
325 fields, 4 pages
1125-A
25 fields, 3 pages
The corporation or other entity completes the form and attaches it to its own return. The officers listed on it do not file it.
No tool matches that search.
The instructions say it is completed and attached when the entity has total receipts of $500,000 or more and deducts compensation for officers.
The instructions say filers may elect to provide only the last four digits of the officer's SSN in column (b).
The instructions say a corporation determines who is an officer under the laws of the state or country where it is incorporated.
Officer compensation deductible elsewhere on the return, such as amounts in cost of goods sold, elective 401(k) contributions, or amounts under a salary reduction SEP or a SIMPLE IRA plan.
The form says to enter it on Form 1120, page 1, line 12, or the appropriate line of the return the form is attached to.
The instructions say to include fringe benefits of officers owning more than 2% of the stock in column (f), and not those of officers owning 2% or less, which are reported elsewhere.