Recipient or lender details
Name, address, telephone number and TIN of the filer. The instructions say to use the same name and address on Form 1096.
1098-E
Student Loan Interest Statement
Form 1098-E is the student loan interest statement. The IRS page says that if you receive student loan interest of $600 or more from an individual during the year in the course of your trade or business, you file this form and provide a statement or acceptable substitute, on paper or electronically, to the borrower. The filer sends Copy A to the IRS and gives Copy B to the borrower.
The form is short. Box 1 shows the student loan interest the lender received during the year, and box 2 is a checkbox for loans made before September 1, 2004 when box 1 leaves out loan origination fees or capitalized interest.
Copy B says the borrower may be able to deduct student loan interest actually paid in 2026, but may not be able to deduct the full amount reported. The current PDF is the 2026 form. You can fill out Copy B free on this page.
Name, address, telephone number and TIN of the filer. The instructions say to use the same name and address on Form 1096.
The borrower's TIN, name and address. The TIN may be truncated to the last four digits on Copy B, but not on the copy filed with the IRS.
Required when the lender files more than one Form 1098-E for the same borrower because of multiple accounts. The IRS encourages an account number on every form.
The interest the lender received during the calendar year. For loans made on or after September 1, 2004, it includes capitalized interest and loan origination fees as described in the regulations.
Checked if box 1 does not include loan origination fees or capitalized interest for loans made before September 1, 2004.
The instructions say a reportable loan is one under a federal, state, local or school program, or one the borrower certifies was taken solely for qualified higher education expenses. Loans under a qualified employer plan are not reported.
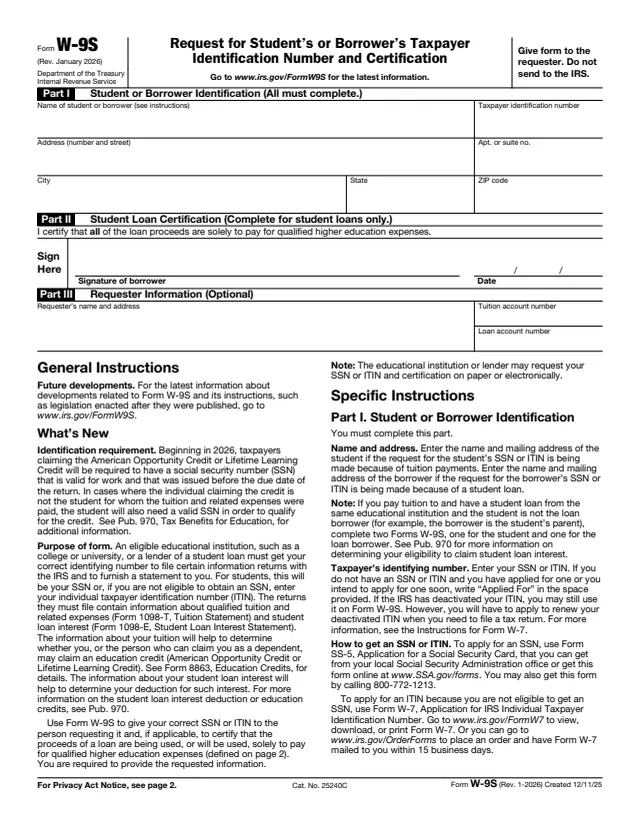
Form W-9S can be used to get the borrower's name, address, TIN and student loan certification. The instructions say using it is optional.
Fill in both names, addresses and TINs, and an account number when the borrower has more than one account with you.
The $600 threshold applies to each borrower, however many loans they have. The instructions allow one form per loan or one form for all of a borrower's loans.
Check it only for loans made before September 1, 2004 when box 1 leaves out loan origination fees or capitalized interest.
Copy A goes to the IRS and Copy B to the borrower, on paper or electronically. You can fill this form free on this page.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions point to Pub. 1099, General Instructions for Certain Information Returns, for when and where to file and for statements to borrowers.
The instructions say the e-file threshold is 10 information returns in total, for returns filed on or after January 1, 2024. The IRS IRIS portal is one way to e-file.
The PDF says Copy A printed from it can't be scanned and a penalty may apply for filing it. Official scannable forms can be ordered at IRS.gov/EmployerForms.
The instructions say a lender may offer consent to receive Form 1098-E electronically as part of a global consent to do business electronically that meets the regulations.
Copy B says a negligence penalty or other sanction may apply if the IRS finds an underpayment of tax because a student loan interest deduction was overstated.
1098-T
56 fields, 4 pages
1040
73 fields, 2 pages

1040
199 fields, 2 pages
W-9S
13 fields, 2 pages
1096
55 fields, 3 pages
1098
41 fields, 4 pages
No tool matches that search.
The instructions set the filing threshold at $600 or more of interest received from a borrower during the year, so a lender that received less may not send one.
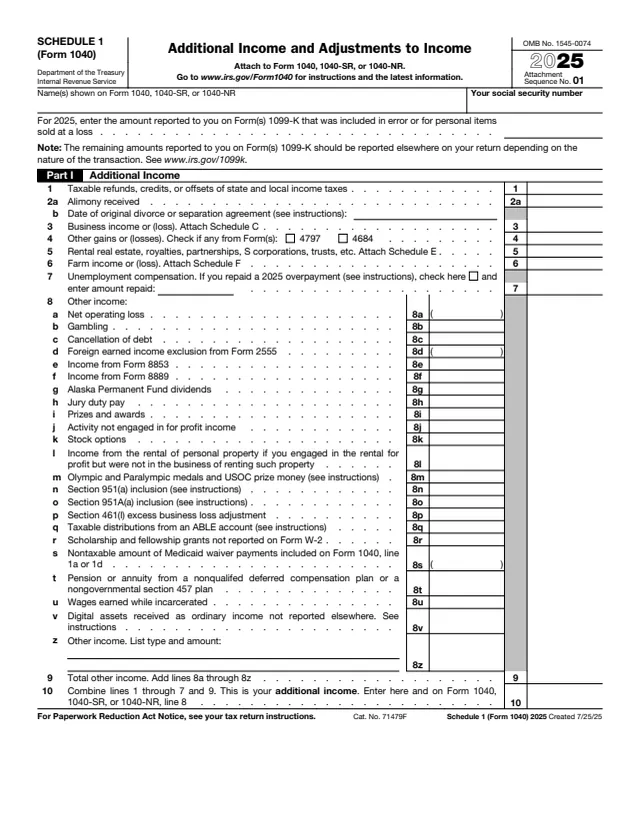
Not always. Copy B says you may not be able to deduct the full amount and points to Pub. 970 and the Student Loan Interest Deduction Worksheet. The 2025 Form 1040 instructions say the worksheet result goes on Schedule 1, line 21, and its line 1 is capped at $2,500.
If checked, box 1 does not include loan origination fees or capitalized interest for loans made before September 1, 2004. Copy B points to Pub. 970 for how to figure any deductible fees or capitalized interest.
Either. The instructions say the lender may file a separate Form 1098-E for each loan or one form for the interest on all of a borrower's loans.
Only if the borrower certifies that all the loan proceeds were used solely for qualified higher education expenses. The instructions say interest on mixed-use loans is not reported.
Copy B says not to contact the lender for explanations of the deduction rules, and points to Pub. 970 and the Instructions for Form 1040 instead.