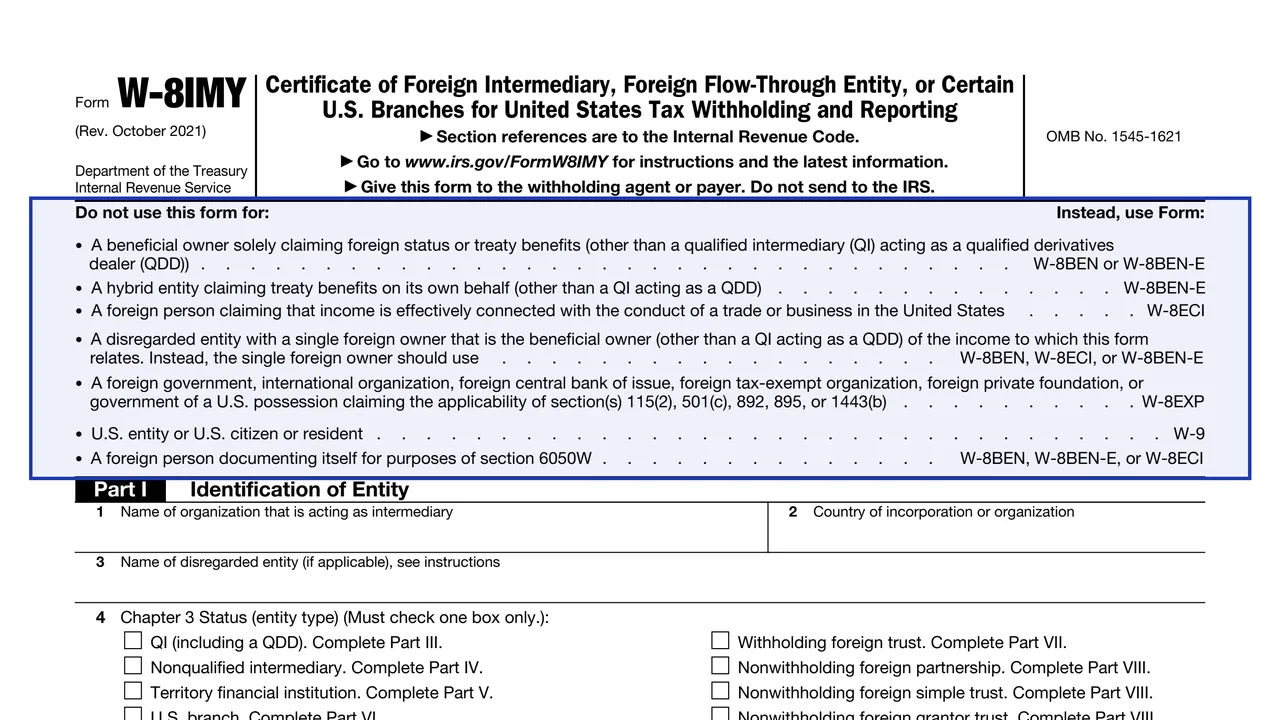
Do not use this form for
A list at the top of page 1 names the cases that use Form W-8BEN, W-8BEN-E, W-8ECI, W-8EXP or W-9 instead.
W-8
Certificate of Foreign Intermediary, Foreign Flow-Through Entity, or Certain U.S. Branches for United States Tax Withholding and Reporting
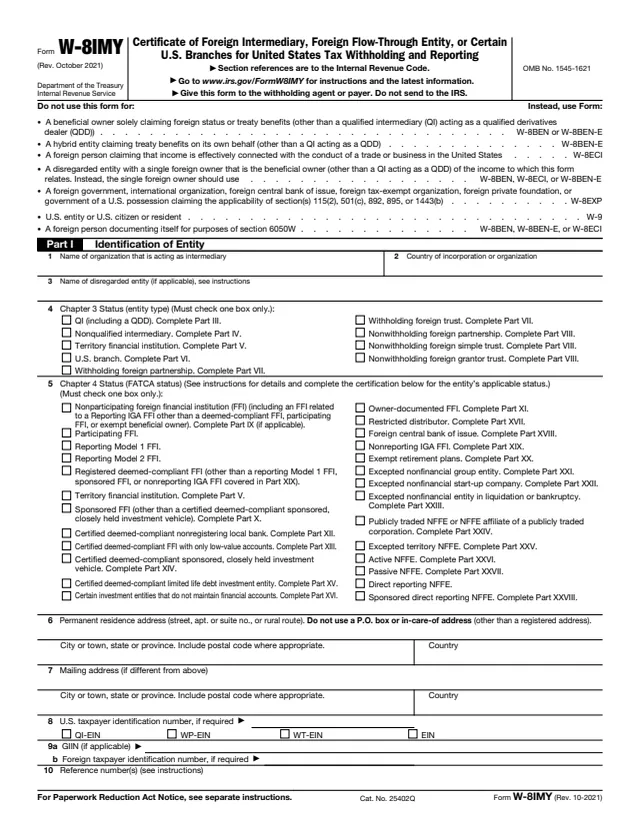
Form W-8IMY is the Certificate of Foreign Intermediary, Foreign Flow-Through Entity, or Certain U.S. Branches for United States Tax Withholding and Reporting. The IRS About Form W-8 IMY page says it may serve to establish foreign status for purposes of sections 1441, 1442, and 1446.
The instructions say it is provided when receiving a reportable amount or withholdable payment on behalf of another person or as a flow-through entity, or when acting as a qualified derivatives dealer (QDD) or qualified securities lender (QSL). The instructions explain that under chapter 3 foreign persons are generally subject to U.S. tax at a 30% rate on certain U.S. source income, and under chapter 4 withholding agents withhold at a 30% rate on withholdable payments to nonparticipating foreign financial institutions. The form says "Give this form to the withholding agent or payer. Do not send to the IRS."
You can fill out Form W-8IMY free in your browser on this page and download it without an account.
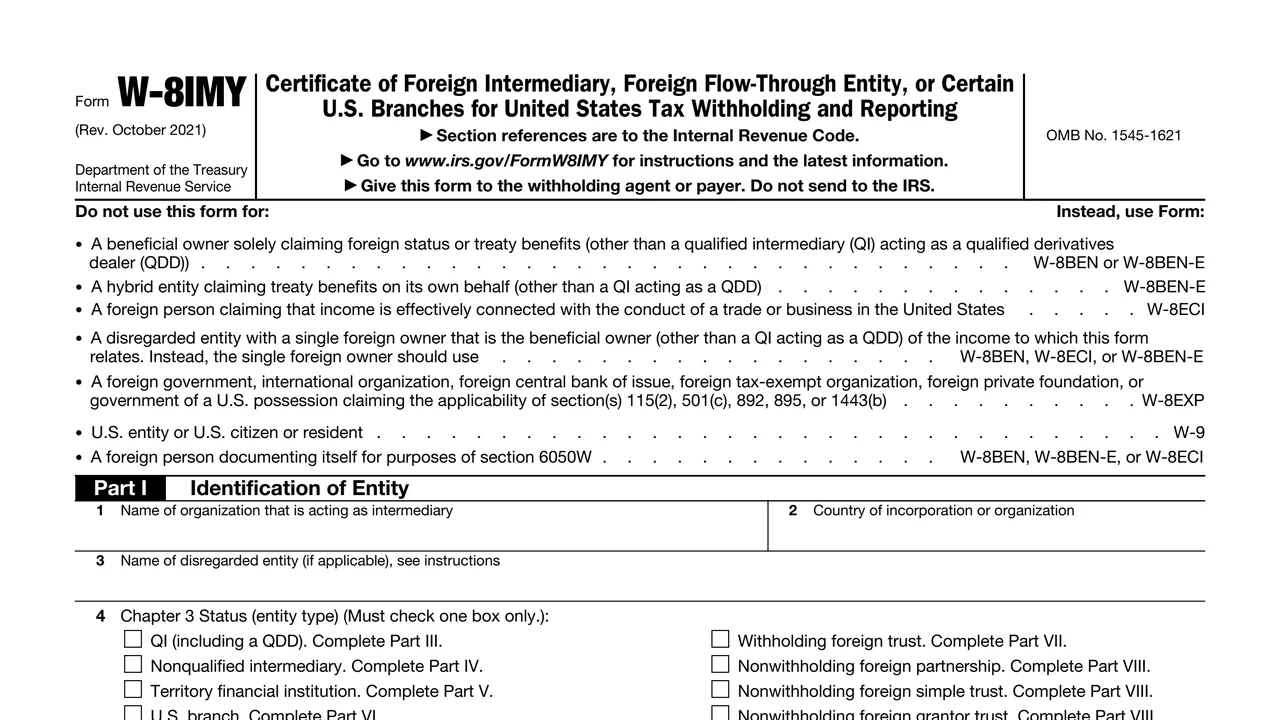
A list at the top of page 1 names the cases that use Form W-8BEN, W-8BEN-E, W-8ECI, W-8EXP or W-9 instead.
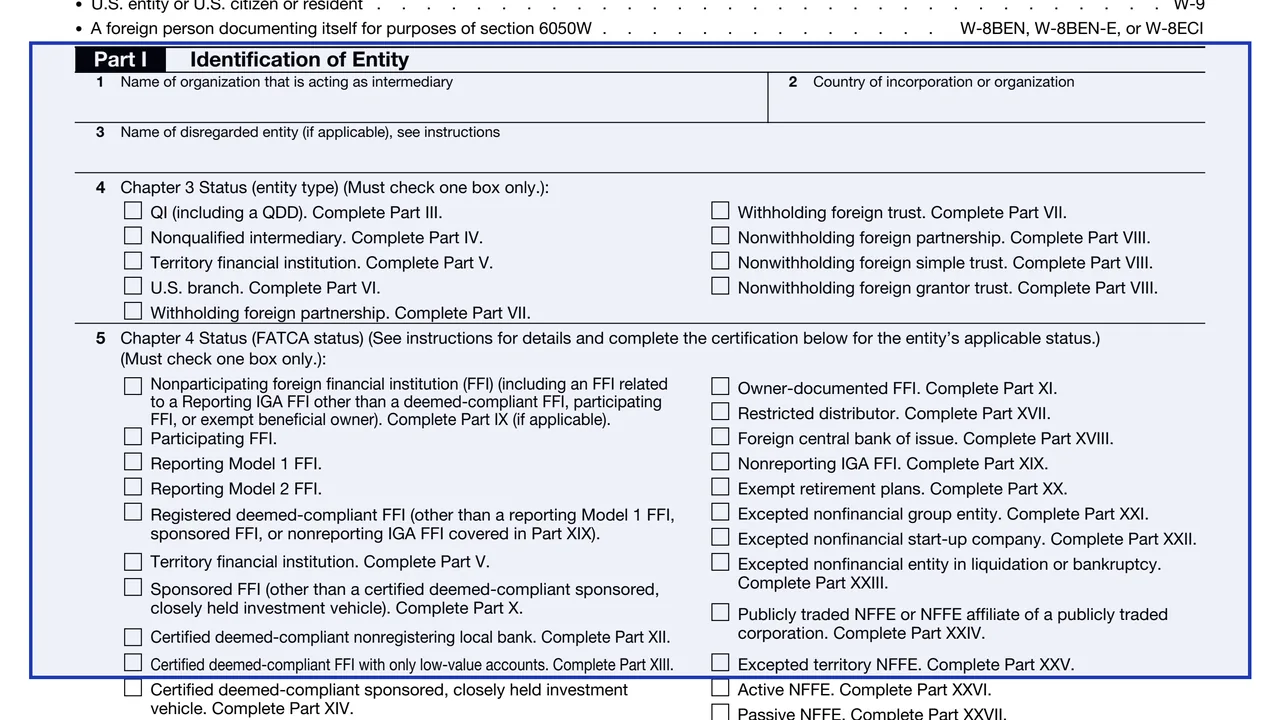
Lines 1 to 10: name, country of organization, disregarded entity name, chapter 3 status, chapter 4 (FATCA) status, addresses, U.S. TIN with QI-EIN, WP-EIN, WT-EIN or EIN boxes, GIIN, foreign TIN and reference numbers.
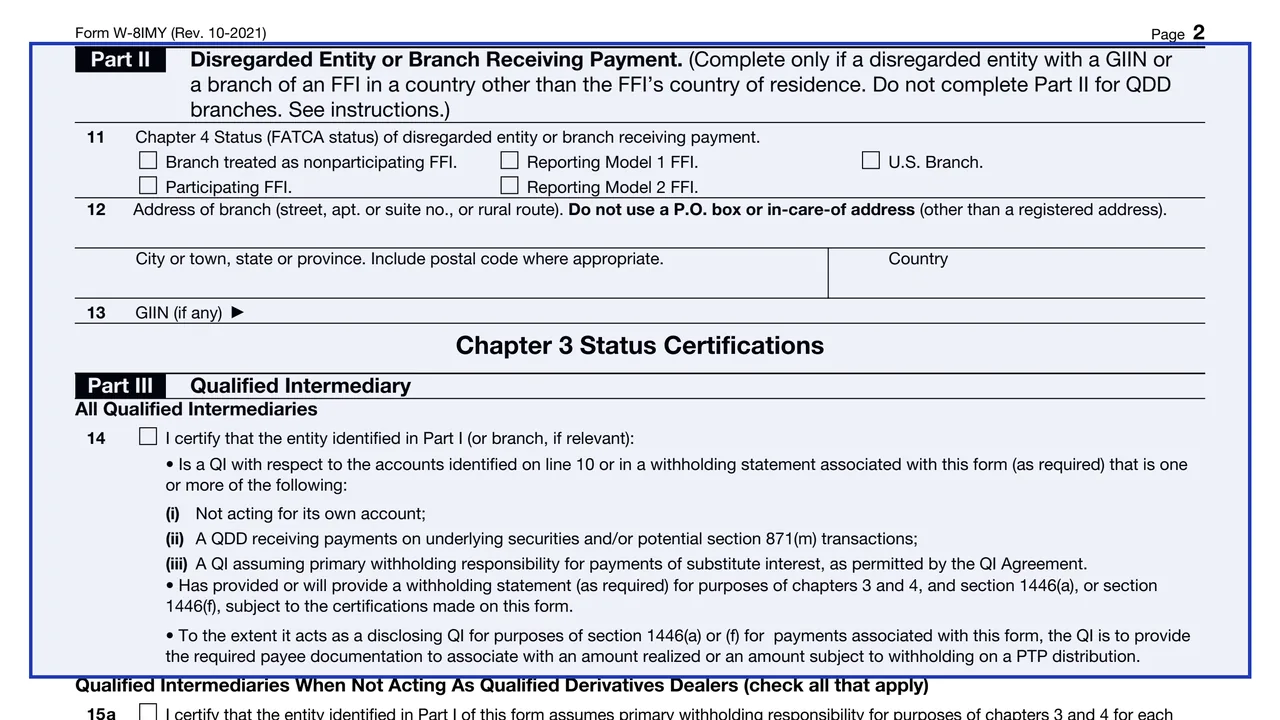
Lines 11 to 13 give the FATCA status, address and GIIN of a disregarded entity with a GIIN or a branch of an FFI in another country that receives the payment.
Certifications for a qualified intermediary or QDD, nonqualified intermediary, territory financial institution, certain U.S. branches, withholding foreign partnership or trust, and nonwithholding foreign partnership, simple trust or grantor trust.
One certification part for each FATCA status checked on line 5, such as sponsored FFI, owner-documented FFI, nonreporting IGA FFI, active NFFE or passive NFFE.
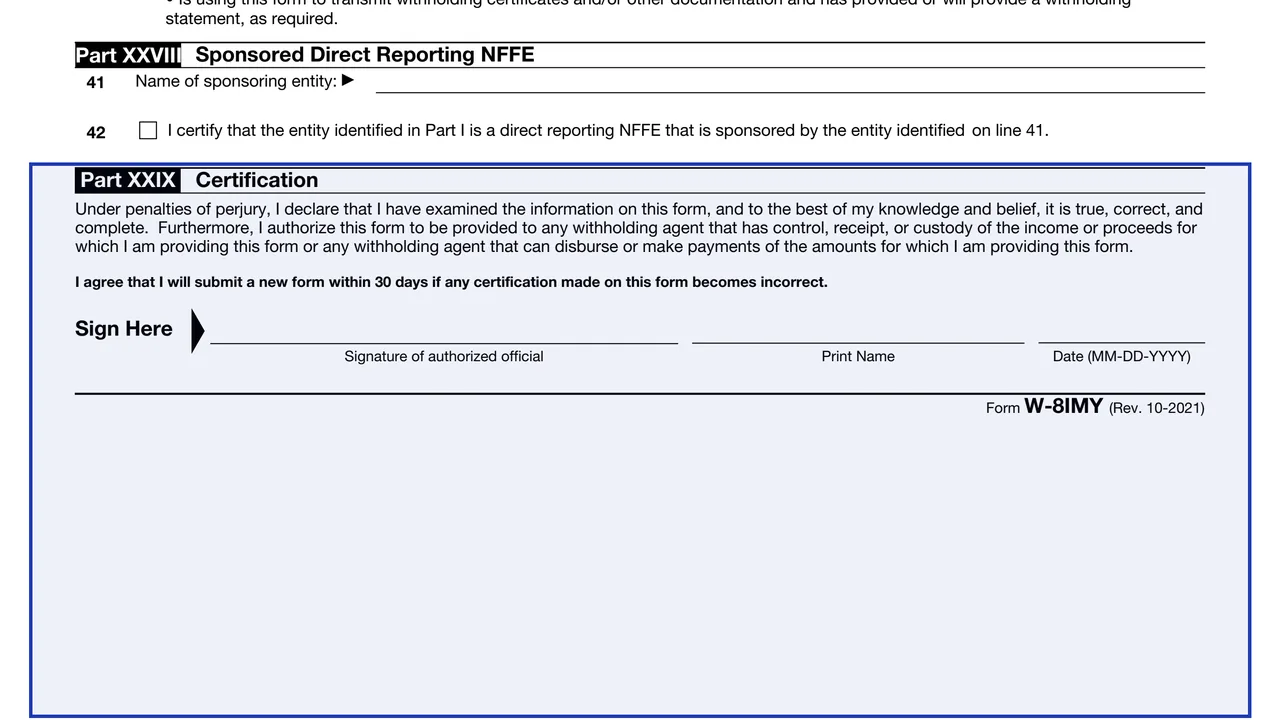
A penalties of perjury declaration, the agreement to submit a new form within 30 days if a certification becomes incorrect, and the signature, printed name and date of an authorized official.
The instructions say entering a name on line 1 represents that you are not the beneficial owner, with stated exceptions. A disregarded entity enters its owner's legal name on line 1 and its own name on line 3 if required.
Check one box for the chapter 3 status and, when required, one box for the chapter 4 status. Each box names the part to complete next, for example Part III for a QI or Part VIII for a nonwithholding foreign partnership.
Line 6 is the permanent residence address, not a P.O. box or in-care-of address except a registered address. On line 8, the instructions say a QI, WP or WT checks its box and enters the EIN issued in that capacity.
Enter a GIIN if the status needs one. The instructions allow "applied for" while registration is pending, and say the requester receives and verifies the GIIN within 90 days. Line 10 holds any reference numbers.
Complete the certifications in the parts your boxes point to. The instructions say a withholding statement allocates each payment to each payee or pool and forms an integral part of the certificate.
A person authorized to sign under penalties of perjury signs and dates it. The instructions say a withholding agent may allow an electronic signature, and simply typing a name into the signature line is not one.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Give it to the withholding agent or payer who asked for it. The form says "Do not send to the IRS." An FFI may also request it to document an account for chapter 4 purposes.
The instructions say to give it before income is paid, credited, or allocated to the account. Without it, the withholding agent may withhold at the 30% rate, backup withhold, or withhold under section 1446.
The instructions say a separate Form W-8IMY generally goes to each withholding agent. A single form may cover multiple branches receiving payments from the same agent, with a schedule for each branch.
The instructions say it generally remains valid until the status changes or a change in circumstances makes it incorrect. Associated certificates, documentary evidence and withholding statements are not valid indefinitely.
The instructions say to notify the withholding agent within 30 days of a change in circumstances that makes the form or its associated documents incorrect.
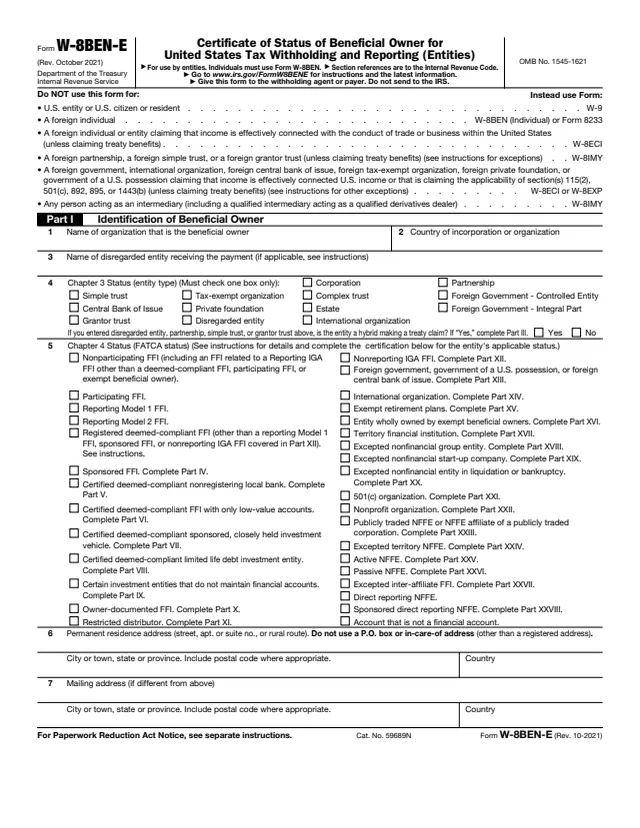
W-8BEN-E
179 fields, 8 pages
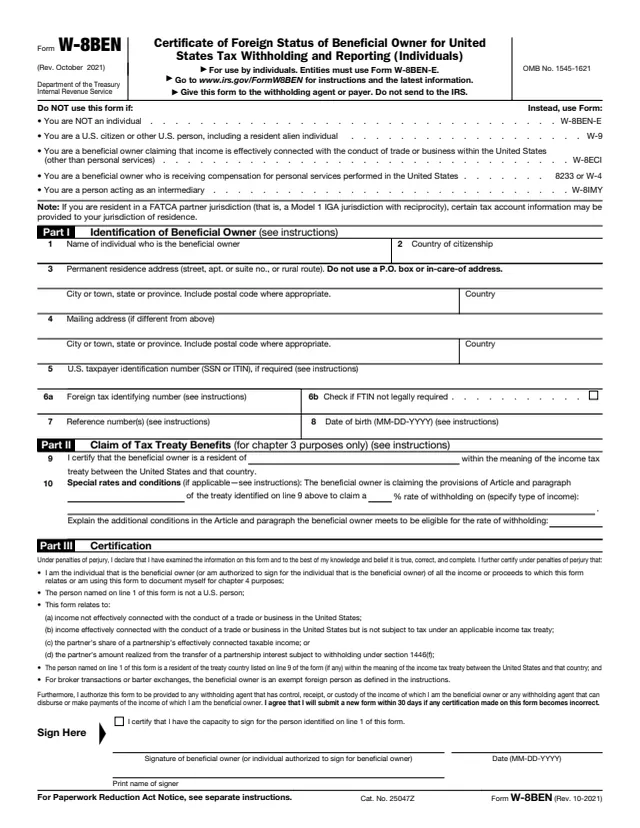
W-8
23 fields, 1 page
W-8
36 fields, 1 page
W-8EXP
67 fields, 3 pages
W-9
23 fields, 6 pages
8233
51 fields, 2 pages
The form is completed by an entity, not an individual, and given to the withholding agent or payer that requests it. The instructions say this is generally the person from whom you receive the payment, the person who credits your account, or a partnership that allocates income to you.
No tool matches that search.
No. The form says to give it to the withholding agent or payer and not to send it to the IRS.
The form says a beneficial owner solely claiming foreign status or treaty benefits, other than a QI acting as a QDD, uses Form W-8BEN or W-8BEN-E. A hybrid entity claiming treaty benefits on its own behalf uses W-8BEN-E.
The instructions say it generally remains valid until the entity's status or circumstances change in a way that makes it incorrect. Certificates and statements attached to it do not share that indefinite validity.
The instructions describe it as an allocation of each payment, by income type, to each payee or pool. It forms an integral part of the certificate and is covered by the penalties of perjury statement.
The instructions say an entity registering with the IRS may write "applied for" on line 9a, and the requester receives and verifies the GIIN within 90 days.
The instructions say a withholding agent may allow an electronic signature that shows it was signed by an authorized person, for example with a time and date stamp.