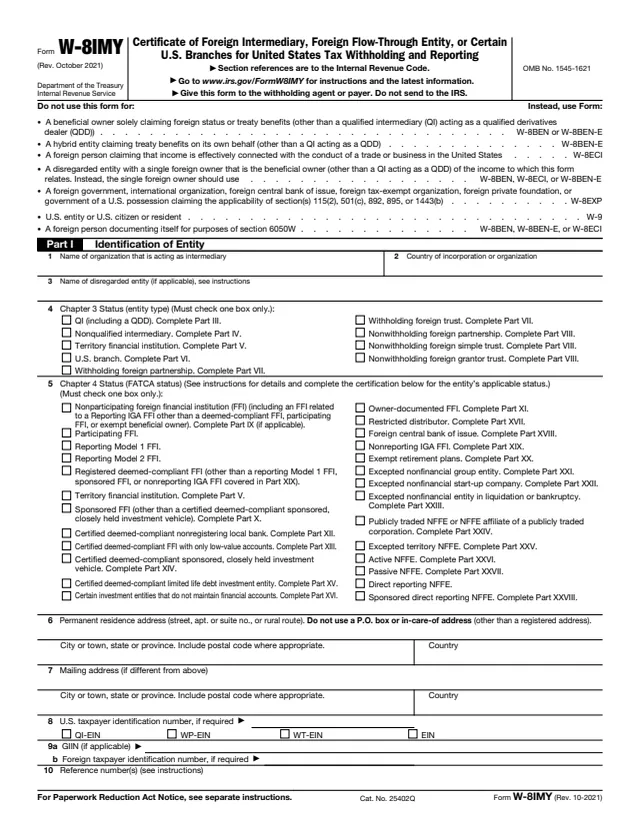
Part I: Identification of Beneficial Owner
Lines 1 to 10: name, country of incorporation, chapter 3 status, chapter 4 (FATCA) status, permanent residence and mailing addresses, U.S. TIN, GIIN, foreign TIN and reference numbers.
W-8BEN-E
Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities)
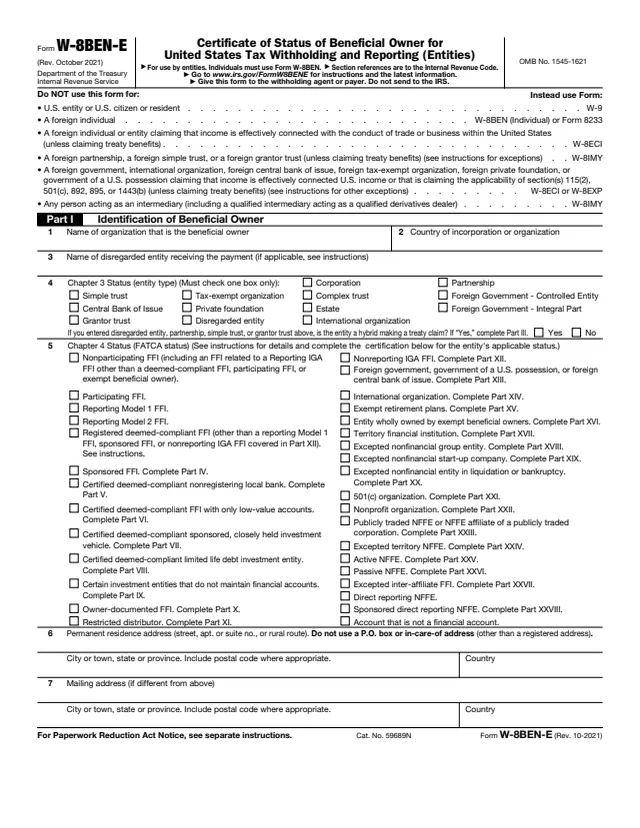
Form W-8BEN-E is the Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities). The instructions say it is used by foreign entities to document their statuses for purposes of chapter 3 and chapter 4, as well as for certain other Code provisions. The form says it is for use by entities and that individuals use Form W-8BEN.
A withholding agent or payer, or a foreign financial institution (FFI) that holds the entity's account, usually asks for it. The instructions say a withholding agent may rely on a properly completed form to treat a payment as made to a foreign person who beneficially owns it and, if applicable, to apply a reduced rate of, or exemption from, withholding under an income tax treaty.
The form says "Give this form to the withholding agent or payer. Do not send to the IRS." Part I identifies the entity, Part III holds any treaty claim, Parts IV to XXVIII hold the certification for the chapter 4 status checked, and Part XXX is the signature. You can fill out Form W-8BEN-E free in your browser on this page and download it without an account.
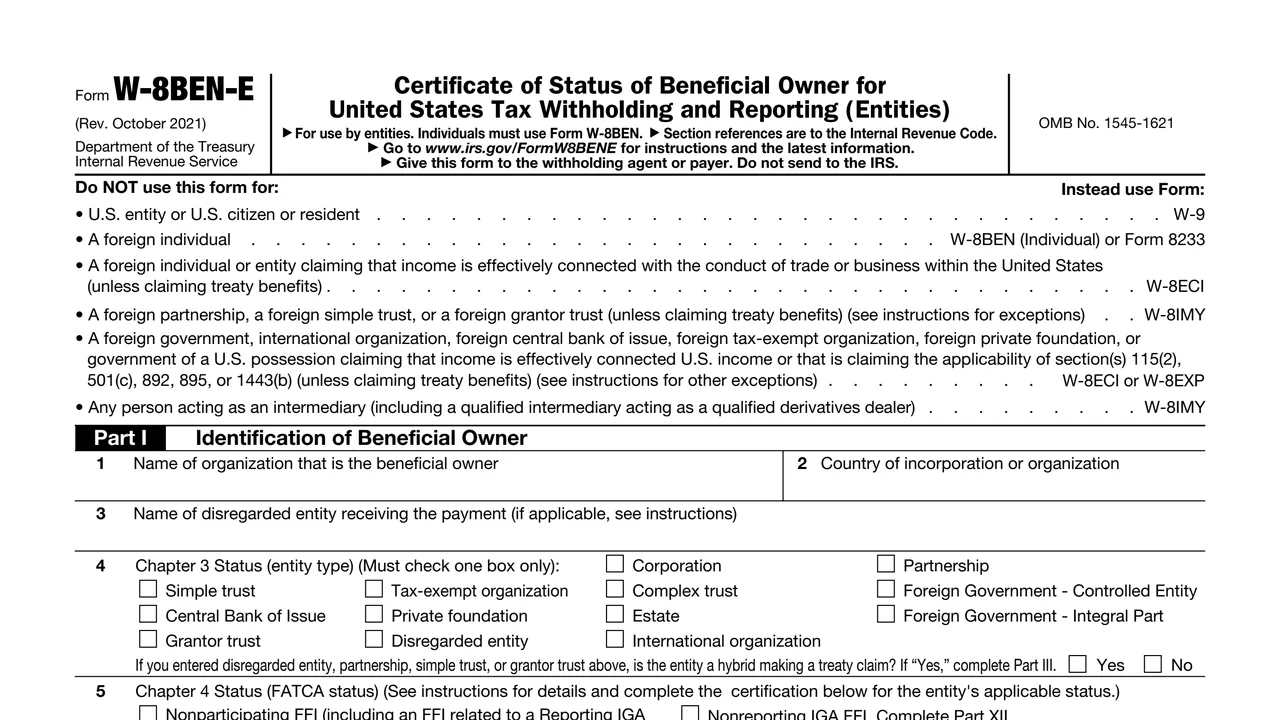
Lines 1 to 10: name, country of incorporation, chapter 3 status, chapter 4 (FATCA) status, permanent residence and mailing addresses, U.S. TIN, GIIN, foreign TIN and reference numbers.
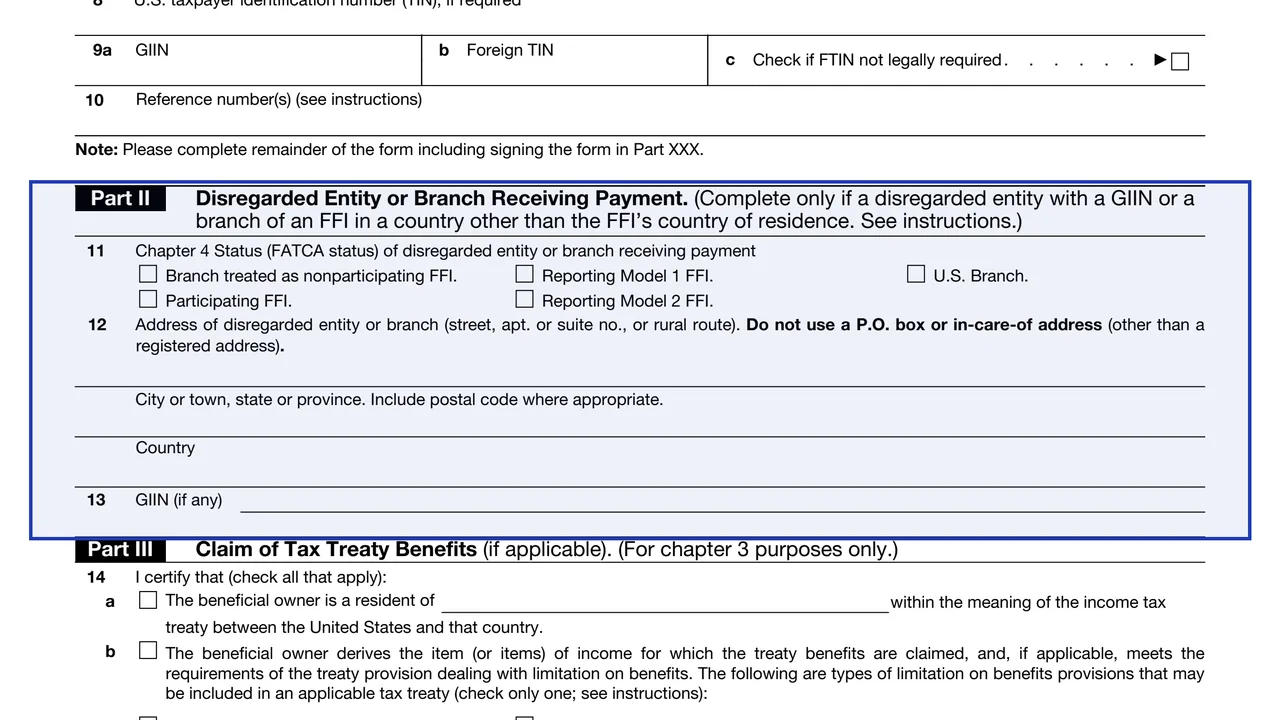
Lines 11 to 13, completed only for a disregarded entity with a GIIN or a branch of an FFI in a country other than the FFI's country of residence.
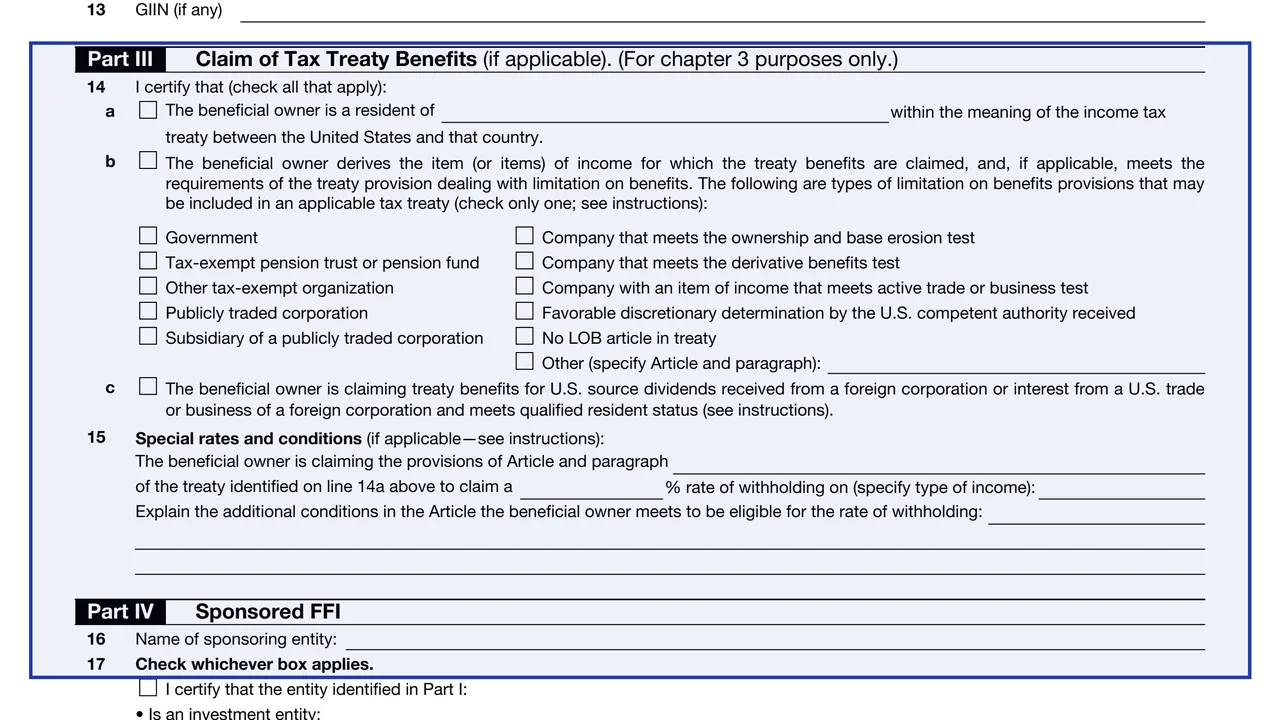
Lines 14 and 15: treaty country of residence, the limitation on benefits provision that applies, qualified resident status, and any special rate and conditions.
One part for each chapter 4 status that needs one, such as sponsored FFI, nonreporting IGA FFI, active NFFE and passive NFFE. Only the part for the status checked on line 5 is completed.
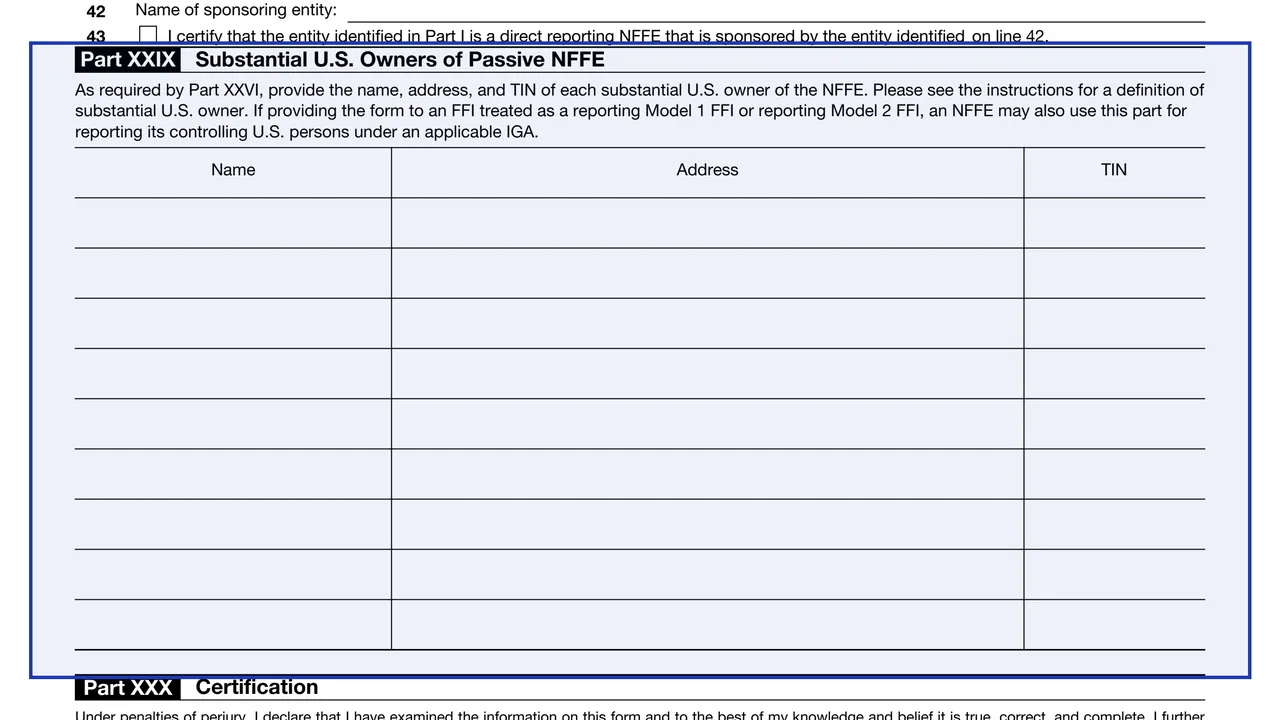
A table for the name, address and TIN of each substantial U.S. owner or controlling U.S. person of a passive NFFE.
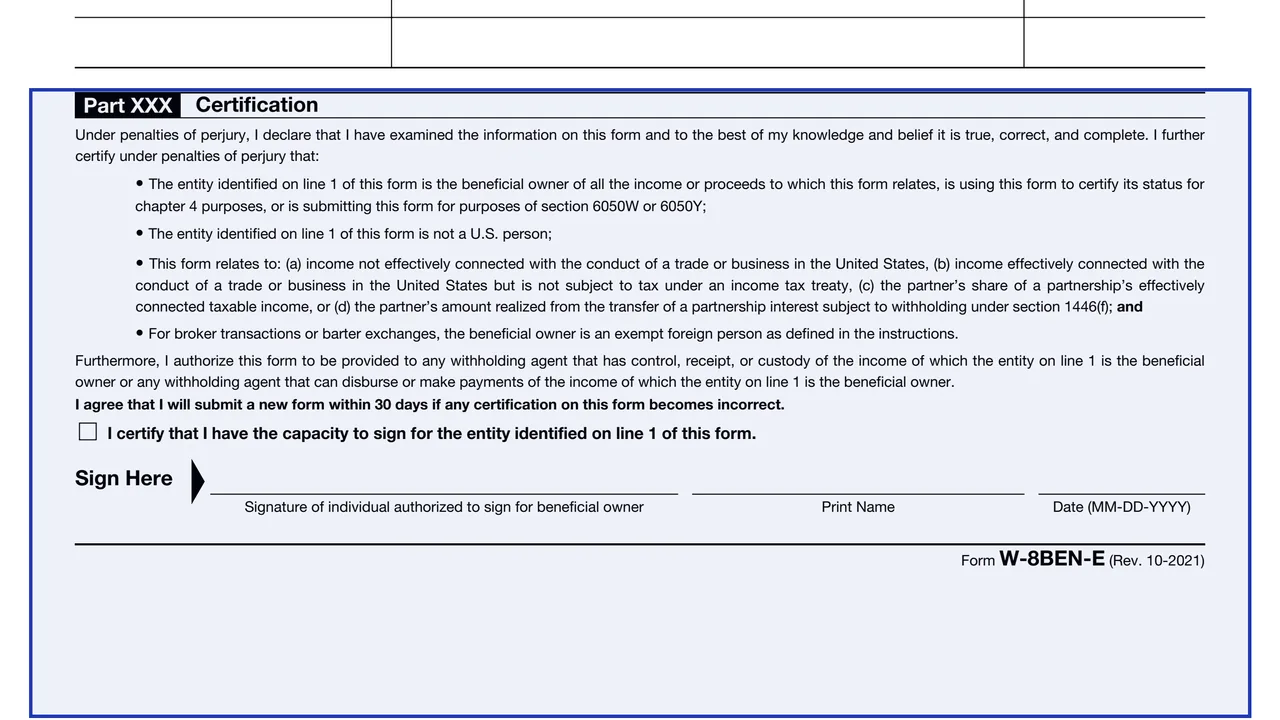
Statements made under penalties of perjury, a box certifying capacity to sign for the entity, and the signature, printed name and date.
Enter the entity's name and country of incorporation or organization. The instructions say a disregarded entity or branch enters the legal name of its owner on line 1, not its business name.
Check one box for the chapter 3 status under U.S. tax principles. A partnership, disregarded entity, simple trust or grantor trust also answers the hybrid entity treaty question.
Check one chapter 4 (FATCA) status. The form says to complete the certification part named next to that status, for example Part XXV for an active NFFE.
Enter the permanent residence address (the form says no P.O. box or in-care-of address other than a registered address), any mailing address, a U.S. TIN if required, the GIIN, the foreign TIN and any reference numbers.
Enter the treaty country on line 14a, check one limitation on benefits provision on line 14b, and use line 15 for a special rate, naming the article, paragraph, rate and type of income.
An authorized representative or officer checks the capacity box, signs, prints the name and dates it. The instructions say an agent signing under a power of attorney attaches it, and Form 2848 may be used.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say not to send it to the IRS and to give it to the person requesting it, generally the payer, the party crediting the account, a partnership allocating income, or an FFI documenting an account.
Before the payment is made, credited or allocated. The instructions say that without it the withholding agent may have to withhold at the 30% rate, the backup withholding rate, or the rate under section 1446.
The instructions say generally from the date signed until the last day of the third succeeding calendar year, unless a change in circumstances makes information on it incorrect.
The certification says the entity agrees to submit a new form within 30 days if any certification on it becomes incorrect.
The instructions say a separate Form W-8BEN-E is generally given to each withholding agent, and an agent may ask for one per type of income.
The instructions say a withholding agent may allow an electronic signature, and that simply typing a name into the signature line is not one.
W-8
23 fields, 1 page
W-9
23 fields, 6 pages
W-8
148 fields, 8 pages
W-8
36 fields, 1 page
W-8EXP
67 fields, 3 pages
8233
51 fields, 2 pages
A foreign entity completes it and gives it to the withholding agent, payer or FFI that requested it. The form is signed by an authorized representative or officer of the entity.
No tool matches that search.
No. The form says to give it to the withholding agent or payer and not to send it to the IRS.
No. The form says it is for use by entities and that individuals use Form W-8BEN. The instructions also mention Form 8233 for certain nonresident alien individuals.
The instructions say generally until the last day of the third calendar year after the year it is signed, unless a change in circumstances makes it incorrect. Some forms remain in effect indefinitely under conditions the regulations set.
It is the entity's FATCA status. The form lists each status and the part to complete for it, such as Part XXV for an active NFFE or Part XXVI for a passive NFFE.
Only in some cases. The instructions list examples, such as claiming treaty benefits without a foreign TIN on line 9b, and items of income for which a TIN is not required to claim treaty benefits.
The instructions say an authorized representative or officer of the beneficial owner, participating payee or account holder signs and dates it, after checking the box certifying capacity to sign.
The instructions say the withholding agent may have to withhold at the 30% rate, the backup withholding rate, or the rate under section 1446.