Lines 1 to 4: identification
Name of the beneficial owner, country of incorporation or organization, the name of a disregarded entity receiving the payments, and the type of entity.
W-8
Certificate of Foreign Person's Claim That Income Is Effectively Connected With the Conduct of a Trade or Business in the United States
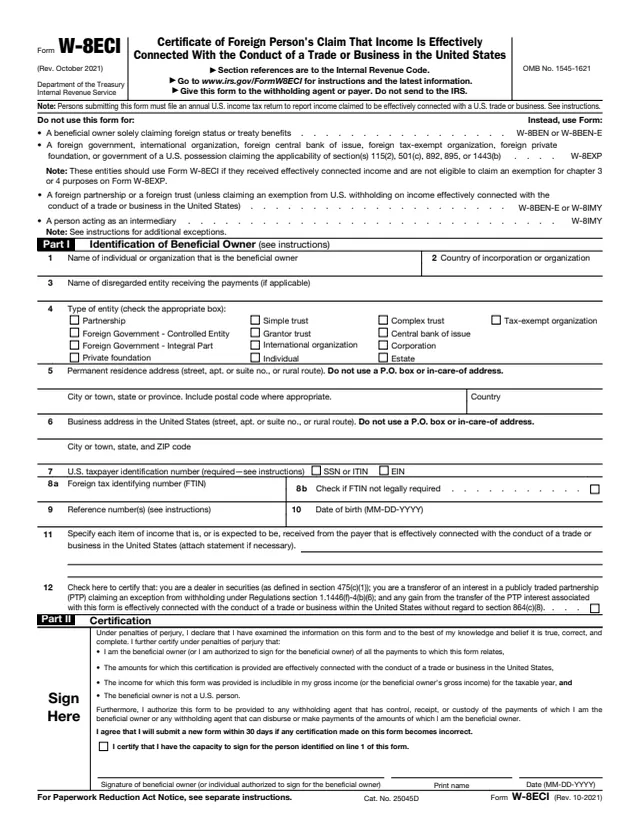
Form W-8ECI is the Certificate of Foreign Person's Claim That Income Is Effectively Connected With the Conduct of a Trade or Business in the United States. A foreign person who is the beneficial owner of U.S. source income that is, or is deemed to be, effectively connected with a U.S. trade or business gives it to the withholding agent or payer.
The instructions explain why it matters. Foreign persons are generally subject to U.S. tax at a 30% rate on income from U.S. sources, but no withholding under section 1441 or 1442 is required on effectively connected income that is includible in the beneficial owner's gross income. The instructions add that this exception does not apply to personal services income performed by an individual.
The form says "Do not send to the IRS." It also notes that persons submitting it file an annual U.S. income tax return to report the income claimed as effectively connected. You can fill out the PDF free in your browser on this page and download it without an account.
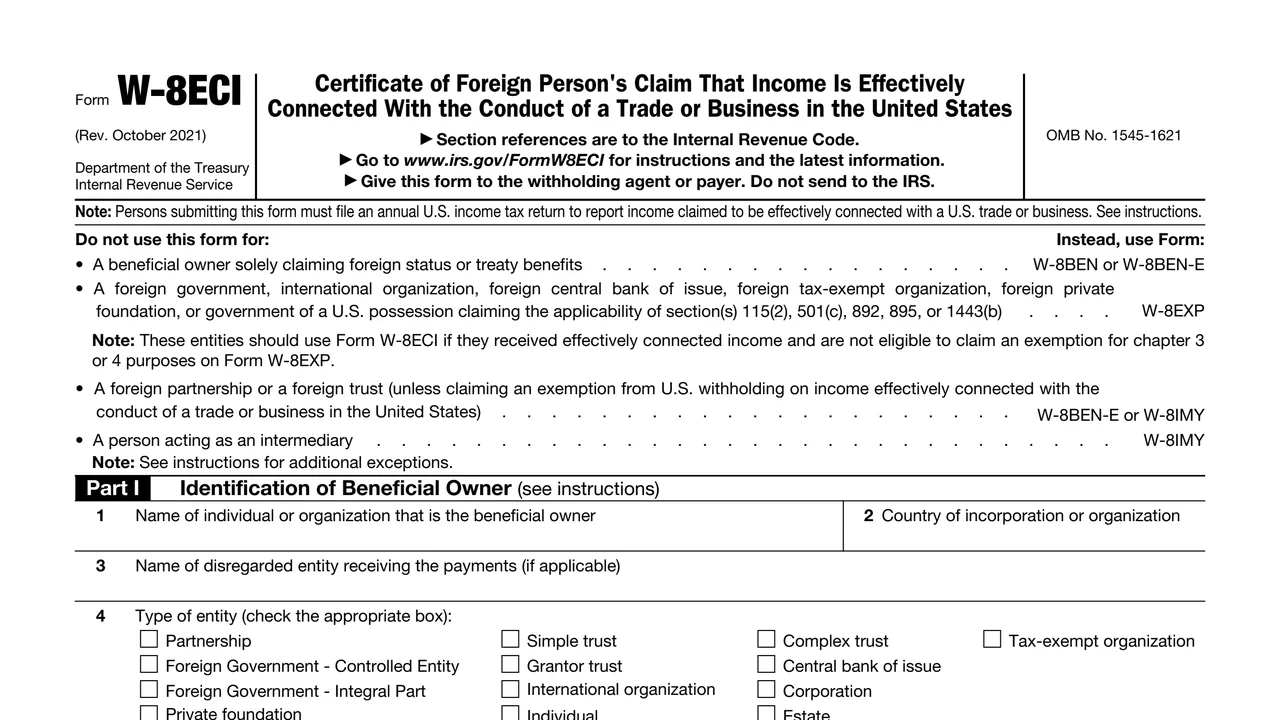
Name of the beneficial owner, country of incorporation or organization, the name of a disregarded entity receiving the payments, and the type of entity.
Permanent residence address and business address in the United States. The form says not to use a P.O. box or in-care-of address on either line.
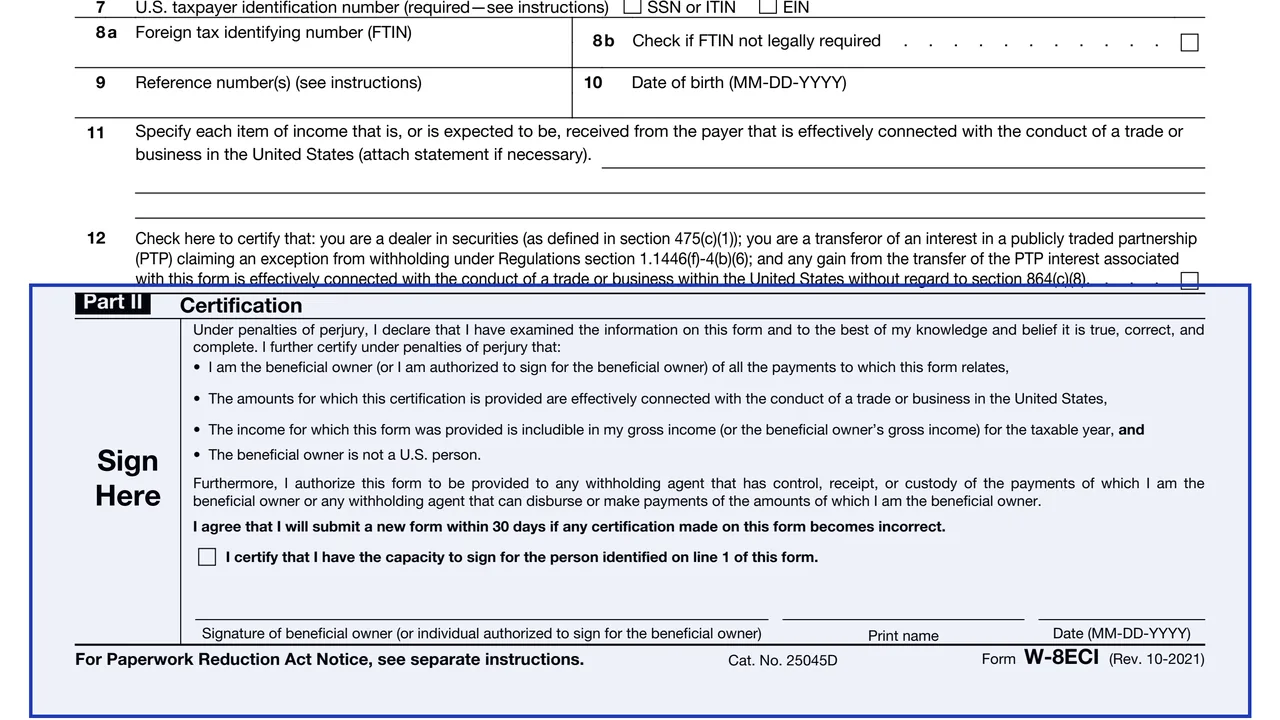
U.S. taxpayer identification number, foreign tax identifying number (FTIN) with a box if it is not legally required, reference numbers and date of birth.
Each item of income received or expected from the payer that is effectively connected with a U.S. trade or business, with a statement attached if needed.
A check box for a dealer in securities transferring a PTP interest and claiming the exception from withholding under Regulations section 1.1446(f)-4(b)(6).
Statements made under penalties of perjury, a box certifying capacity to sign, and the signature, printed name and date.
Enter the beneficial owner's name and country. For a corporation, the country of incorporation; for an individual, the country of residence for tax purposes. A disregarded entity's foreign single owner completes and signs the form and may put the entity's name on line 3.
Check the type of entity. The instructions say the foreign government choice is split into an integral part of a foreign government and an entity controlled by a foreign government.
Line 5 is the address in the country where the owner claims residence for income tax, not a financial institution's address or a mailing-only address. Line 6 is the U.S. business address.
The instructions say a U.S. TIN is required for the form to be valid. Individuals generally enter an SSN, or an ITIN from Form W-7 if not eligible for an SSN. Entities use an EIN from Form SS-4.
Enter an FTIN on line 8a when the instructions call for one, or check 8b if it is not legally required. Line 9 can hold an account name and number, line 10 a date of birth as MM-DD-YYYY, and line 11 each item of effectively connected income.
Check line 12 only for the securities dealer exception. The beneficial owner, or an authorized representative or officer, signs and dates. An agent under a power of attorney attaches it, and Form 2848 can be used.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Give the form to the withholding agent or payer, usually the person who pays or credits the income. The form says not to send it to the IRS. A separate form generally goes to each withholding agent.
The instructions say to provide it before income is paid, credited or allocated. Without it, the withholding agent withholds at the 30% rate or the backup withholding rate.
The form notes that persons submitting it file an annual U.S. income tax return to report income claimed to be effectively connected with a U.S. trade or business.
Generally from the date signed until the last day of the third succeeding calendar year, unless a change in circumstances makes it incorrect. The instructions give the example of a form signed September 30, 2020, valid through December 31, 2023.
The certification includes an agreement to submit a new form within 30 days if any certification on the form becomes incorrect.
For income that is not effectively connected, the instructions point to Form W-8BEN, W-8BEN-E, W-8EXP or W-8IMY alongside Form W-8ECI.
W-8
23 fields, 1 page
W-8BEN-E
179 fields, 8 pages
W-8EXP
67 fields, 3 pages
W-8
148 fields, 8 pages
8233
51 fields, 2 pages
W-9
23 fields, 6 pages
The form is completed by the foreign beneficial owner of the income, or by someone authorized to sign for it, and handed to the withholding agent or payer.
No tool matches that search.
No. The form says to give it to the withholding agent or payer and not to send it to the IRS.
Yes. The instructions say a TIN on line 7 is required for the form to be valid. It can be an SSN, an EIN or an ITIN.
Generally until the last day of the third succeeding calendar year after it is signed, unless a change in circumstances makes information on it incorrect.
The form says a beneficial owner solely claiming foreign status or treaty benefits uses Form W-8BEN or W-8BEN-E instead of W-8ECI.
The instructions say the withholding exception does not apply to personal services income performed by an individual, and point to Form 8233 or Form W-4.
The instructions say a withholding agent can allow an electronic signature, and that simply typing a name into the signature line is not an electronic signature.