Who should use this form
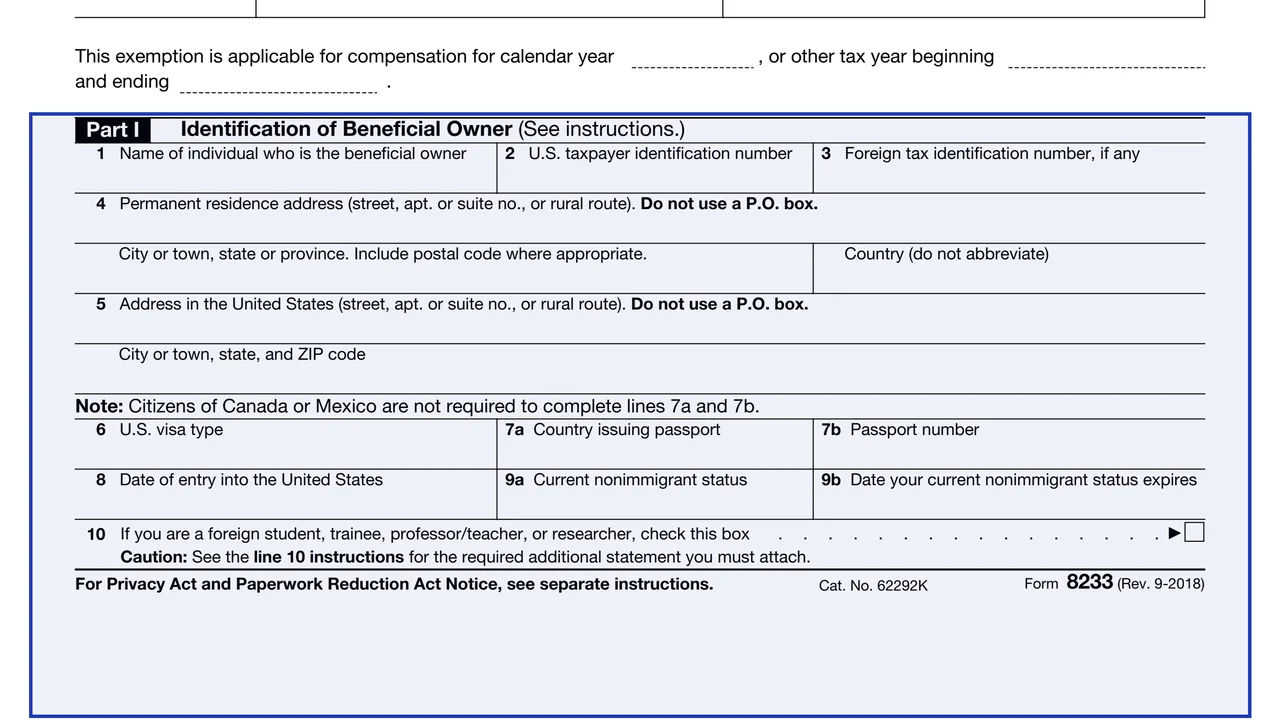
A table at the top of page 1 lists the income the form covers and the cases that use Form W-4 or Form W-8BEN instead, followed by the tax year the exemption applies to.
8233
Exemption From Withholding on Compensation for Independent (and Certain Dependent) Personal Services of a Nonresident Alien Individual
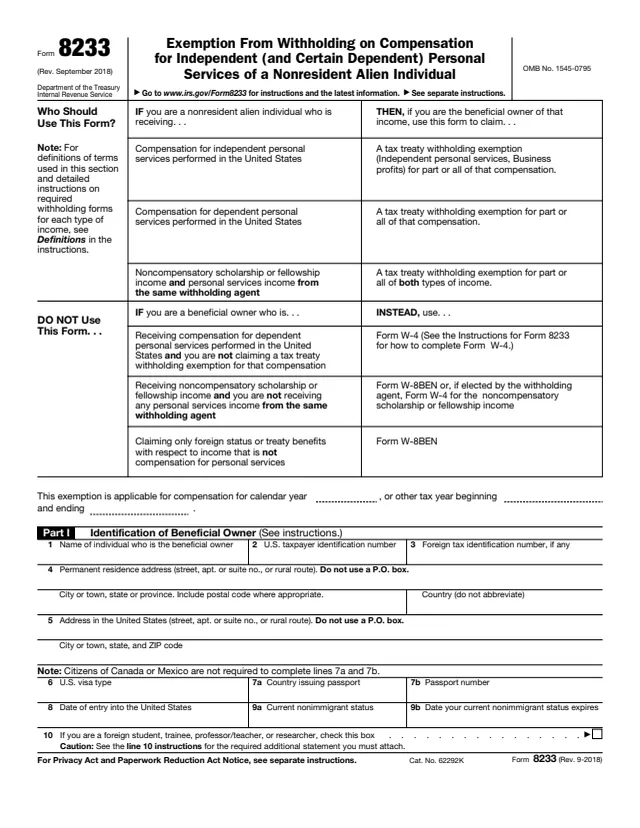
Form 8233 is the Exemption From Withholding on Compensation for Independent (and Certain Dependent) Personal Services of a Nonresident Alien Individual. The About page says nonresident alien individuals use it to claim exemption from withholding on compensation for personal services because of an income tax treaty.
The instructions say section 1441 generally requires 30% withholding on compensation for independent personal services, and that some payments may be exempt from withholding because of a tax treaty. The individual completes the form and gives it to the withholding agent, which in most cases is the person who pays the income. The form can also cover noncompensatory scholarship or fellowship income, but only together with a treaty claim for personal services income from the same withholding agent.
The withholding agent reviews the form, signs Part IV if satisfied, and sends a copy to the IRS. This page hosts the September 2018 revision of the form; the current instructions were revised in December 2025. You can fill out the PDF free in your browser on this page and download it without an account.
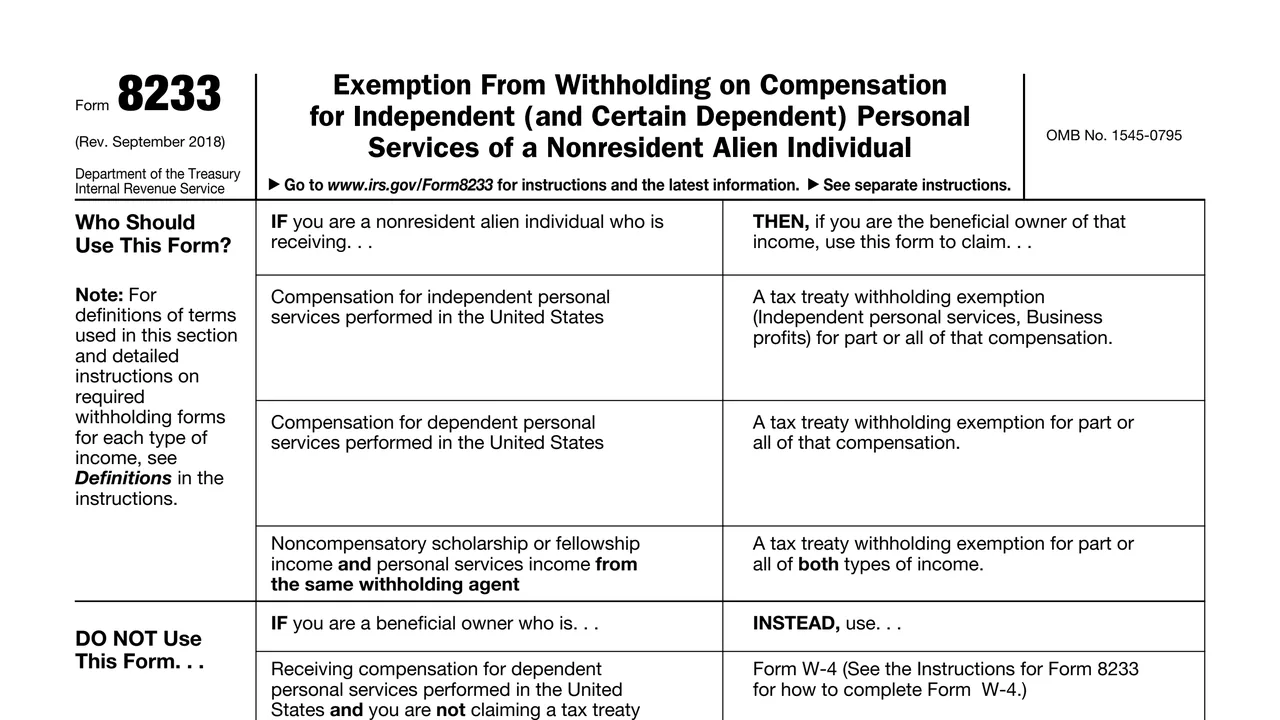
A table at the top of page 1 lists the income the form covers and the cases that use Form W-4 or Form W-8BEN instead, followed by the tax year the exemption applies to.
Lines 1 to 10: name, U.S. and foreign taxpayer identification numbers, permanent and U.S. addresses, visa type, passport, date of entry, nonimmigrant status and the student or researcher box.
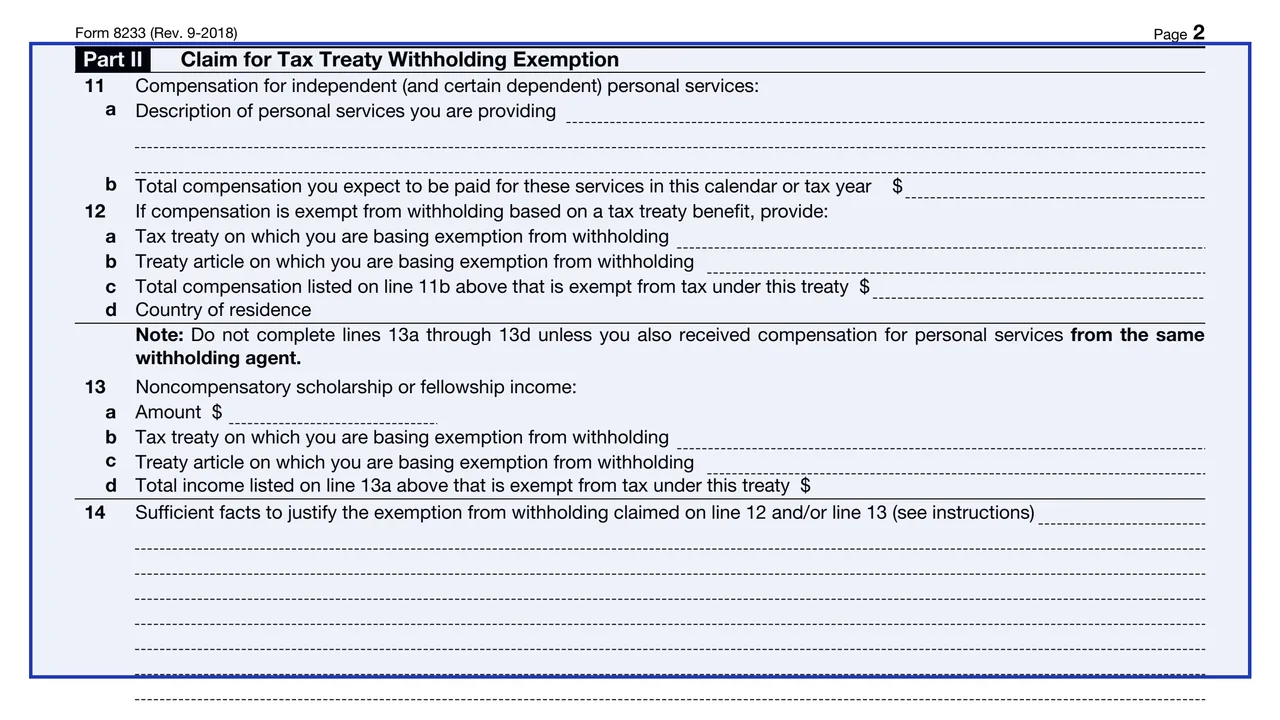
A description of the services, the total compensation expected, and the treaty, article, exempt amount and country of residence behind the claim.
Noncompensatory scholarship or fellowship income and its treaty claim, then the facts that justify the exemption claimed on line 12 or 13.
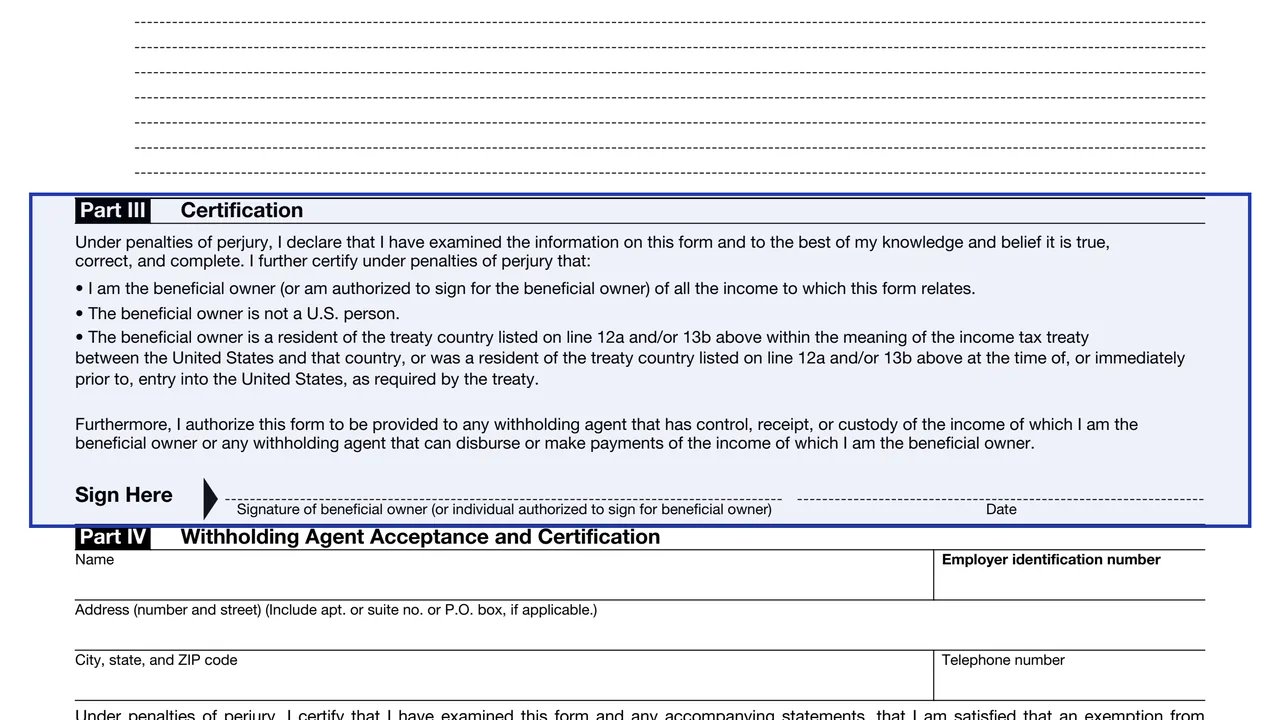
The beneficial owner certifies under penalties of perjury that they own the income, are not a U.S. person and are a resident of the treaty country as the treaty requires, then signs.
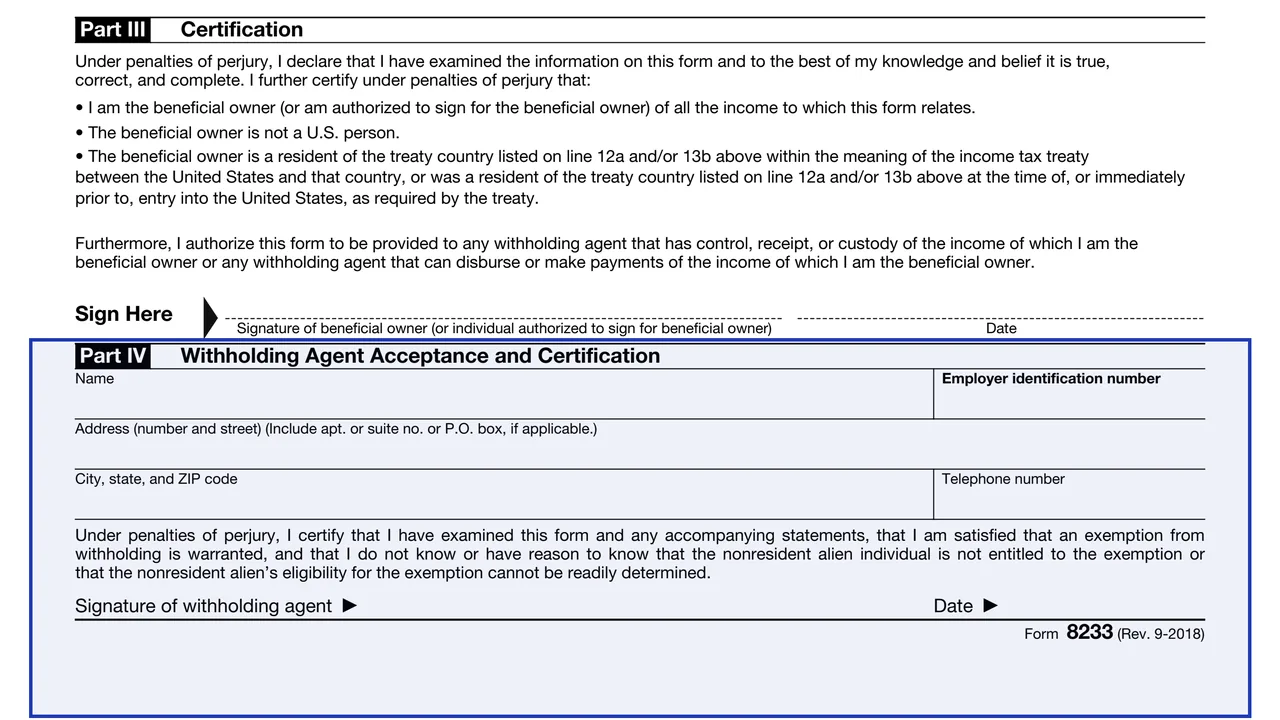
The withholding agent's name, EIN, address and telephone number, and its certification that an exemption from withholding is warranted.
Enter the calendar year or other tax year above Part I. The instructions say a separate Form 8233 is completed for each tax year, each withholding agent and each type of income.
Enter a U.S. taxpayer identification number, in most cases an SSN. The instructions say someone without an SSN who is not eligible for one gets an ITIN with Form W-7; a copy of a completed Form W-7 or SS-5 may be attached while a number is pending.
Line 4 is the permanent residence address, not a P.O. box. Enter the visa type, or None, the date of entry, the nonimmigrant status and its expiration date, or DS for duration of status. Citizens of Canada or Mexico skip lines 7a and 7b.
Students, trainees, professors, teachers and researchers check the box and attach the statement shown in Appendix A or Appendix B of Pub. 519.
Describe the services, for example give three lectures at XYZ University, and enter the expected compensation. Name the treaty and article, write All or the exact exempt amount, enter the country of residence and give facts that support the claim.
Sign Part III and give the form to the withholding agent. The agent completes Part IV if satisfied that the exemption is warranted.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The nonresident alien gives the completed form to the withholding agent. The instructions say not to send it to the IRS comments address but to give it to the withholding agent.
The withholding agent makes three copies with all attachments: one for the individual, one for its records, and one forwarded to the IRS within 5 days of acceptance.
The instructions give Department of the Treasury, Internal Revenue Service, Philadelphia, PA 19255-0725, or fax 267-941-1365, limited to 25 pages at one time.
The exemption applies back to the first payment the form covers, though the withholding agent waits at least 10 days after properly mailing the form to see whether the IRS objects.
The instructions say the withholding agent does not accept the form, and withholds, if it knows or has reason to know a statement may be false or that eligibility cannot be readily determined.
Leaving out the tax year, missing the line 10 statement, claiming a treaty or a treaty benefit that does not exist, too little detail on lines 11 to 14, and no Part III certification.
W-8
23 fields, 1 page
W-4
48 fields, 5 pages
W-7
69 fields, 1 page
13930
133 fields, 6 pages
The form's own table says who should use it. The nonresident alien who is the beneficial owner of the income completes it, and the withholding agent accepts it.
No tool matches that search.
The individual gives it to the withholding agent, not to the IRS. The withholding agent forwards a copy to the IRS within 5 days of accepting it.
The withholding agent, after reviewing the form and being satisfied that the exemption from withholding is warranted.
No. The instructions say a separate form is completed for each tax year, each withholding agent and each type of income.
The instructions say section 1441 generally requires 30% withholding on compensation for independent personal services, and dependent personal services are withheld sometimes at 30% and sometimes at graduated rates.
Only noncompensatory scholarship or fellowship income paired with a treaty claim for personal services income from the same withholding agent. Otherwise the instructions point to Form W-8BEN.
The instructions say someone not eligible for an SSN gets an ITIN by filing Form W-7 with the required documentation, and a copy of a completed Form W-7 or SS-5 may be attached while a number is pending.
The instructions say the IRS typically cannot accept Form 8233 from them because the exemption depends on factors known only after the year ends, and they mention a Central Withholding Agreement instead.