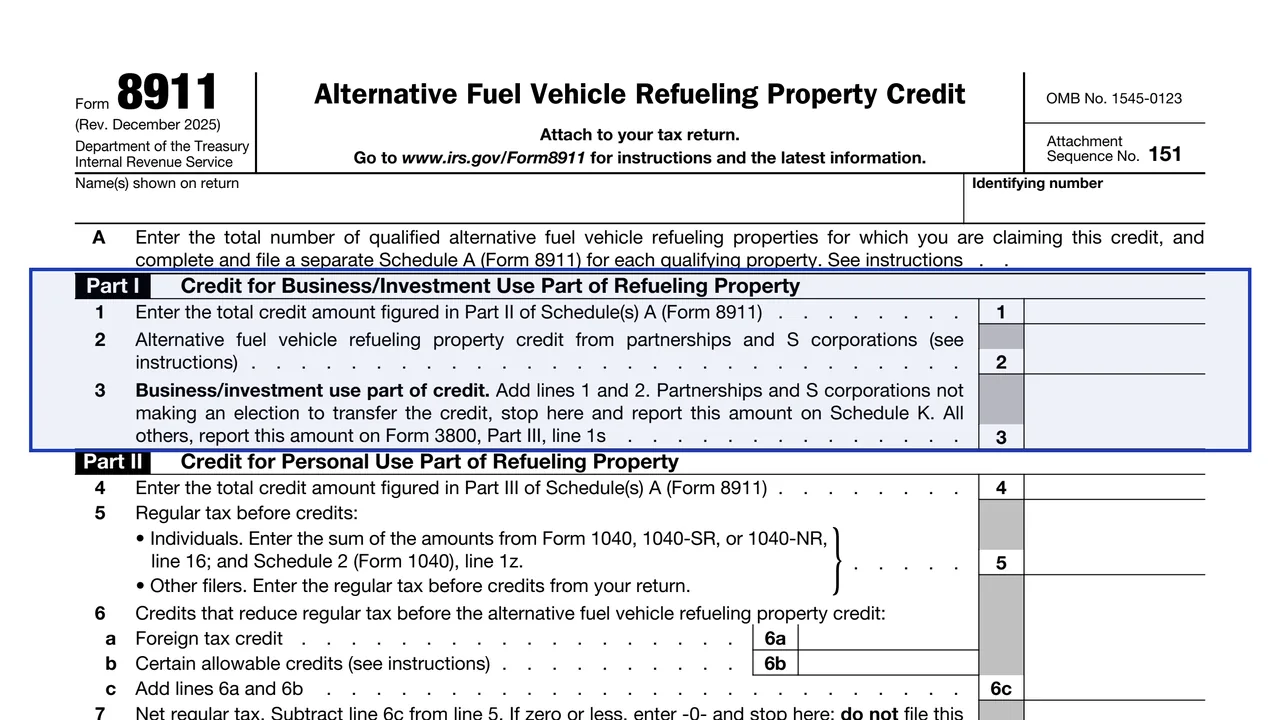
Item A
The total number of qualified alternative fuel vehicle refueling properties claimed, with a separate Schedule A (Form 8911) for each one.
8911
Alternative Fuel Vehicle Refueling Property Credit
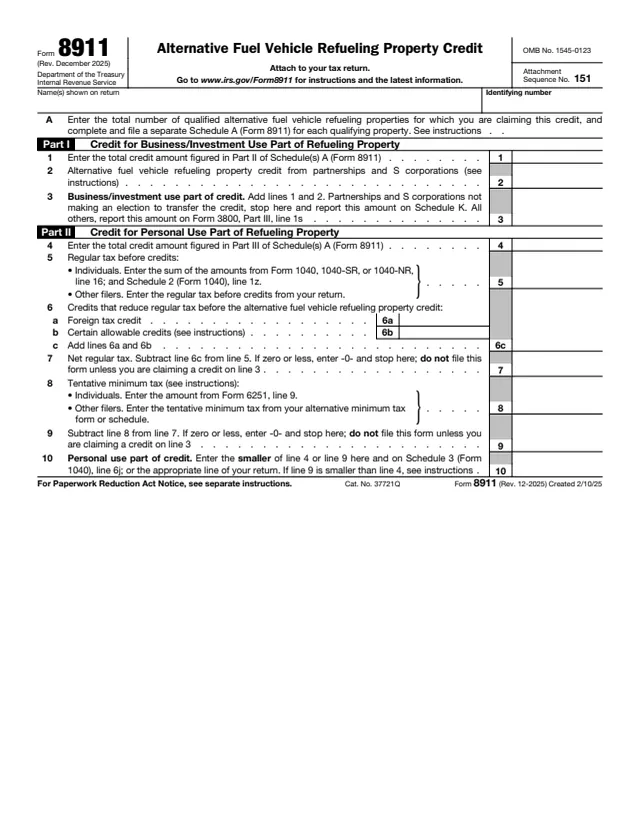
Form 8911 is used with Schedule A (Form 8911) to figure the credit for alternative fuel vehicle refueling property placed in service during the tax year. The instructions describe this property as equipment that stores or dispenses an alternative fuel other than electricity into a vehicle's fuel tank, or that recharges an electric vehicle, at the point where the vehicle is fueled or recharged.
The credit has two parts. The instructions say the part attributable to business/investment use is treated as a general business credit, and any other part is treated as a personal credit. The form says to attach it to the tax return, and a separate Schedule A (Form 8911) is completed for each property.
The instructions say the credit can't be claimed for property placed in service after June 30, 2026. This page carries the December 2025 revision, which the instructions say is for tax years beginning in 2025 or later. You can fill it out free in your browser on this page and download the result without an account.
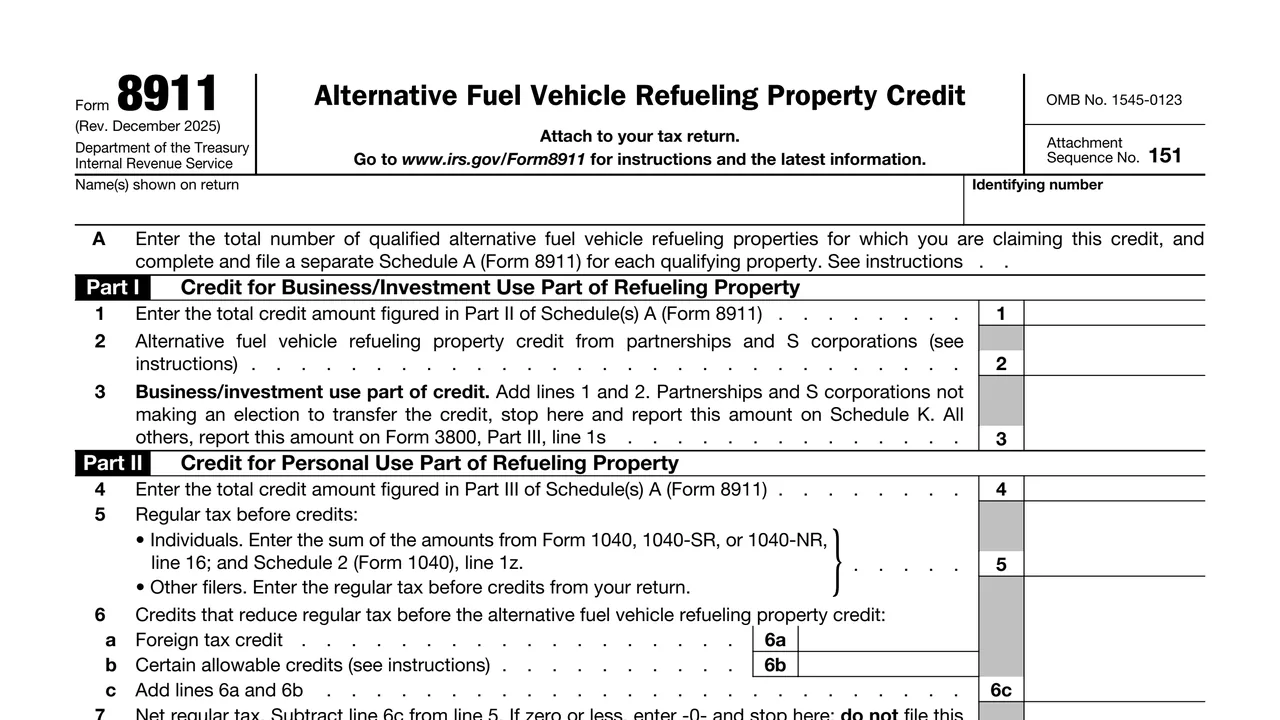
The total number of qualified alternative fuel vehicle refueling properties claimed, with a separate Schedule A (Form 8911) for each one.
Line 1 takes the credit from Part II of the Schedule(s) A, line 2 adds credits from partnerships and S corporations, and line 3 adds the two.
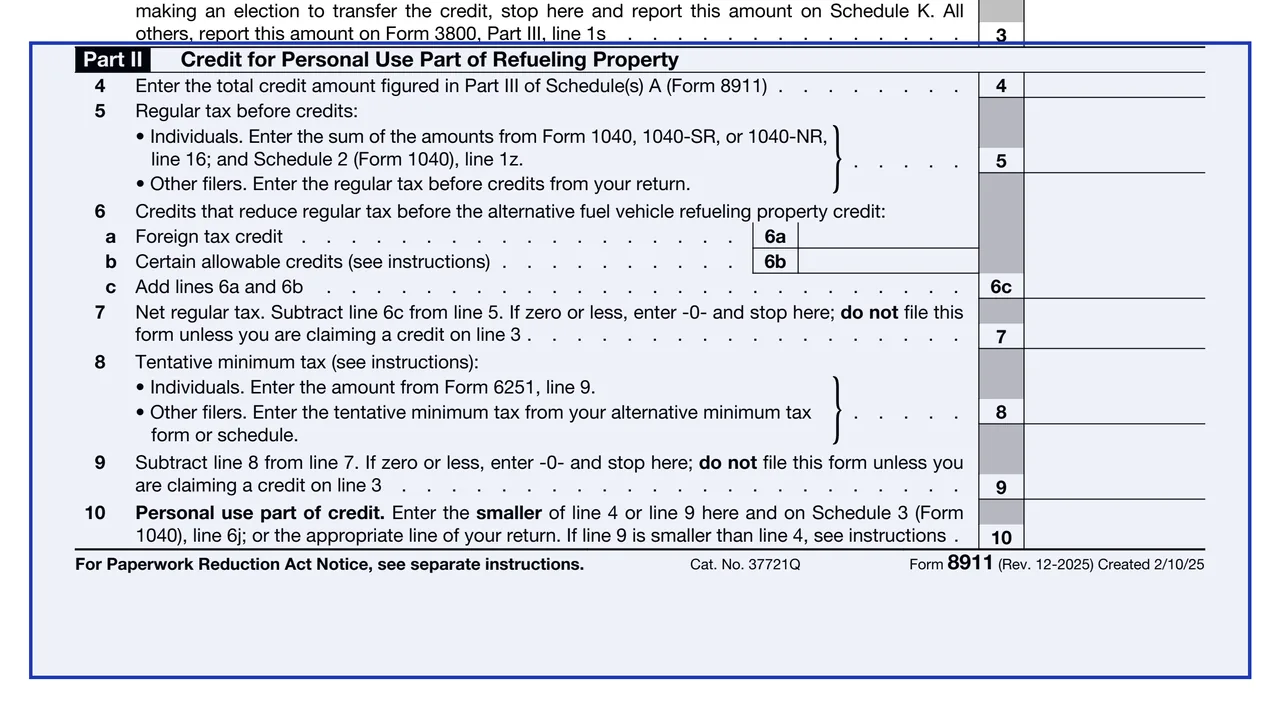
The total credit amount figured in Part III of the Schedule(s) A (Form 8911).
Regular tax before credits, less the foreign tax credit on line 6a and certain allowable credits on line 6b.
Individuals enter the amount from Form 6251, line 9, on line 8. Line 9 subtracts line 8 from line 7.
The smaller of line 4 or line 9, entered here and on Schedule 3 (Form 1040), line 6j, or the appropriate line of the return.
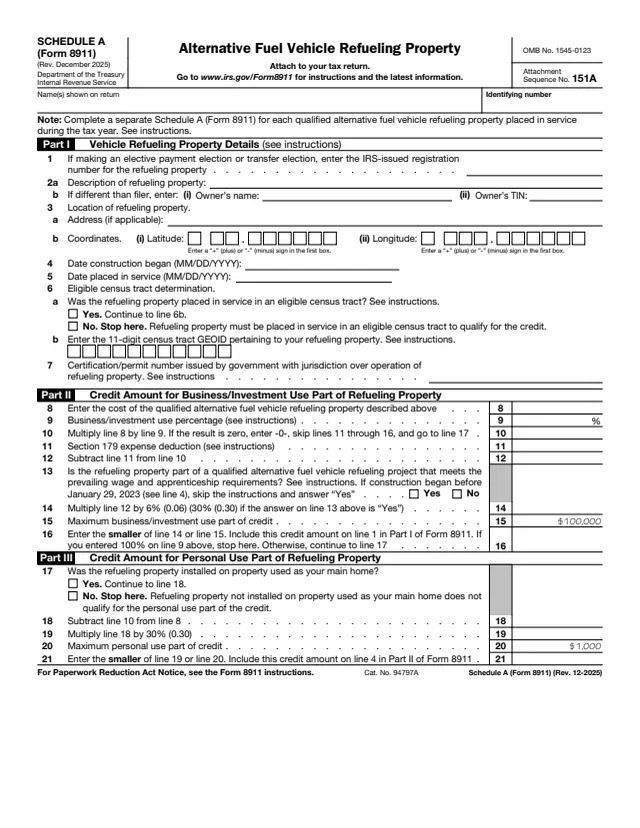
The About page says a separate Schedule A (Form 8911) is completed for each item of property placed in service during the tax year before Form 8911. Schedule A asks for details such as the date placed in service and the census tract.
Enter the total number of properties for which the credit is claimed. The instructions say to enter -0- if the only credit is from line 2.
The instructions say to enter credits from Schedule K-1 (Form 1065), box 15 (code AO), and Schedule K-1 (Form 1120-S), box 13 (code AO).
Add lines 1 and 2. The form says partnerships and S corporations not making an election to transfer the credit stop here and report the amount on Schedule K, and all others report it on Form 3800, Part III, line 1s.
Enter regular tax, the credits on lines 6a and 6b, and the tentative minimum tax. The instructions say the tentative minimum tax is figured even when no AMT is owed. The form says to stop if line 7 or line 9 is zero or less, unless a credit is claimed on line 3.
Enter the smaller of line 4 or line 9. The instructions say an unused personal portion of the credit is lost and can't be carried back or forward to other tax years.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return, along with the Schedule(s) A (Form 8911).
The instructions say to use the December 2025 revision for tax years beginning in 2025 or later, and prior revisions for earlier tax years.
The instructions say the business/investment use credit is 6% (30% if PWA requirements are met) of the property's cost, limited to $100,000 for each single item. The personal use credit is 30% of the cost, limited to $1,000 for each single item.
The instructions say P.L. 119-21 changed the termination date to June 30, 2026, and the credit can't be claimed for property placed in service after that date.
The instructions say a separate Form 7220 is filed for each property for which the increased credit amount for meeting the PWA requirements is claimed.
The instructions say a pre-filing registration is completed for each property or project before filing when an elective payment or transfer election is planned for the Part I credit, at IRS.gov/EPTRegister.
8911 Sch. A
35 fields, 1 page
3800
1,921 fields, 9 pages
7220
653 fields, 5 pages
1040
37 fields, 1 page
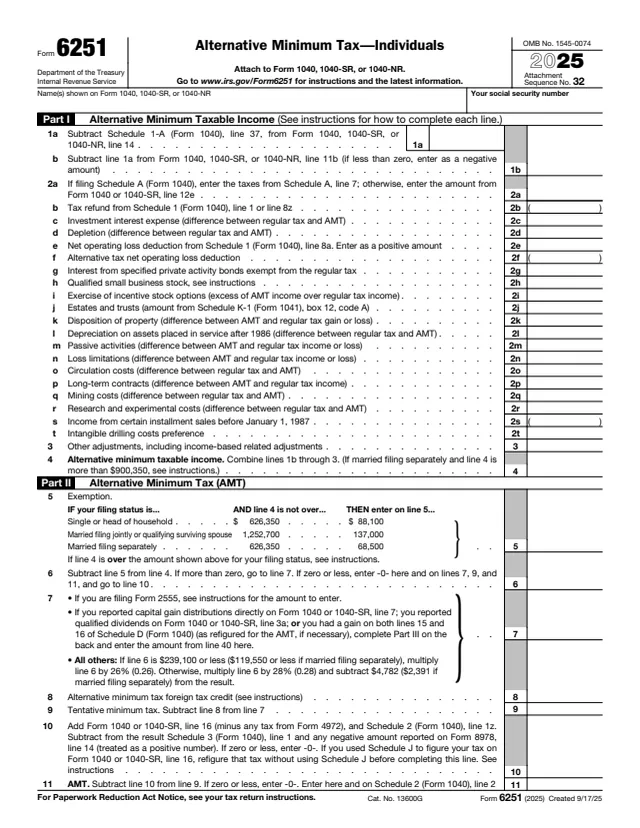
6251
62 fields, 2 pages
4562
277 fields, 3 pages
The form is attached to the tax return of the taxpayer claiming the credit. The instructions name the filers below.
No tool matches that search.
Yes. The form says to complete and file a separate Schedule A (Form 8911) for each qualifying property.
The instructions say the credit can't be claimed for alternative fuel vehicle refueling property placed in service after June 30, 2026.
The instructions say taxpayers whose only source for this credit is a partnership or S corporation aren't required to file it and can report the credit directly on Form 3800, Part III, line 1s.
The instructions say the unused personal portion of the credit is lost and can't be carried back or forward to other tax years.
The instructions say property placed in service after 2022 isn't treated as qualified unless it was placed in service in an eligible census tract. Schedule A, line 6 records the census tract GEOID.
The instructions say that unless the filer elects not to claim the credit, the basis of the property is reduced by the sum of the amounts on lines 16 and 21 of its Schedule A (Form 8911).