Part I, lines 1 to 4
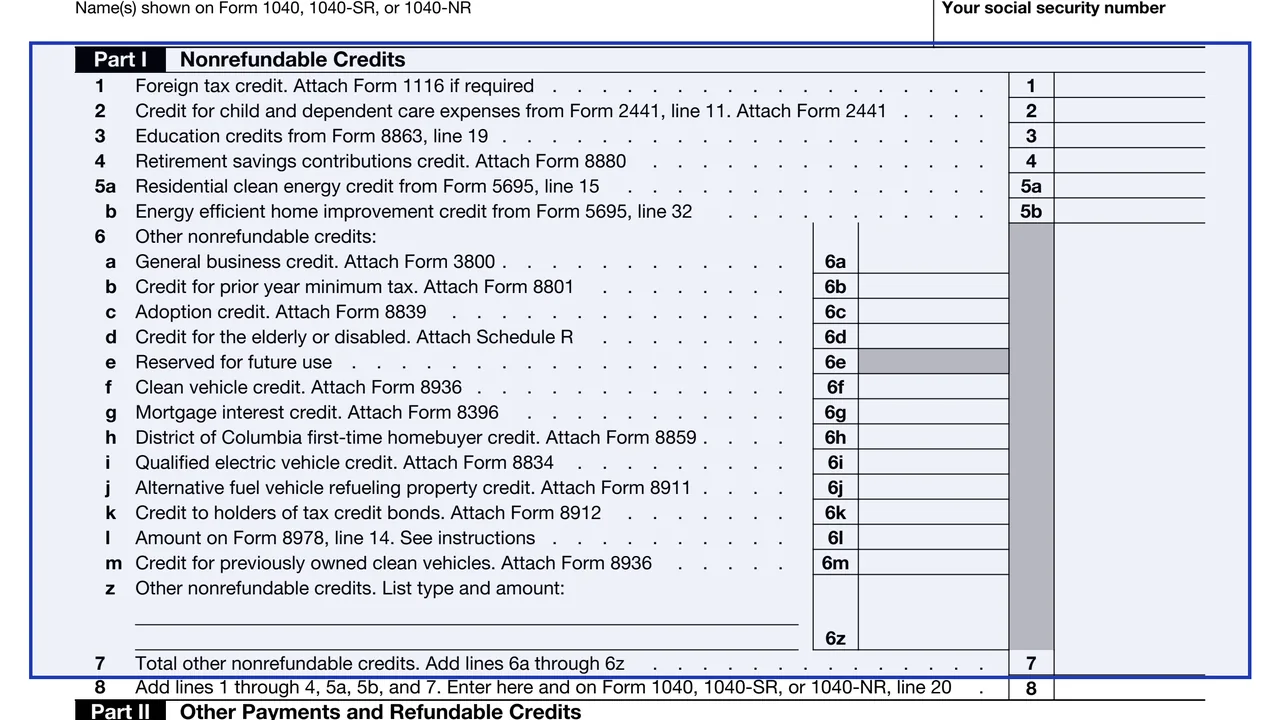
Foreign tax credit, the credit for child and dependent care expenses from Form 2441, education credits from Form 8863, and the retirement savings contributions credit from Form 8880.
1040
Additional Credits and Payments
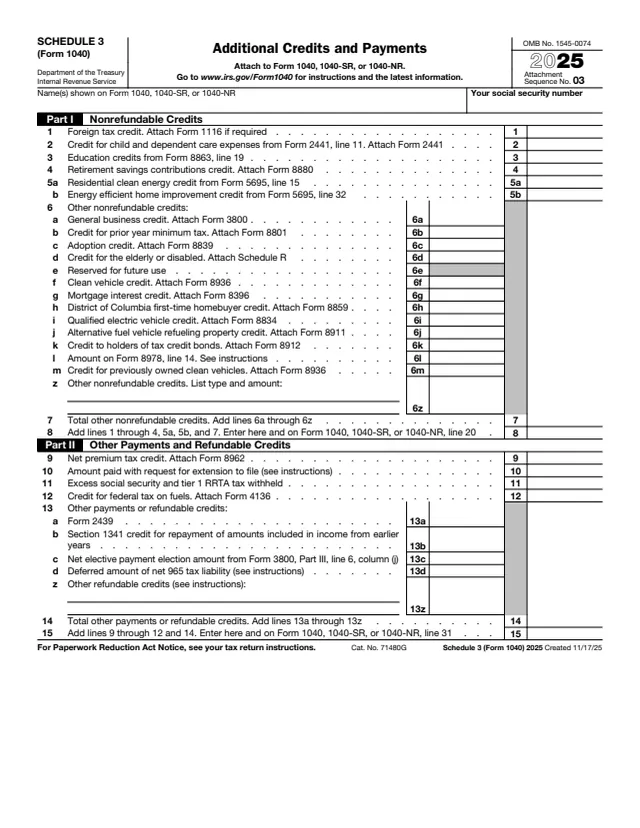
Schedule 3 is one of the numbered schedules that attach to Form 1040, 1040-SR or 1040-NR. The IRS page for Form 1040 says to use it if you can claim a credit that you didn't claim on Form 1040 or 1040-SR, such as the foreign tax credit, education credits or the general business credit, or if you have other payments, such as an amount paid with a request for an extension to file or excess social security tax withheld.
The schedule has two parts. Part I collects nonrefundable credits other than the child tax credit and the credit for other dependents, and its total on line 8 goes to Form 1040, 1040-SR or 1040-NR, line 20. Part II collects other payments and refundable credits, and its total on line 15 goes to line 31 of the same return.
Most lines take a figure from another form, such as Form 2441, Form 8863, Form 5695 or Form 8962, so those forms are usually finished first. You can fill Schedule 3 free in your browser on this page.
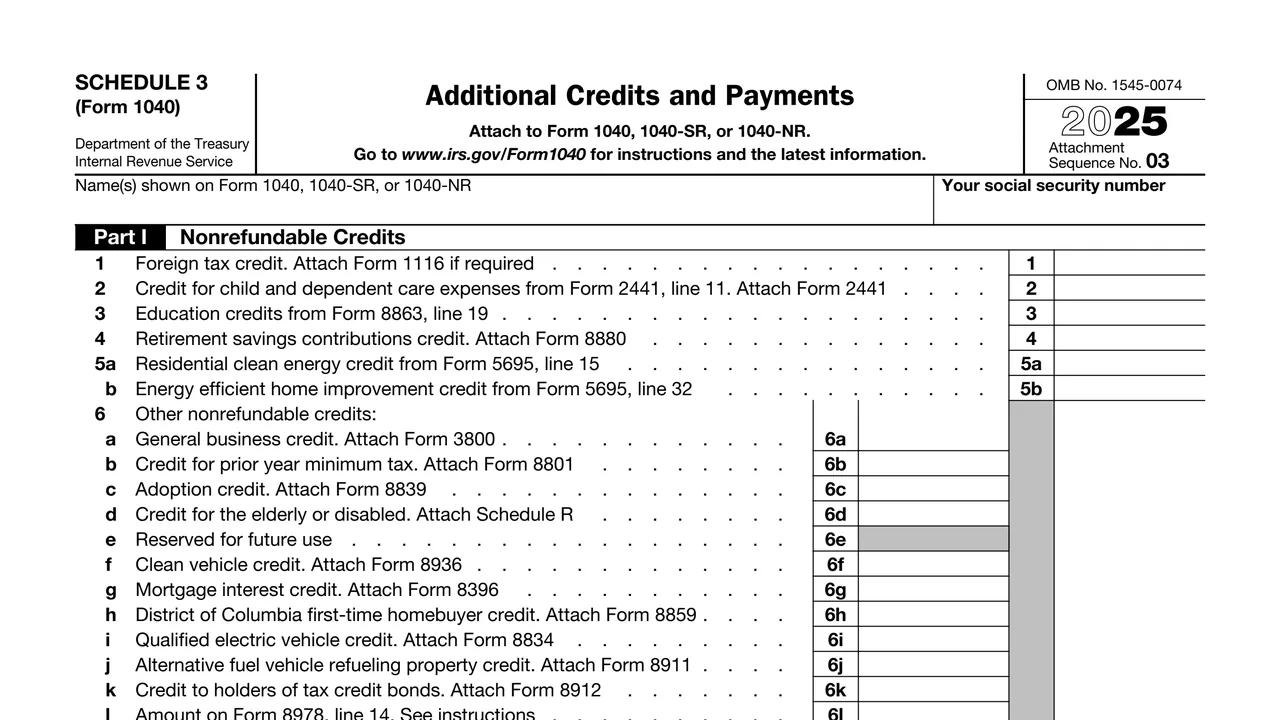
Foreign tax credit, the credit for child and dependent care expenses from Form 2441, education credits from Form 8863, and the retirement savings contributions credit from Form 8880.
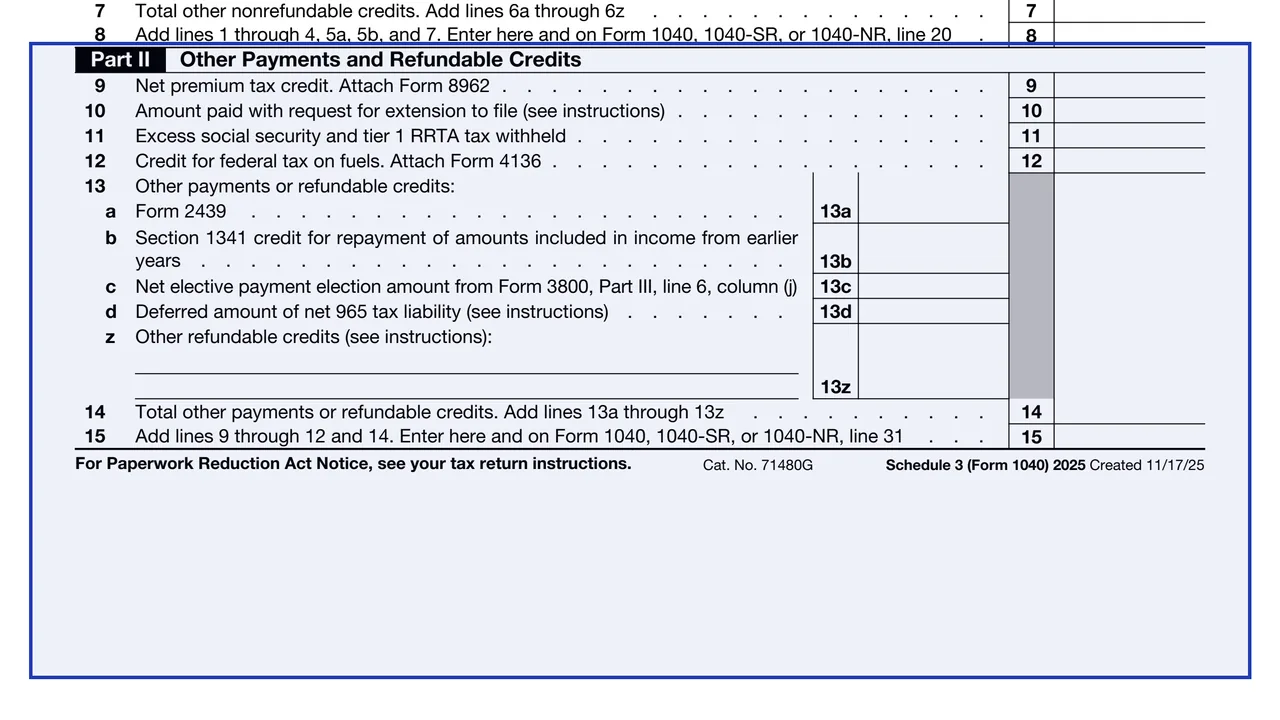
Line 5a is the residential clean energy credit from Form 5695, line 15. Line 5b is the energy efficient home improvement credit from Form 5695, line 32.
Named lines for credits such as the general business credit (Form 3800), the adoption credit (Form 8839), the credit for the elderly or disabled (Schedule R) and the clean vehicle credit (Form 8936). Line 7 adds lines 6a to 6z.
Line 8 adds lines 1 through 4, 5a, 5b and 7. The form says to enter it on Form 1040, 1040-SR or 1040-NR, line 20.
Net premium tax credit (Form 8962), the amount paid with a request for an extension to file, excess social security and tier 1 RRTA tax withheld, and the credit for federal tax on fuels (Form 4136).
Other payments and refundable credits, such as Form 2439, the section 1341 credit and the net elective payment election amount from Form 3800. Line 15 is the Part II total, which goes on Form 1040, 1040-SR or 1040-NR, line 31.
Most lines name the form and line they come from, such as Form 2441, line 11 or Form 8863, line 19. Complete those forms before Schedule 3.
For line 1 without Form 1116, the instructions say to enter the smaller of your total foreign taxes or the total of Form 1040 or 1040-SR, line 16 and Schedule 2, line 1a.
Enter each other nonrefundable credit on its own line and attach the form the line names. The 2025 instructions say line 6e is reserved and line 6z is left blank. Add them on line 7.
Add the Part I credits on line 8 and enter that amount on Form 1040, 1040-SR or 1040-NR, line 20.
For line 10, the instructions say to leave out any fee charged when making the payment and to include amounts paid with Form 2350.
Add lines 9 through 12 and 14 on line 15 and enter it on Form 1040, 1040-SR or 1040-NR, line 31. You can fill this form free on this page.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Schedule 3 is attached to Form 1040, 1040-SR or 1040-NR and is due with it. The 2025 instructions say to file Form 1040 or 1040-SR by April 15, 2026.
Attach it to your return when you mail it, or let tax software transmit it when you e-file.
The IRS form is free.
Many lines tell you to attach the form behind the credit, such as Form 1116, 2441, 8880, 3800, 8839, 8936, 8962 or 4136.
The instructions say Schedule 3 is for nonrefundable credits other than the child tax credit or the credit for other dependents.

1040
199 fields, 2 pages
1040
27 fields, 2 pages
1040
73 fields, 2 pages
8863
77 fields, 2 pages
8962
141 fields, 2 pages
4868
17 fields, 4 pages
No tool matches that search.
Only if you have a credit or payment it lists. The IRS page for Form 1040 says to use it for a credit you didn't claim on Form 1040 or 1040-SR, or for other payments, such as an extension payment or excess social security tax withheld.
Generally yes. The instructions give an exception when all five listed requirements are met, including that all foreign source income was interest and dividends reported on Form 1099-INT, Form 1099-DIV or Schedule K-3, and total foreign taxes were not more than $300 ($600 if married filing jointly).
On line 10. The instructions say to enter the amount paid with Form 4868 or as an extension payment, without any fee you were charged, and to include amounts paid with Form 2350.
The 2025 instructions say it can apply if you had more than one employer and total wages of more than $176,100. The credit is the amount withheld over $10,918.20. If any one employer withheld more than that, the excess isn't claimed on the return: the employer should adjust it, and if it doesn't, Form 843 is used to claim a refund.
Part I holds nonrefundable credits, and its total on line 8 goes to Form 1040, line 20. Part II holds other payments and refundable credits, and its total on line 15 goes to Form 1040, line 31.
No. The instructions say Schedule 3 is for nonrefundable credits other than the child tax credit or the credit for other dependents.