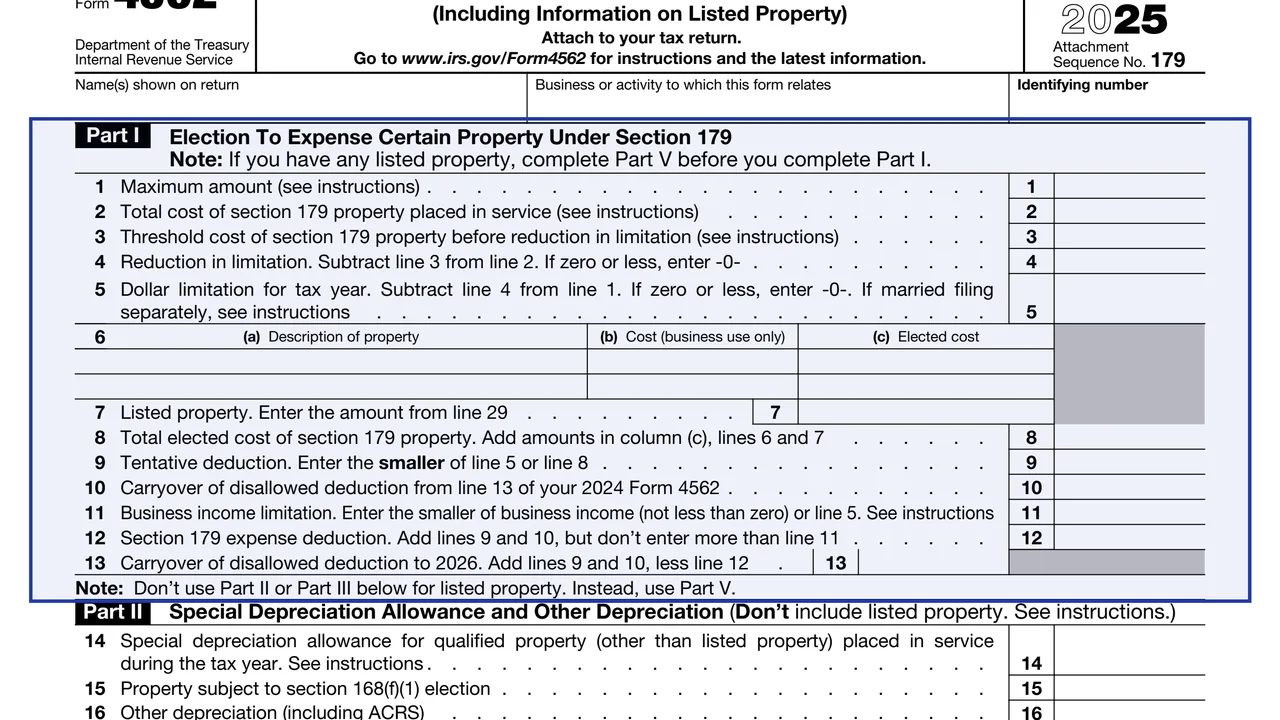
Part I: section 179 election
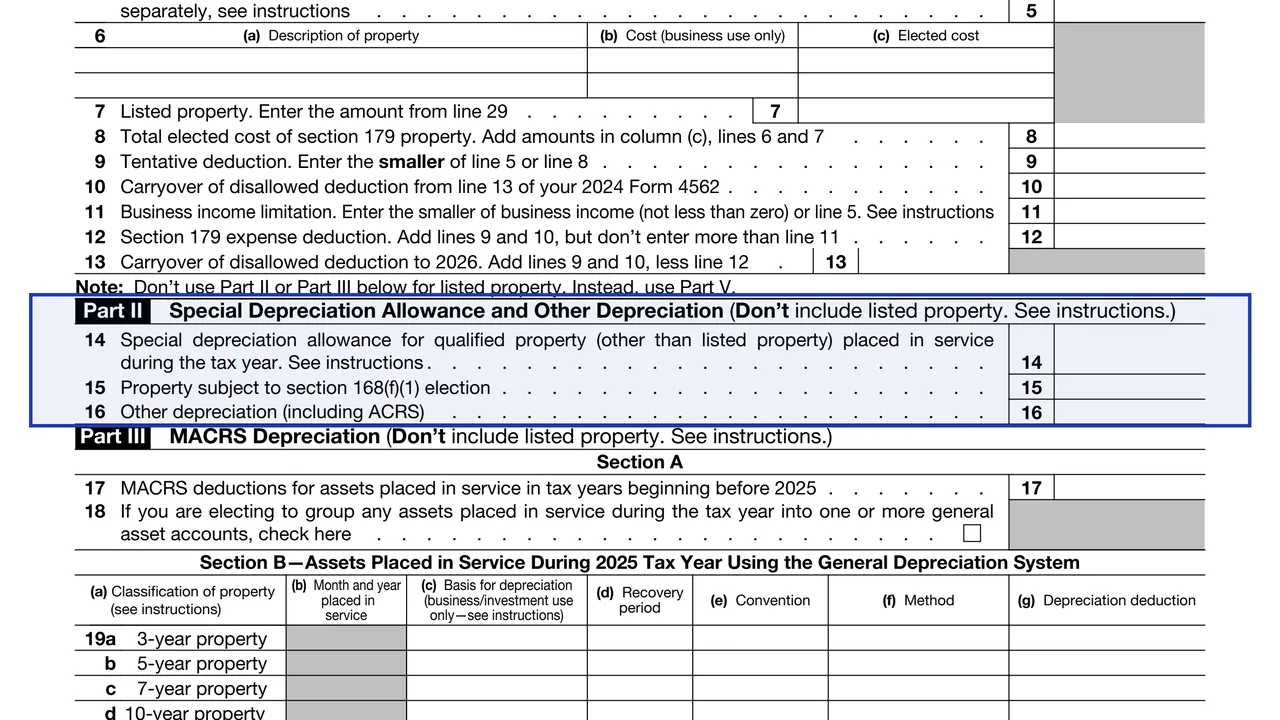
Lines 1 to 13 figure the section 179 expense deduction: the maximum amount, cost of property, threshold, dollar limitation, elected costs, business income limitation and carryovers.
4562
Depreciation and Amortization (Including Information on Listed Property)
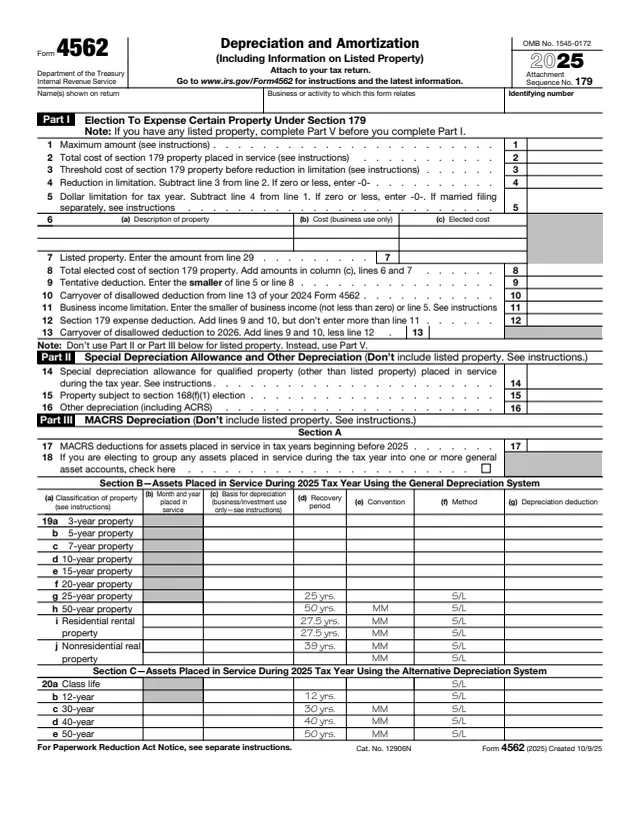
Form 4562, Depreciation and Amortization (Including Information on Listed Property), is attached to a tax return. The IRS page says it is used to claim a deduction for depreciation and amortization, to make the election under section 179 to expense certain property, and to provide information on the business or investment use of automobiles and other listed property.
It is filed by individuals, partnerships, S corporations, corporations and other filers that claim these deductions. The 2025 form has six parts: the section 179 election, the special depreciation allowance and other depreciation, MACRS depreciation, a summary, listed property, and amortization. The instructions say a separate Form 4562 is filed for each business or activity on the return that needs one.
The instructions note new lines for 2025: lines 19h and 20e for 50-year property, lines 23a and 23b for capitalized costs, and line 24c for aircraft. You can fill out Form 4562 free in your browser on this page and download it without an account.
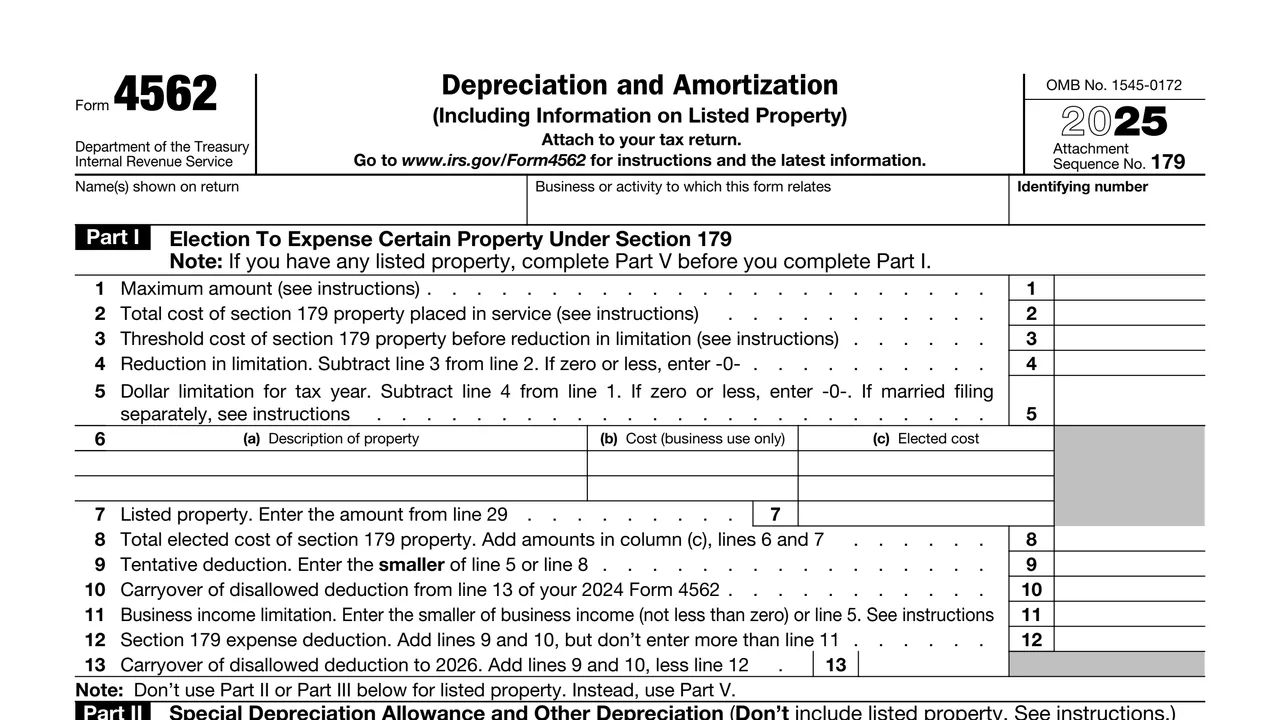
Lines 1 to 13 figure the section 179 expense deduction: the maximum amount, cost of property, threshold, dollar limitation, elected costs, business income limitation and carryovers.
Line 14 for the special depreciation allowance, line 15 for property under a section 168(f)(1) election and line 16 for other depreciation, including ACRS. Listed property is excluded.
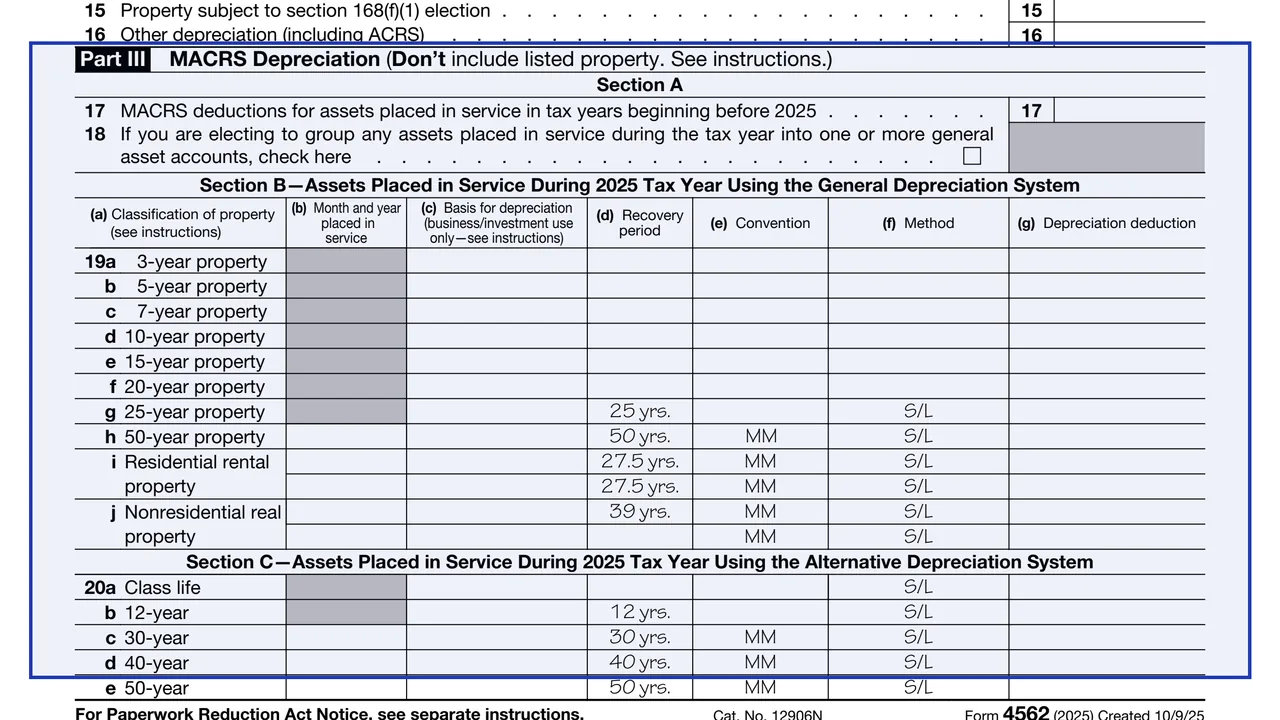
Line 17 for assets placed in service before 2025, line 18 for general asset accounts, and lines 19a to 19j (GDS) and 20a to 20e (ADS) for assets placed in service in 2025.
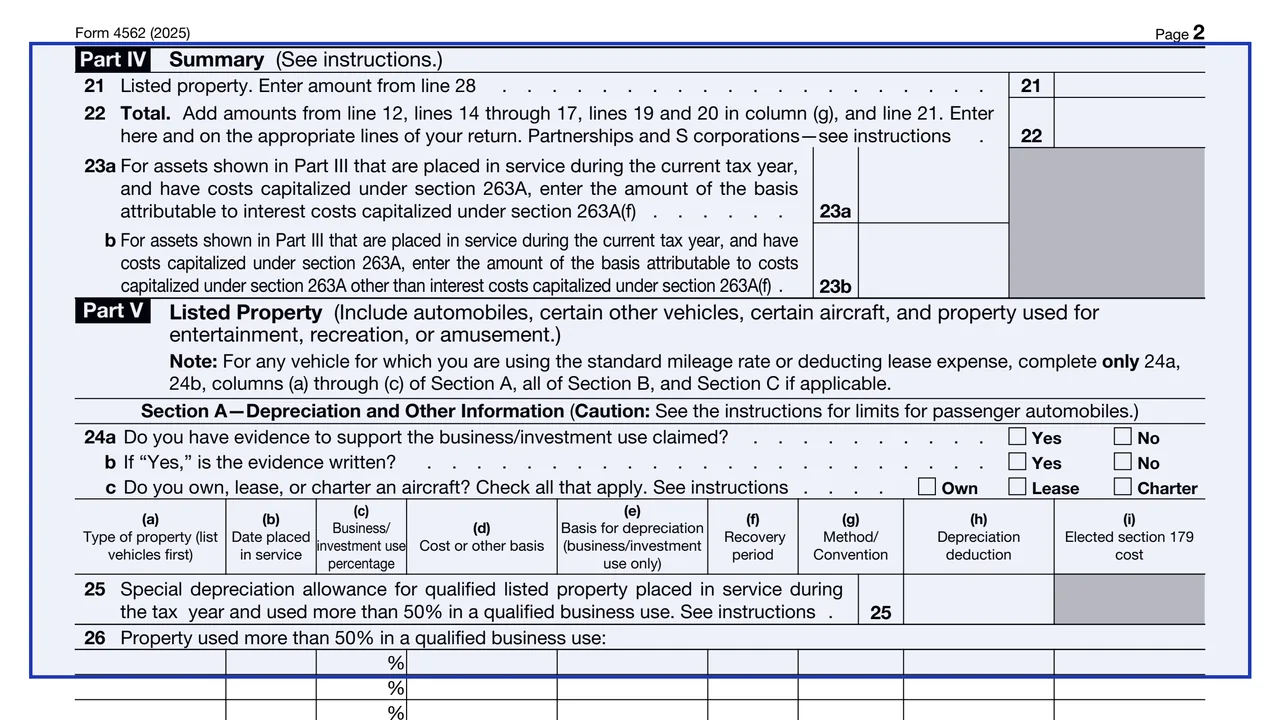
Line 21 for listed property, line 22 for the total, and lines 23a and 23b for basis attributable to costs capitalized under section 263A.
Section A for depreciation of vehicles and other listed property, Section B for vehicle mileage and use, and Section C with questions for employers who provide vehicles to employees.
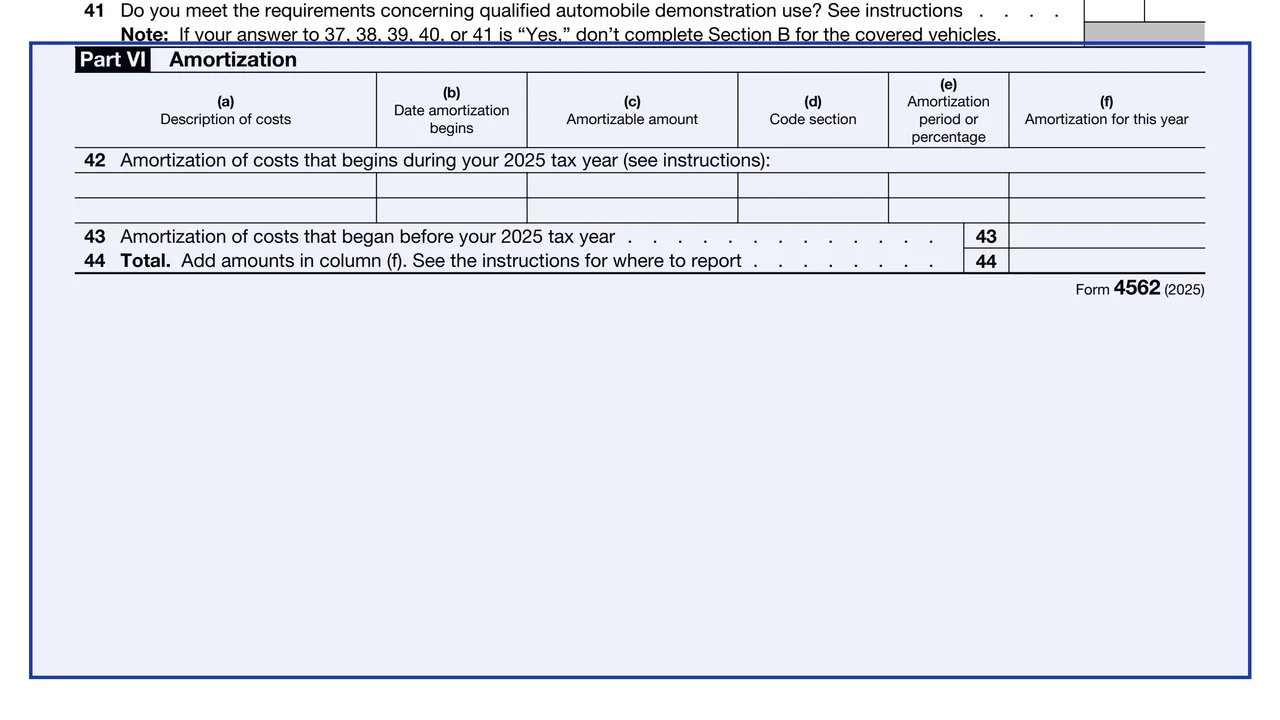
Line 42 for costs whose amortization begins in 2025, line 43 for amortization that began earlier, and line 44 for the total.
Enter the names on the return, the business or activity the form relates to and the identifying number. The form says to complete Part V before Part I if there is any listed property.
The instructions say the 2025 maximum section 179 deduction is $2,500,000, reduced by the amount the cost of section 179 property placed in service exceeds $4,000,000. Line 6 lists property other than listed property, line 10 carries over line 13 of the 2024 form, and line 11 applies the business income limitation.
Line 14 is the special depreciation allowance for qualified property placed in service during the year. The instructions describe a 100% allowance for certain qualified property acquired after January 19, 2025, with an election to take 40% instead (60% for long production period property and certain aircraft).
Line 17 holds MACRS deductions for assets placed in service in earlier years. For 2025 assets, each row of lines 19 and 20 takes the month and year placed in service, basis, recovery period, convention, method and the deduction in column (g).
Answer lines 24a to 24c, then lines 25 to 29 for each item of listed property. Section B covers vehicles used by a sole proprietor, partner, more than 5% owner or related person. Employers answer Section C, lines 37 to 41, to see if Section B can be skipped for employee vehicles.
Line 22 totals the depreciation and goes on the appropriate lines of the return. The instructions say partnerships and S corporations leave the section 179 deduction out of line 22 and pass it through on Schedules K-1. Line 44 totals amortization.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. It is not filed on its own.
The instructions say to file a separate Form 4562 for each business or activity on the return that needs one, attaching extra sheets for more space, but to complete only one Part I in its entirety for the section 179 deduction.
The instructions say the election is made on Form 4562 filed with the original return for the year the property was placed in service, or with an amended return filed within the time prescribed by law.
Except for Part V, the instructions say the IRS does not require detailed information with the return on assets placed in service in earlier years, but the basis, method and other figures are part of permanent records.
The instructions say not to use Form 4562 for the energy efficient commercial buildings deduction under section 179D. Form 7205 is used instead.
The IRS page lists a correction to the 2021, 2022 and 2023 Instructions for Form 4562, instructions for Part I, line 5, dated 4-DEC-2024.
2106
87 fields, 2 pages
4797
182 fields, 2 pages
1040
105 fields, 2 pages
6251
62 fields, 2 pages
7205
113 fields, 1 page
4626
813 fields, 8 pages
The instructions say Form 4562 is completed and filed by anyone claiming any of the items below, except as otherwise noted. It is attached to that filer's own tax return.
No tool matches that search.
The IRS page says to claim depreciation and amortization, to make the section 179 election to expense certain property, and to provide information on the business or investment use of automobiles and other listed property.
It is filed for a year in which one of the items in the Who Must File list applies, such as property placed in service that year, a section 179 deduction, or depreciation on a vehicle or other listed property.
The instructions say the maximum section 179 expense deduction is $2,500,000 for tax years beginning in 2025, reduced by the amount the cost of section 179 property placed in service exceeds $4,000,000. The SUV limit is $31,300.
The instructions say it generally includes passenger automobiles weighing 6,000 pounds or less, other transportation property that lends itself to personal use, and property used for entertainment or recreational purposes, with exceptions.
The instructions say an employee deducting job-related vehicle expenses uses Form 2106 for this purpose.
The instructions say land cannot be depreciated.
The instructions say one for each business or activity on the return that needs one, with only one Part I completed in full for the section 179 deduction.