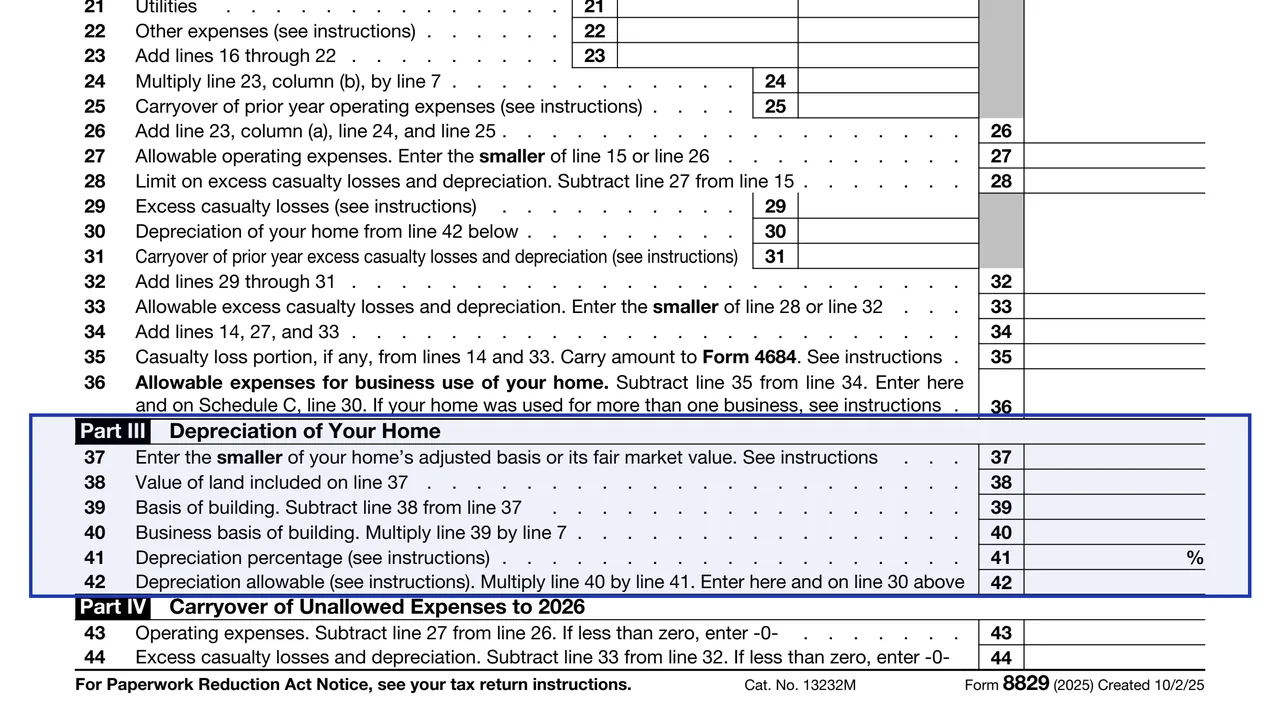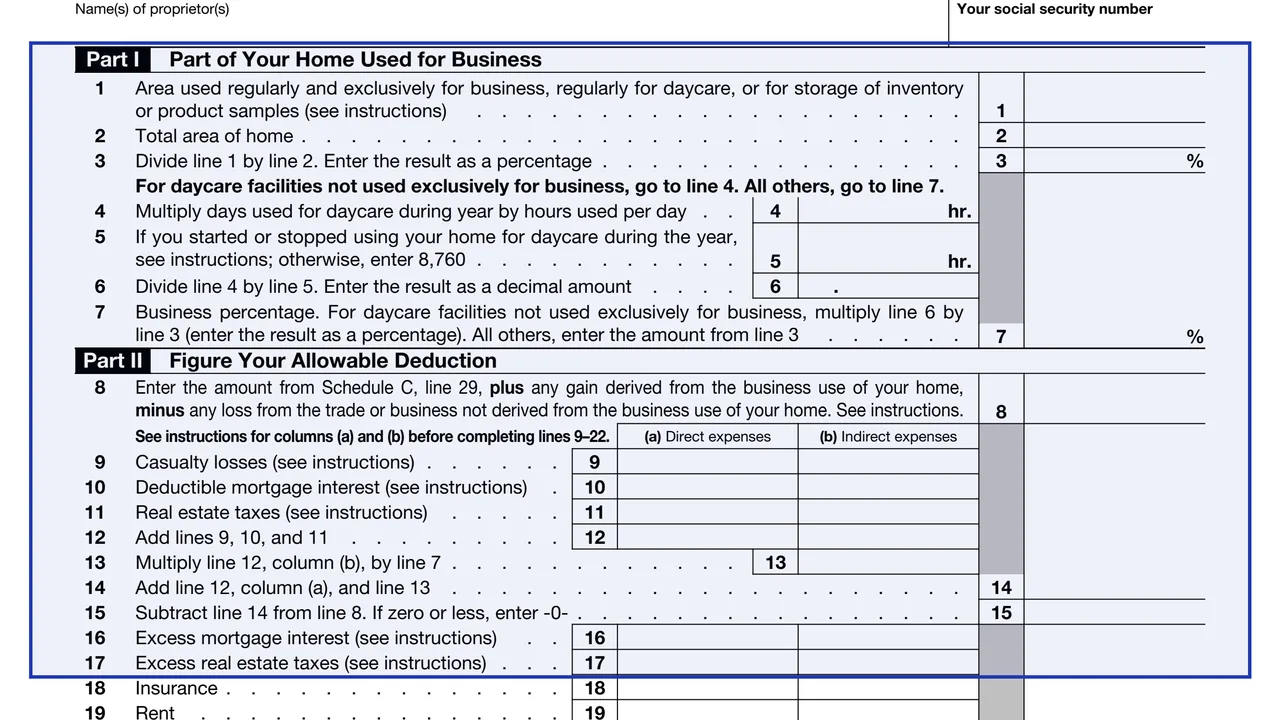
Part I: lines 1 to 7
The business area and total area of the home, the business percentage, and for daycare space not used exclusively for business, the hours used for daycare.
8829
Expenses for Business Use of Your Home
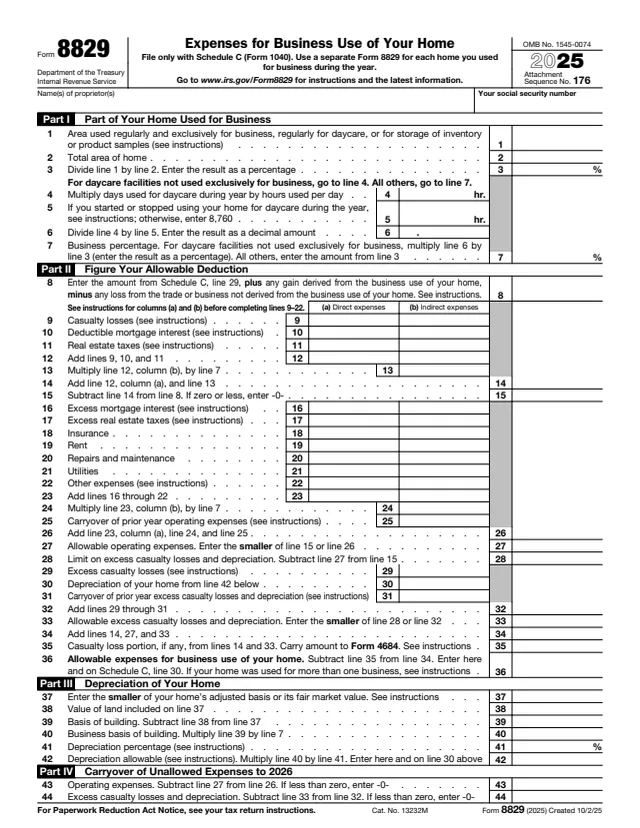
Form 8829 figures the allowable expenses for business use of a home on Schedule C (Form 1040) and any carryover to 2026 of amounts not deductible in 2025. The form says to file it only with Schedule C (Form 1040) and to use a separate Form 8829 for each home used for business during the year.
The form has four parts: the part of the home used for business, the allowable deduction, depreciation of the home, and the carryover of unallowed expenses to 2026. The result on line 36 is entered on Schedule C, line 30.
The instructions say specific requirements apply to deducting expenses for business use of a home, and that even when they are met the deductible expenses may be limited. They point to Pub. 587 for details. This page covers the 2025 form. You can fill out Form 8829 free in your browser on this page and download it without an account.
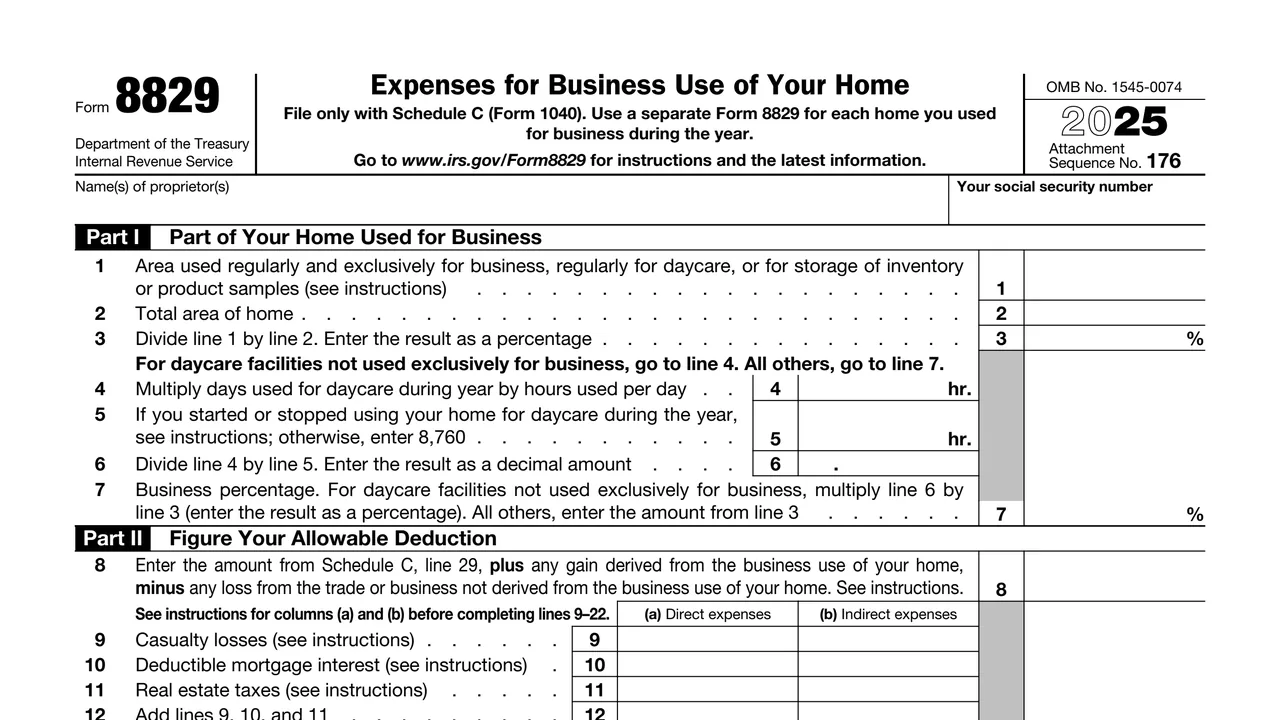
The business area and total area of the home, the business percentage, and for daycare space not used exclusively for business, the hours used for daycare.
The income limit on line 8, then casualty losses, deductible mortgage interest and real estate taxes in column (a) direct and column (b) indirect expenses.
Excess mortgage interest, excess real estate taxes, insurance, rent, repairs and maintenance, utilities, other expenses and the prior year operating expense carryover.
Excess casualty losses, depreciation from line 42, prior year carryover, the casualty loss portion for Form 4684, and the allowable expenses on line 36.
The smaller of the home's adjusted basis or fair market value, land value, basis of the building, business basis, depreciation percentage and depreciation allowable.
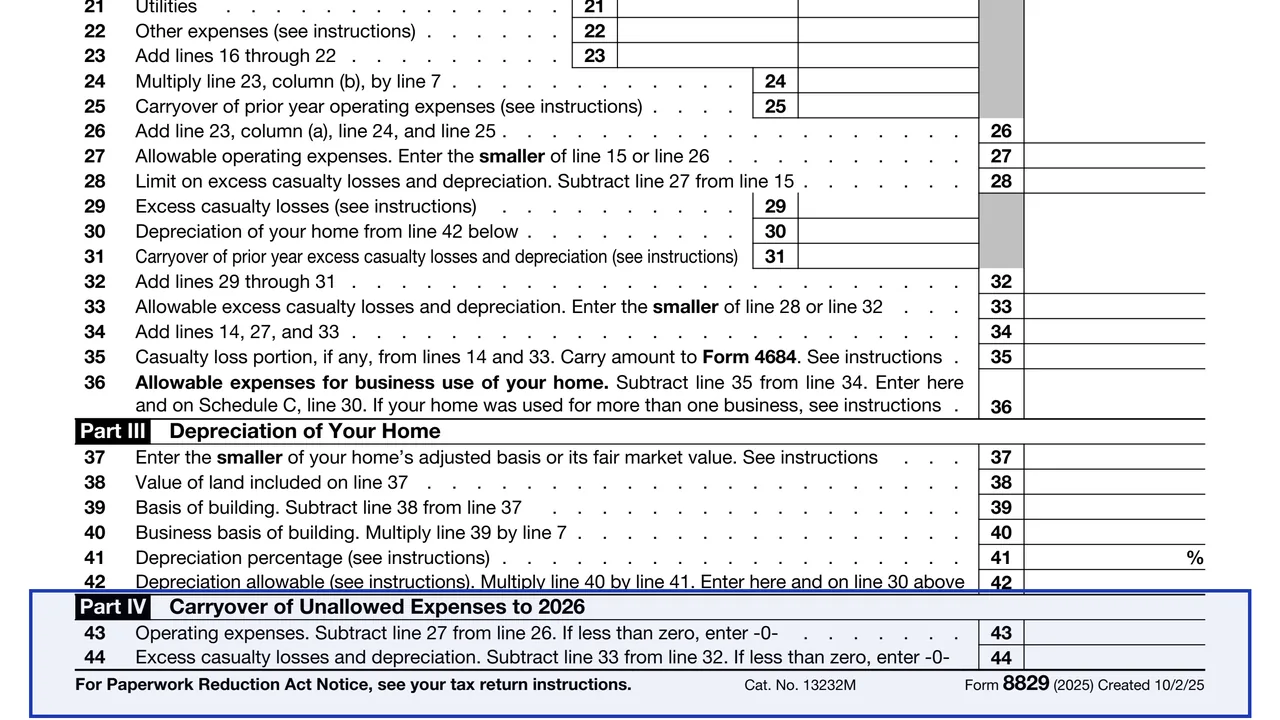
Operating expenses on line 43 and excess casualty losses and depreciation on line 44 that were not allowed this year.
Enter the area used for business and the total area of the home. The instructions allow square feet or any other reasonable method that accurately figures the business percentage. Divide line 1 by line 2.
For daycare space not used exclusively for business, enter hours used on line 4 and 8,760 on line 5, or 24 times the days available if daycare started or stopped during the year. All others enter line 3 on line 7.
Enter Schedule C, line 29, plus any gain from business use of the home, minus losses not derived from it. The instructions explain how to allocate income when some of it comes from another business location.
Direct expenses benefit only the business part of the home and go in column (a) at 100%. Indirect expenses keep up the whole home and generally go in column (b) at 100%. Supplies and advertising belong elsewhere on Schedule C.
The instructions say a taxpayer claiming the standard deduction leaves lines 10 and 11 blank and enters the business portion of mortgage interest and real estate taxes on lines 16 and 17. Itemizers follow the steps and worksheet in the instructions.
Enter the smaller of basis or fair market value, subtract land, multiply by line 7 and apply the line 41 percentage. The instructions list 2.564% for a home first used for business after May 12, 1993, and before 2025, with noted exceptions.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Form 8829 is filed with Schedule C (Form 1040) as part of the income tax return. The form says to use a separate Form 8829 for each home used for business during the year.
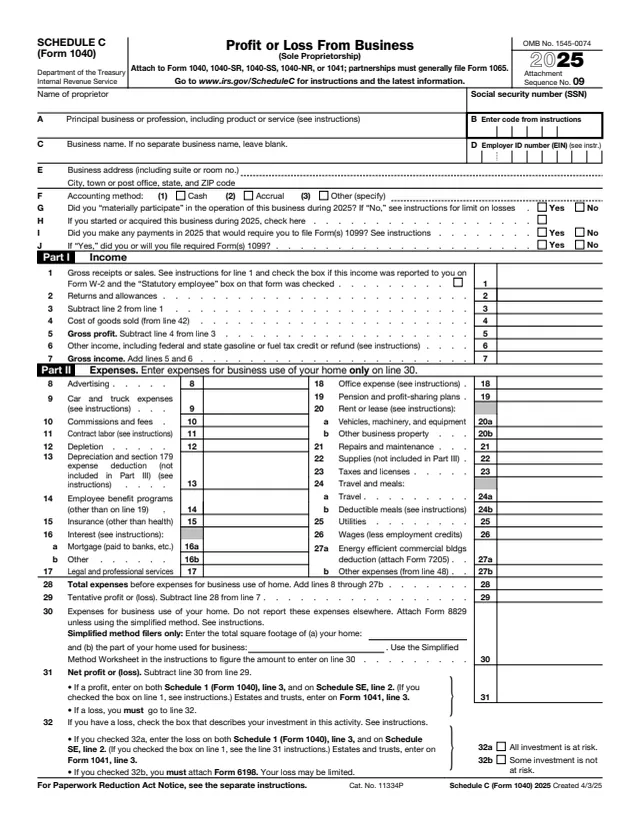
Line 36 is entered on Schedule C, line 30. If the home was used in more than one business, the instructions say to allocate it using any method that is reasonable under the circumstances.
The instructions say to enter line 35 on Form 4684, line 27, and write "See Form 8829" above line 27.
The instructions say to complete and attach Form 4562 only if the home was first used for business in 2025 or additions and improvements were placed in service in 2025.
Lines 43 and 44 carry unallowed amounts to 2026. The instructions say the carryover is subject to the deduction limit for that year, whether or not the same home is used.
If the simplified method was used for 2024 but not for 2025, the instructions say unallowed expenses from a prior year Form 8829 may carry over on lines 25 and 31.
1040
105 fields, 2 pages
4562
277 fields, 3 pages
4684
162 fields, 4 pages
1040
33 fields, 1 page
4797
182 fields, 2 pages

1040
199 fields, 2 pages
The form is an attachment to Schedule C (Form 1040), so it is completed by the person who files that schedule and goes to the IRS with the return. The instructions also list cases where Form 8829 is not used.
No tool matches that search.
The form says to file it only with Schedule C (Form 1040), using a separate Form 8829 for each home used for business during the year.
No. The instructions list expenses for business use of a home as an employee among the cases where Form 8829 is not used, and say these expenses can't be deducted on a personal return.
The instructions say not to use it for actual expenses claimed as a partner or on Schedule F (Form 1040), and point to the worksheet in Pub. 587 instead.
The instructions say direct expenses benefit only the business part of the home, such as painting or repairs to the rooms used for business. Indirect expenses are for keeping up and running the entire home.
Part IV carries unallowed operating expenses and excess casualty losses and depreciation to 2026, where they are subject to that year's limit.
The line 41 table in the instructions gives a percentage by month, from 2.461% for January to 0.107% for December.