Line 1: students and schools
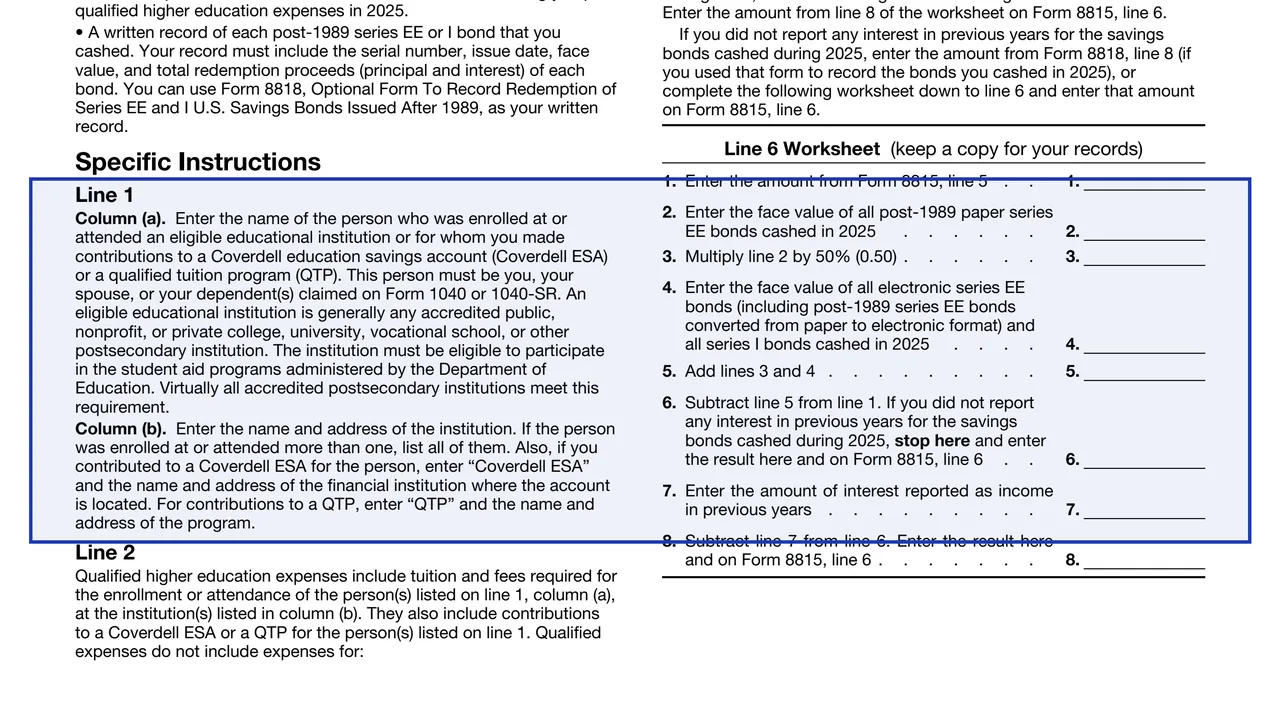
Column (a) names each person enrolled at or attending an eligible educational institution. Column (b) gives the institution's name and address.
8815
Exclusion of Interest From Series EE and I U.S. Savings Bonds Issued After 1989 (For Filers With Qualified Higher Education Expenses)
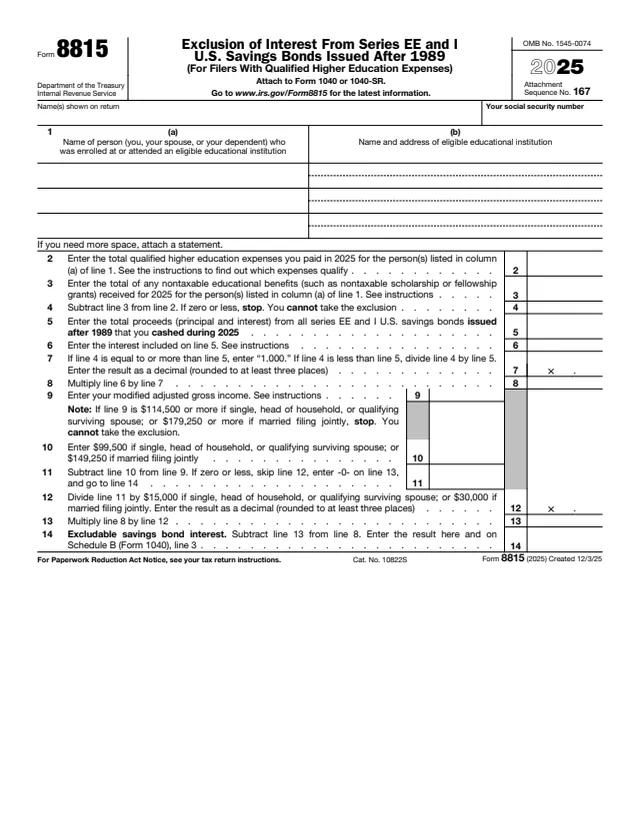
Form 8815 is the IRS form used to figure how much interest from Series EE and I U.S. savings bonds issued after 1989 may be excluded from income when the bonds were cashed and qualified higher education expenses were paid. Its subtitle reads For Filers With Qualified Higher Education Expenses, and it is attached to Form 1040 or 1040-SR.
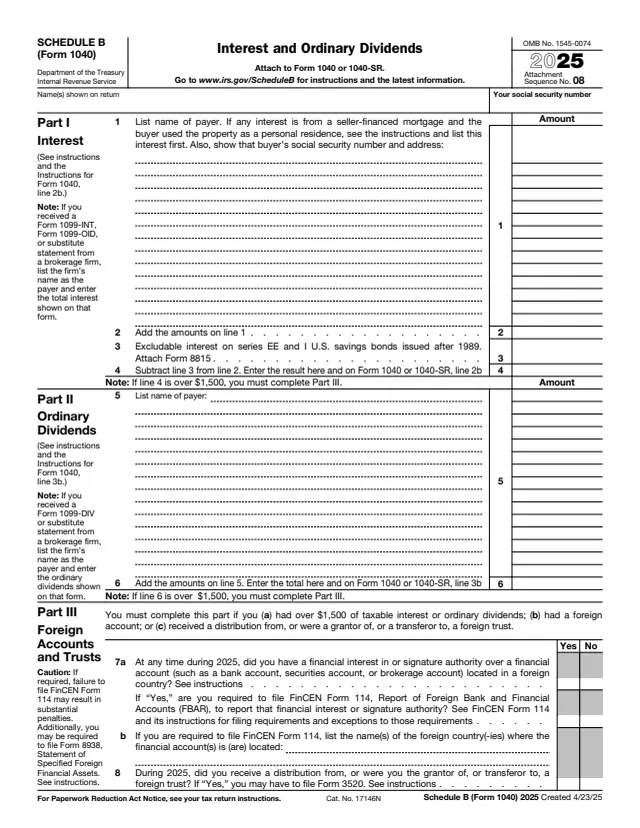
The form compares the education expenses paid, less nontaxable benefits such as scholarships, with the total bond proceeds, then applies a reduction based on modified adjusted gross income (AGI). The result on line 14 is the excludable savings bond interest, which also goes on Schedule B (Form 1040), line 3. The instructions are printed on pages 3 and 4 of the same PDF, including worksheets for lines 6 and 9.
This page covers the 2025 form, for bonds cashed during 2025. You can fill it out free in your browser on this page and download the result without an account.
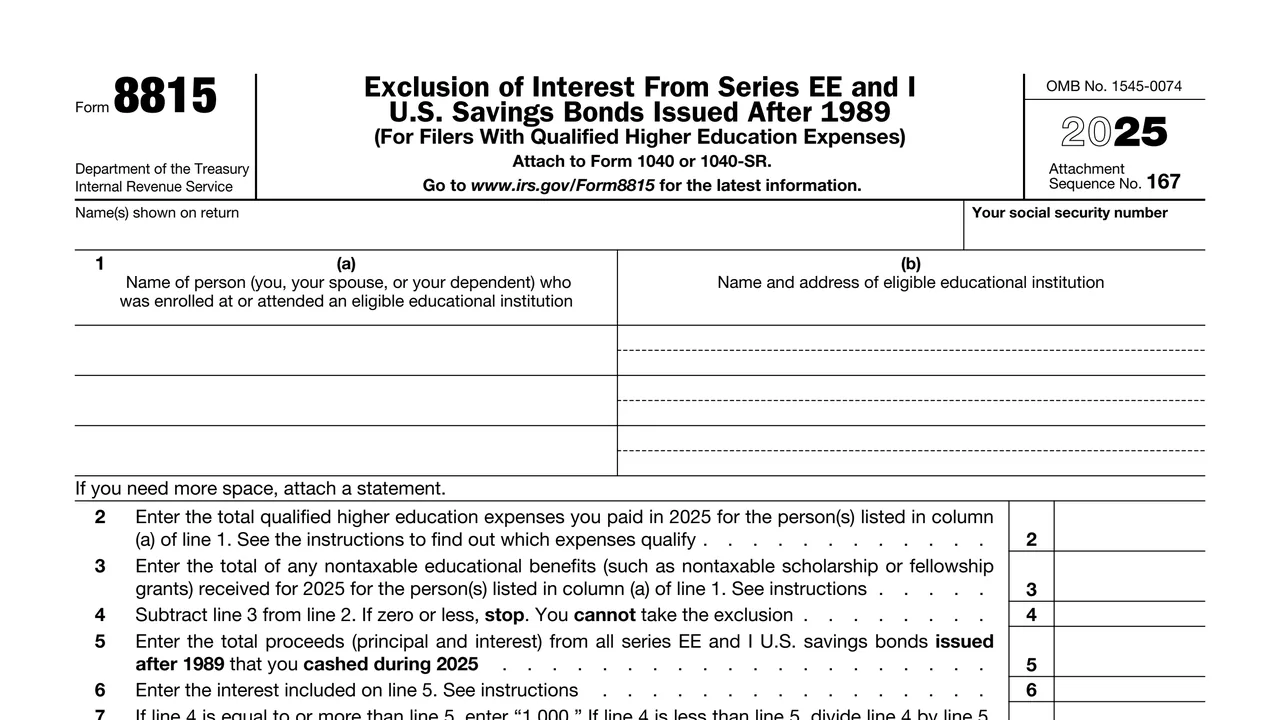
Column (a) names each person enrolled at or attending an eligible educational institution. Column (b) gives the institution's name and address.
Qualified higher education expenses paid in 2025, minus nontaxable educational benefits. If line 4 is zero or less, the form says to stop.
Total proceeds from the bonds cashed in 2025, the interest included in them, a ratio of expenses to proceeds, and the interest that ratio covers.
Modified AGI, the starting amount on line 10, and a reduction figured by dividing the excess by $15,000 or $30,000 depending on filing status.
Line 8 minus line 13. The form says to enter the result here and on Schedule B (Form 1040), line 3.
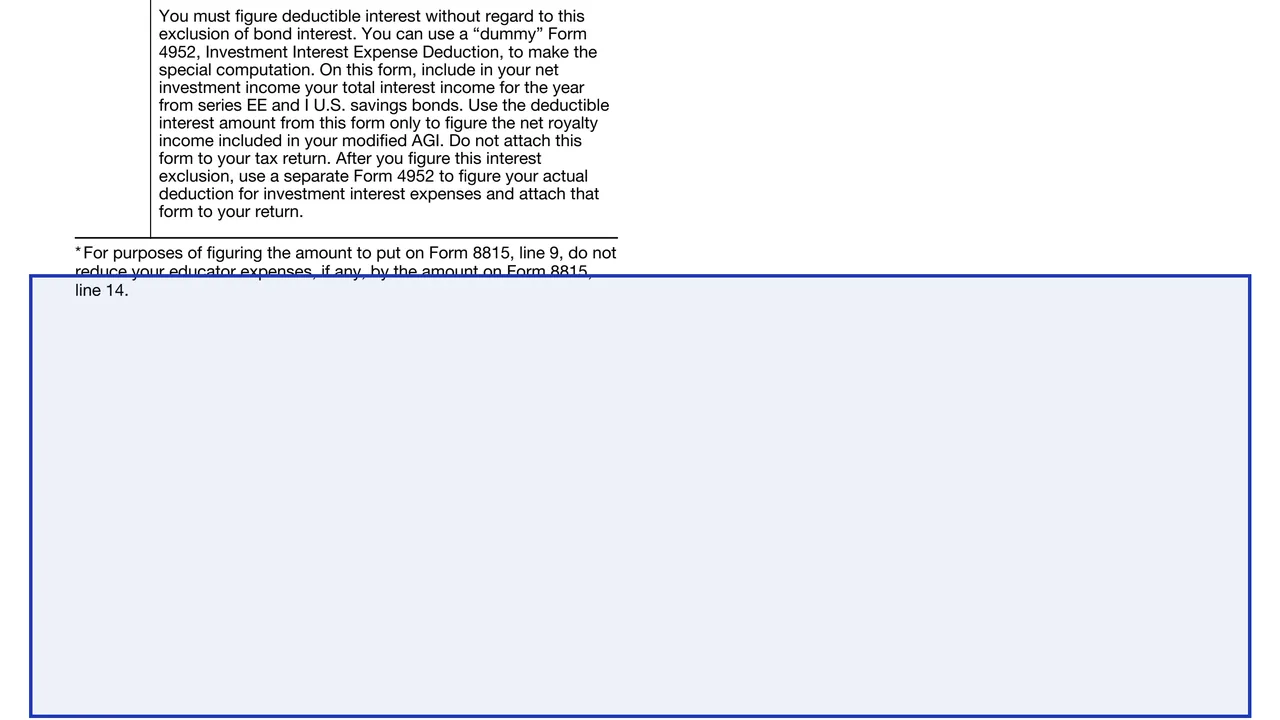
Pages 3 and 4 hold the general and line instructions, the Line 6 Worksheet for interest and the Line 9 Worksheet for modified AGI.
In column (a), enter each person, who the instructions say is you, your spouse, or a dependent claimed on Form 1040 or 1040-SR. In column (b), list each institution, or Coverdell ESA or QTP and the account's institution or program.
Enter tuition and fees required for enrollment or attendance, plus Coverdell ESA or QTP contributions. The instructions say not to include room and board, or expenses used for an education credit on Form 8863.
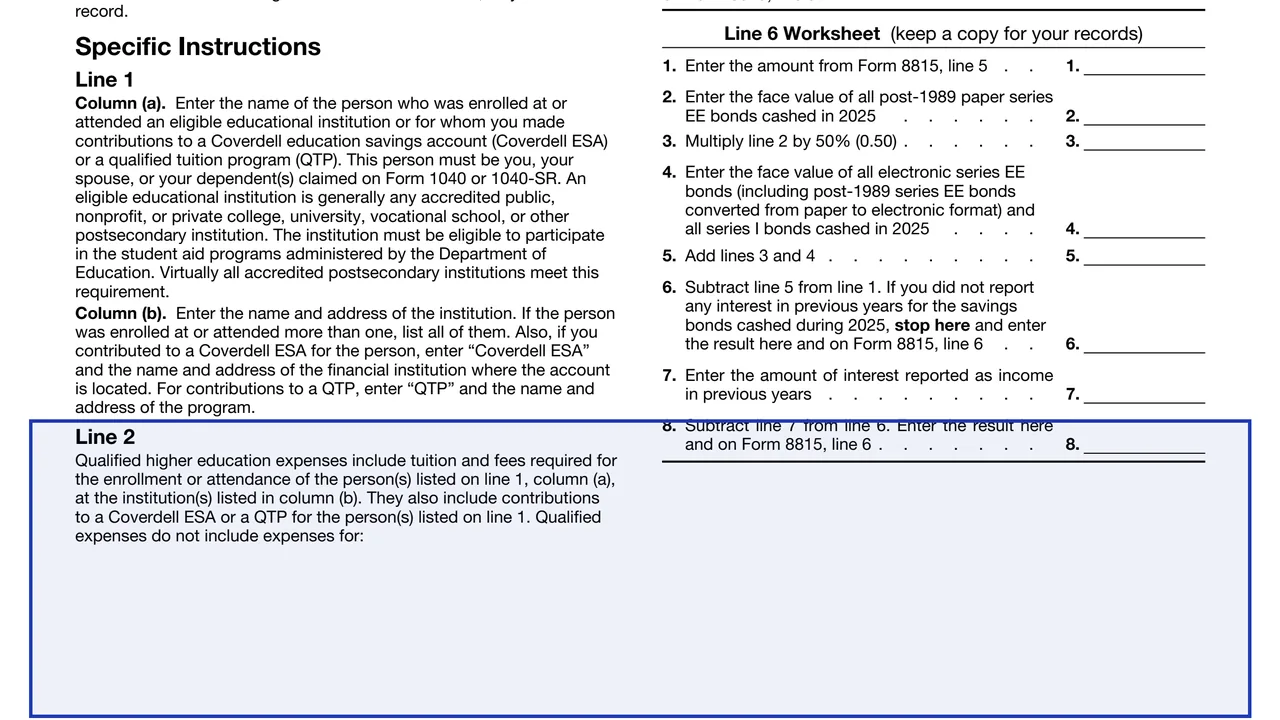
Enter expenses from line 2 covered by nontaxable benefits such as excludable scholarships, veterans' educational assistance or certain employer-provided assistance, but not benefits paid directly to or by the institution.
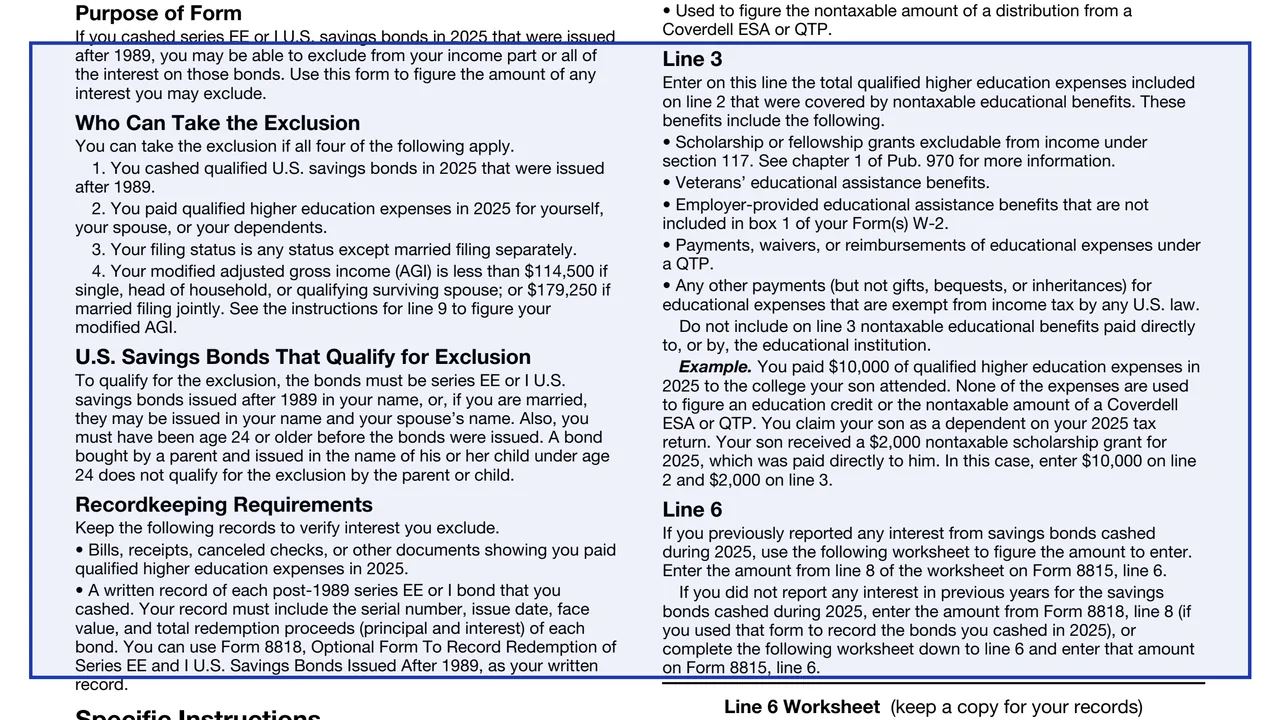
Enter the total principal and interest from the bonds cashed during 2025, then the interest included. Use the Line 6 Worksheet, or Form 8818, line 8, if no interest from those bonds was reported in earlier years.
If line 4 is equal to or more than line 5, enter 1.000. Otherwise divide line 4 by line 5, rounded to at least three places, and multiply line 6 by the result.
Figure modified AGI with the Line 9 Worksheet. Enter $99,500 or $149,250 on line 10, finish the phaseout on lines 11 to 13, and enter line 14 here and on Schedule B (Form 1040), line 3.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach Form 8815 to Form 1040 or 1040-SR. The amount on line 14 is also entered on Schedule B (Form 1040), line 3.
The form says to stop if line 4 is zero or less, or if line 9 is $114,500 or more for single, head of household, or qualifying surviving spouse, or $179,250 or more if married filing jointly.
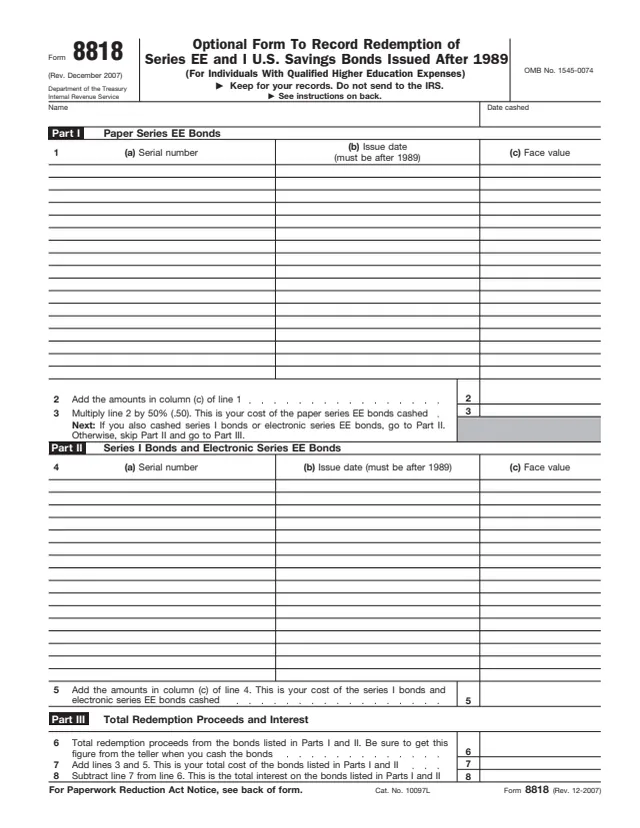
The instructions list bills, receipts, canceled checks or other proof of 2025 education expenses, and a written record of each bond cashed with its serial number, issue date, face value and total redemption proceeds.
The instructions say Form 8818, Optional Form To Record Redemption of Series EE and I U.S. Savings Bonds Issued After 1989, can serve as the written record.
The Line 6 and Line 9 Worksheets are each marked keep a copy for your records.
8818
107 fields, 2 pages
1040
72 fields, 1 page

1040
199 fields, 2 pages
8863
77 fields, 2 pages
1099-INT
127 fields, 7 pages
4952
17 fields, 4 pages
The form is completed by an individual filer and attached to Form 1040 or 1040-SR. The instructions list four conditions for taking the exclusion, shown in the first four cards, and separate rules for which bonds qualify.
No tool matches that search.
The instructions say it figures the amount of any interest from Series EE or I U.S. savings bonds issued after 1989 and cashed in 2025 that may be excluded from income.
The instructions list any filing status except married filing separately as one of the four conditions for the exclusion.
The form says to stop if modified AGI on line 9 is $114,500 or more for single, head of household, or qualifying surviving spouse, or $179,250 or more if married filing jointly. The phaseout starts at $99,500 or $149,250.
The instructions say a bond bought by a parent and issued in the name of a child under age 24 does not qualify for the exclusion by the parent or child.
The instructions say tuition and fees required for enrollment or attendance, and contributions to a Coverdell ESA or QTP. Room and board and certain sports, games or hobby courses are excluded.
Line 14 is entered on Schedule B (Form 1040), line 3, and Form 8815 is attached to Form 1040 or 1040-SR.