Header
Name and Social Security number, the main home address if it differs from the return, and the issuer's name, MCC number and issue date.
8396
Mortgage Interest Credit
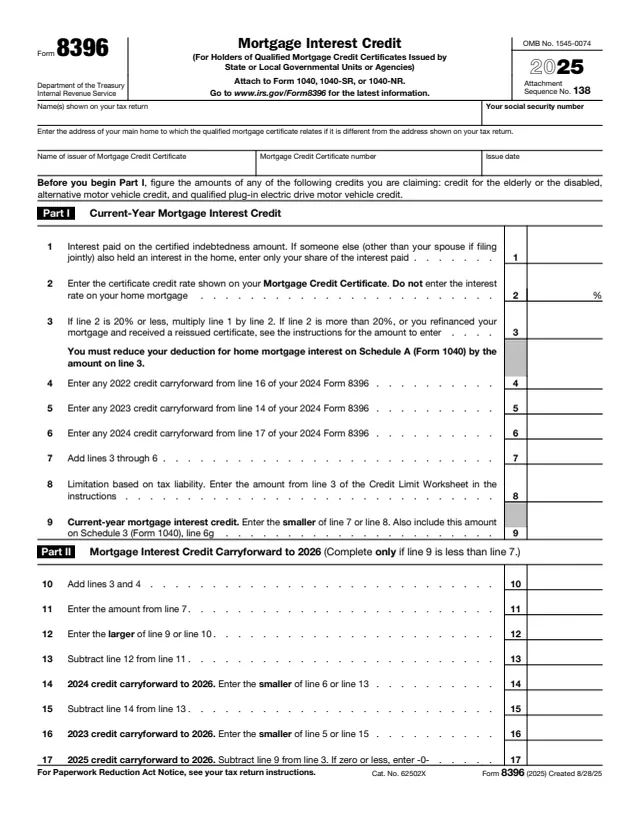
Form 8396, Mortgage Interest Credit, is used to figure the mortgage interest credit for 2025 and any credit carryforward to 2026. Its subtitle says it is for holders of qualified Mortgage Credit Certificates issued by state or local governmental units or agencies. It is attached to Form 1040, 1040-SR or 1040-NR.
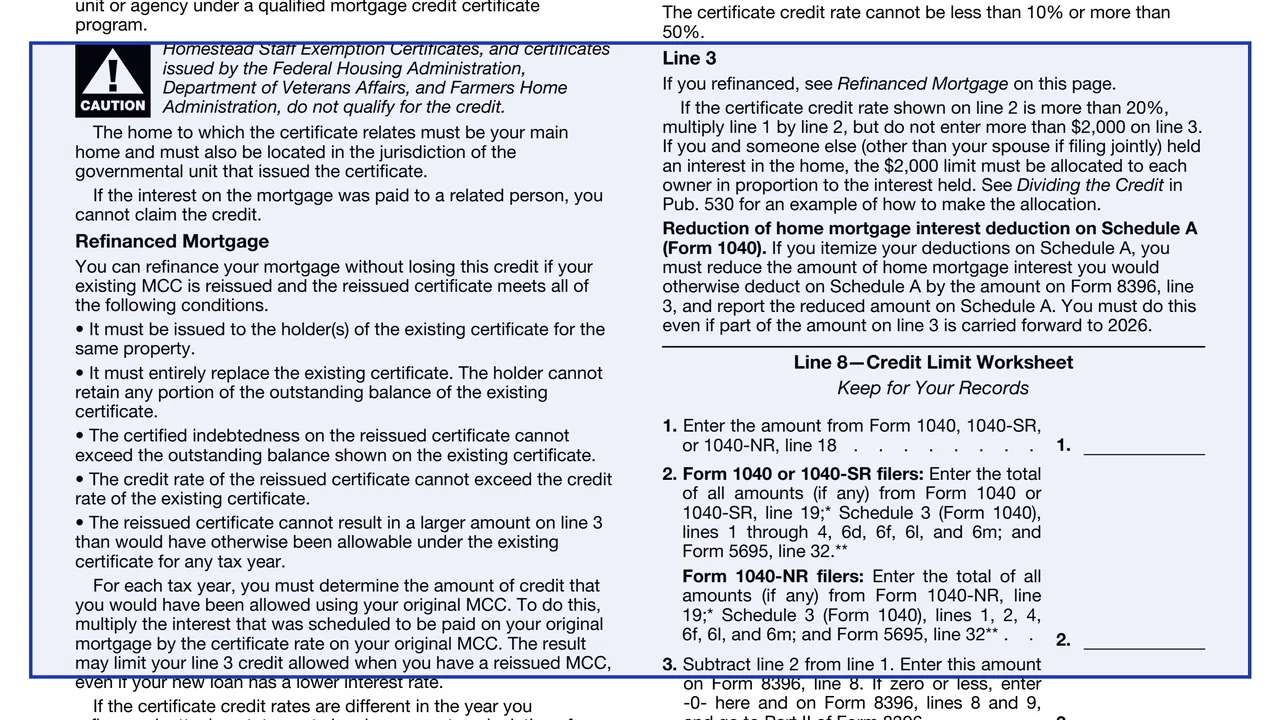
The instructions say the credit can be claimed only by someone issued a qualified Mortgage Credit Certificate (MCC) by a state or local governmental unit or agency under a qualified mortgage credit certificate program. The home has to be the main home and located in the jurisdiction of the unit that issued the certificate. The form says certificates issued by the Federal Housing Administration, Department of Veterans Affairs and Farmers Home Administration, and Homestead Staff Exemption Certificates, do not qualify.
This page has the 2025 edition of the form, which carries its own instructions on page 2. You can fill out the PDF free in your browser on this page and download it without an account.
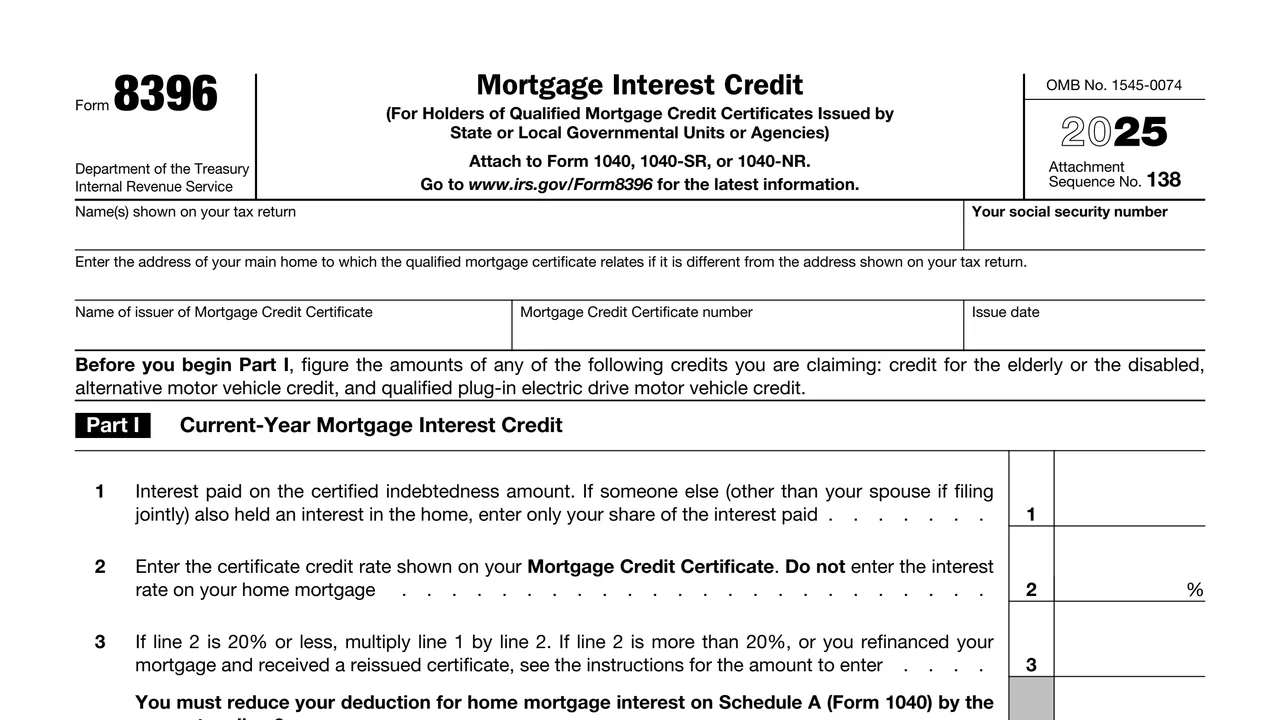
Name and Social Security number, the main home address if it differs from the return, and the issuer's name, MCC number and issue date.
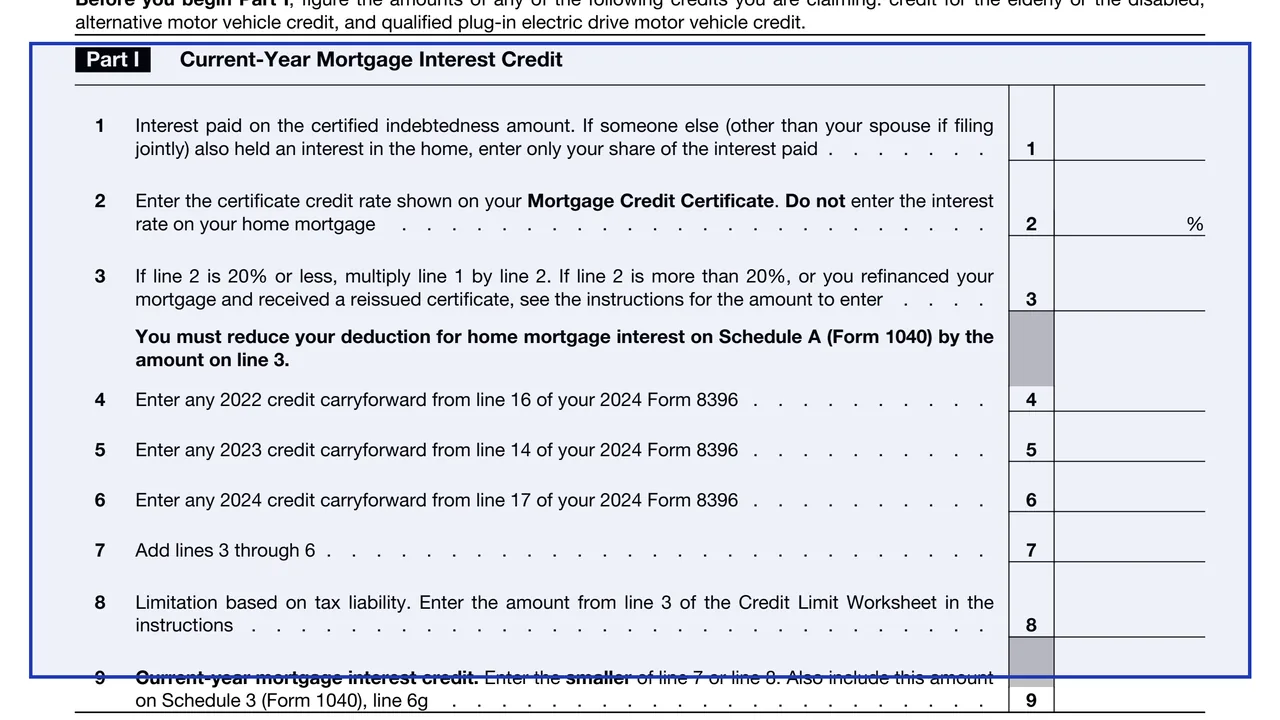
Interest paid on the certified indebtedness amount, the certificate credit rate from the MCC, and the credit figured from those two lines.
Carryforwards from 2022, 2023 and 2024 taken from lines 16, 14 and 17 of the 2024 Form 8396, and their total with line 3.
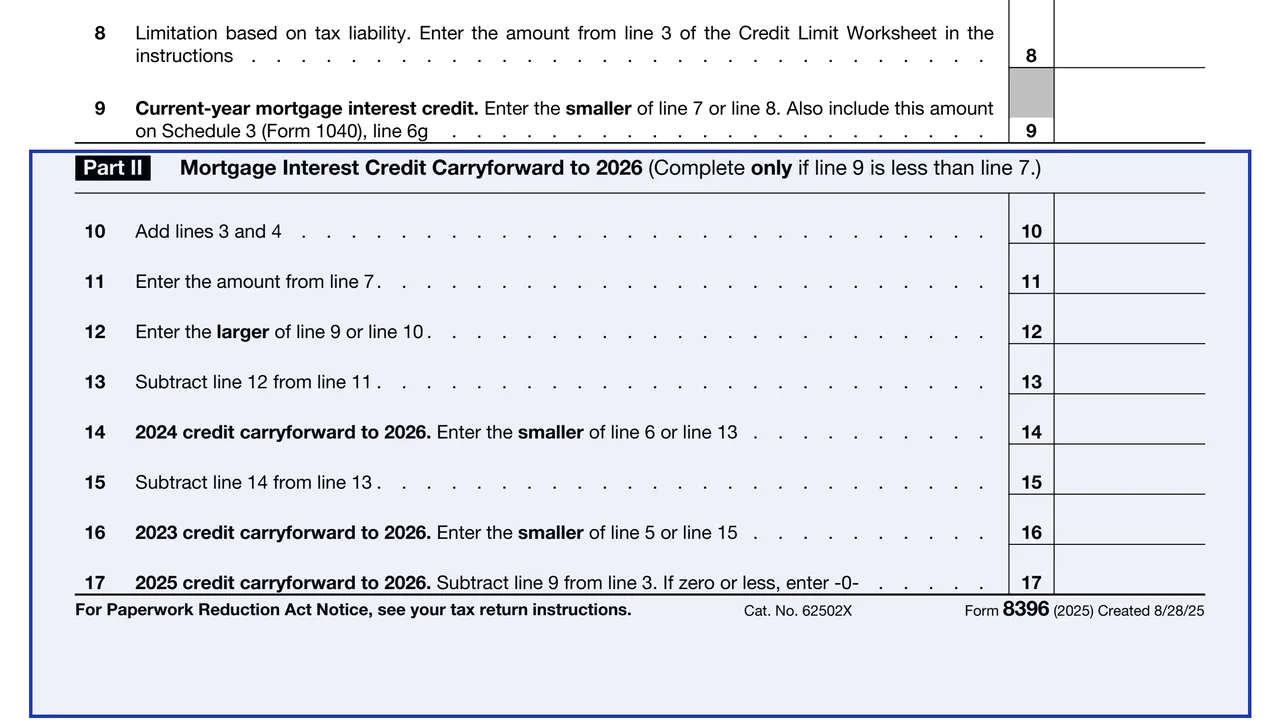
The limitation based on tax liability from the Credit Limit Worksheet, and the current-year credit, which also goes on Schedule 3 (Form 1040), line 6g.
Mortgage Interest Credit Carryforward to 2026, completed only if line 9 is less than line 7. It splits the unused credit by the year it came from.
Who can claim the credit, refinanced mortgages, recapture, line instructions and the Credit Limit Worksheet for line 8.
Enter the certificate details. The form says to first figure any credit for the elderly or the disabled, alternative motor vehicle credit, and qualified plug-in electric drive motor vehicle credit being claimed.
Enter the interest paid during the year on the certified indebtedness amount shown on the MCC. The instructions say this is in most cases box 1 of Form 1098, and point to Pub. 530 when the MCC covers only part of the loan.
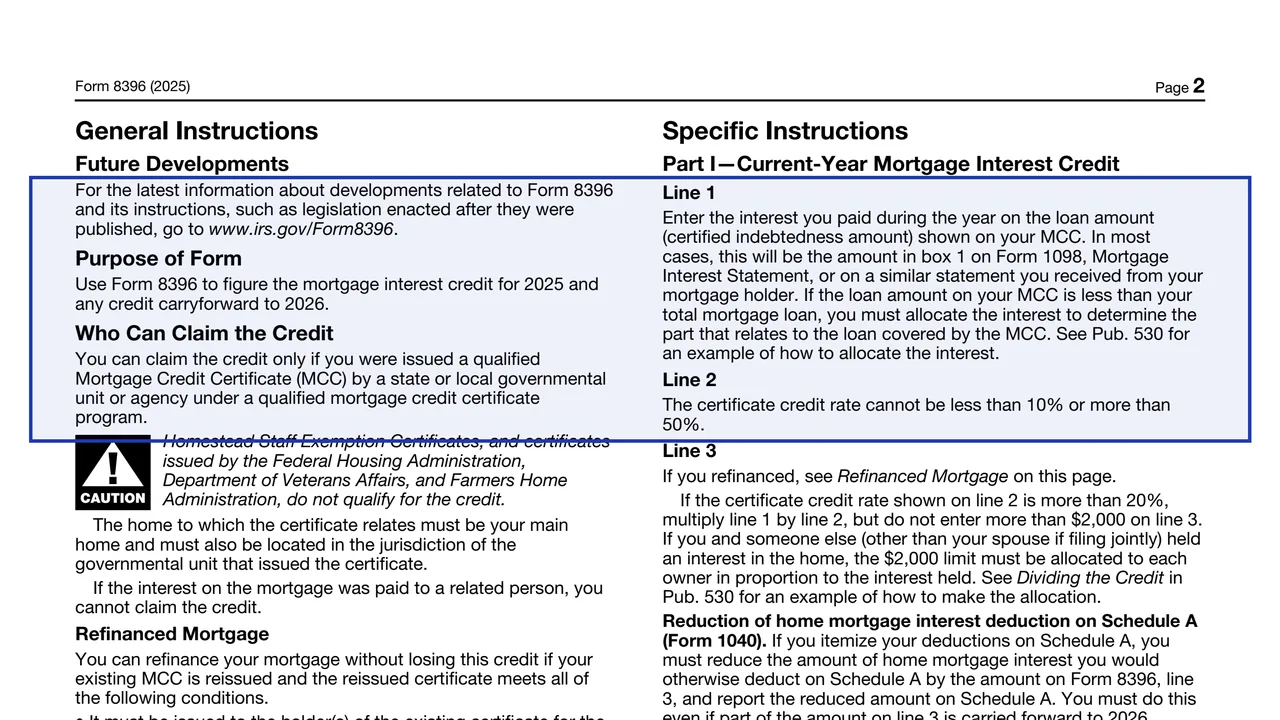
Enter the certificate credit rate shown on the MCC, not the interest rate on the mortgage. The instructions say the rate cannot be less than 10% or more than 50%.
If line 2 is 20% or less, multiply line 1 by line 2. If it is more than 20%, multiply but do not enter more than $2,000. The form says the Schedule A home mortgage interest deduction is reduced by this amount.
Enter any carryforwards from the 2024 Form 8396 and add lines 3 to 6. Complete the Credit Limit Worksheet for line 8, then enter the smaller of line 7 or line 8 on line 9.
Complete it only if line 9 is less than line 7. The instructions say unused credit can be carried forward to the next 3 tax years or until used, and to keep a copy of the form for next year.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach Form 8396 to Form 1040, 1040-SR or 1040-NR. The line 9 credit is also included on Schedule 3 (Form 1040), line 6g.
The instructions say that anyone who itemizes reduces the home mortgage interest deducted on Schedule A by the amount on line 3, even if part of that amount is carried forward to 2026.
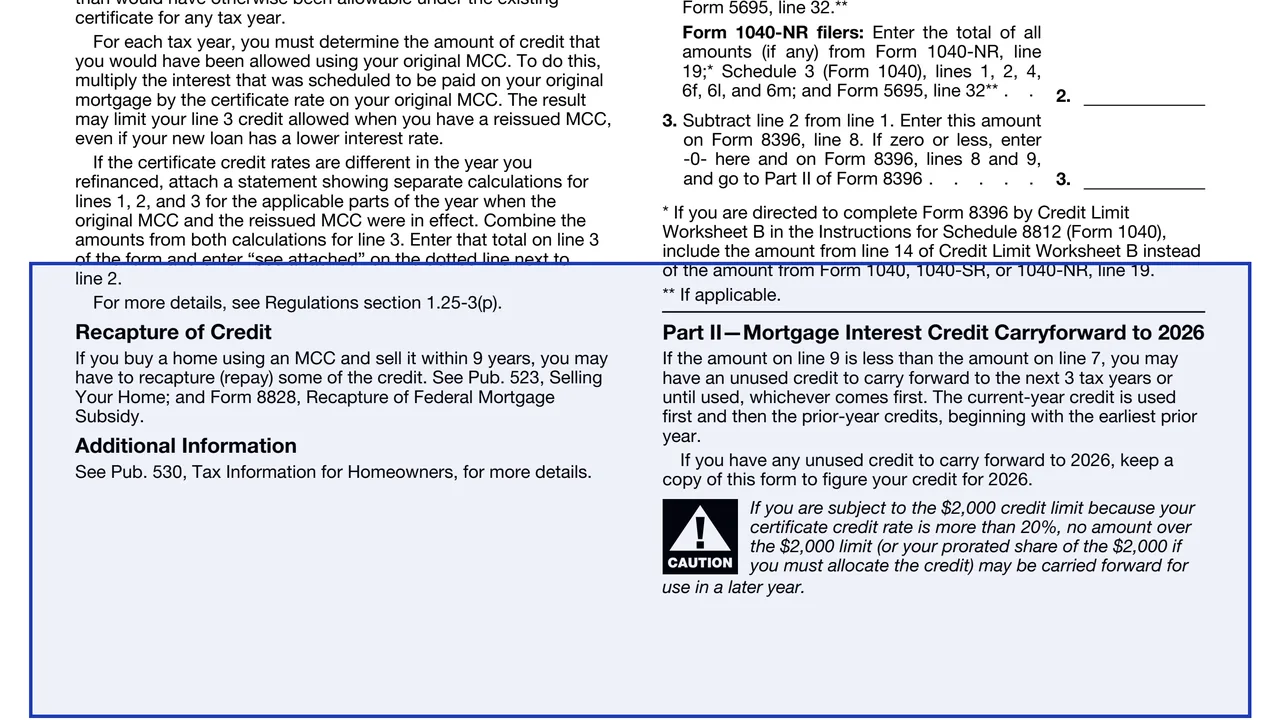
With a certificate credit rate over 20%, line 3 is capped at $2,000, shared among co-owners by interest held. The instructions say no amount over that limit may be carried forward.
If the credit rates differ in the year of a refinance, the instructions say to attach a statement with separate calculations for lines 1, 2 and 3 and enter "see attached" next to line 2.
The instructions say a home bought using an MCC and sold within 9 years may require repaying some of the credit, and point to Pub. 523 and Form 8828.
1098
41 fields, 4 pages
1040
33 fields, 1 page
1040
37 fields, 1 page
8828
33 fields, 1 page

1040
199 fields, 2 pages
1040-NR
171 fields, 2 pages
The form is filed by individuals with their own income tax return. The certificate itself comes from a state or local governmental unit or agency.
No tool matches that search.
The instructions say only someone issued a qualified MCC by a state or local governmental unit or agency under a qualified mortgage credit certificate program, for a main home in that unit's jurisdiction.
No. The form says to enter the certificate credit rate shown on the MCC and not the interest rate on the home mortgage.
When the certificate credit rate is more than 20%, the instructions say not to enter more than $2,000 on line 3. The credit is also limited by tax liability through the Credit Limit Worksheet.
Yes for those who itemize. The instructions say the Schedule A home mortgage interest is reduced by the amount on line 3.
The instructions say the credit can continue if the existing MCC is reissued and the reissued certificate meets every condition listed, such as not exceeding the old credit rate.
The instructions say that if a home bought using an MCC is sold within 9 years, some of the credit may have to be repaid. They point to Pub. 523 and Form 8828.
To the next 3 tax years or until used, whichever comes first. The current-year credit is used first, then prior-year credits starting with the earliest.