Part I, lines 1 to 4
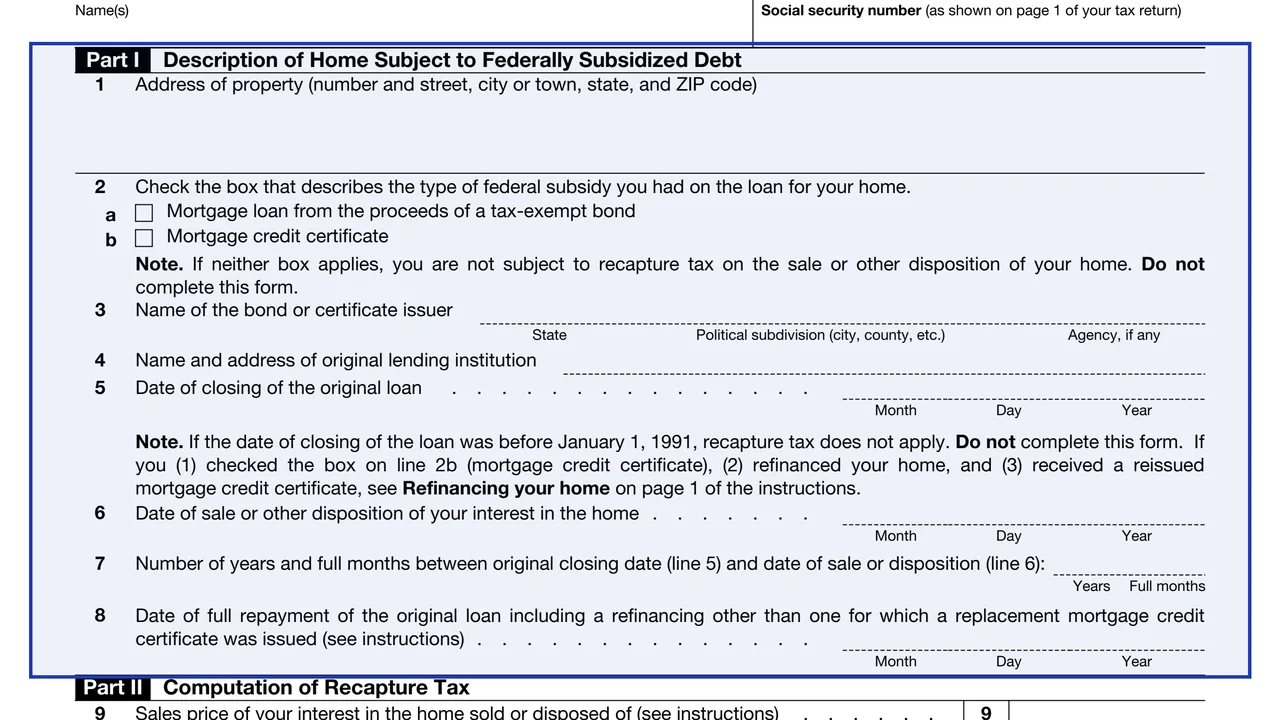
Property address, the type of federal subsidy, the bond or certificate issuer (state, political subdivision, agency), and the name and address of the original lending institution.
8828
Recapture of Federal Mortgage Subsidy
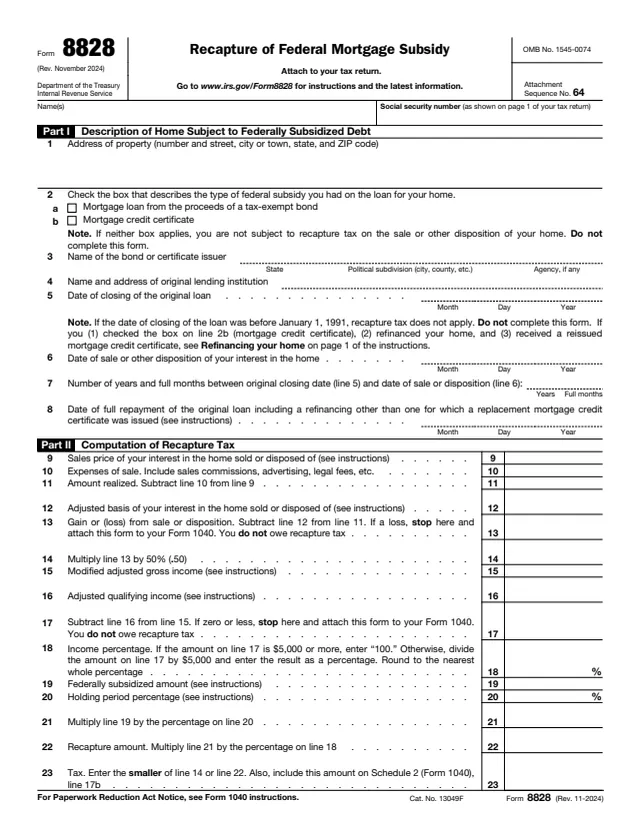
The IRS says to use Form 8828 to figure and report the recapture tax on the mortgage subsidy if you sold or otherwise disposed of your federally subsidized home. The form covers two kinds of federal subsidy on a home loan: a mortgage loan from the proceeds of a tax-exempt bond, and a mortgage credit certificate. The form says that if neither applies, there is no recapture tax on the sale or other disposition of the home and the form is not completed.
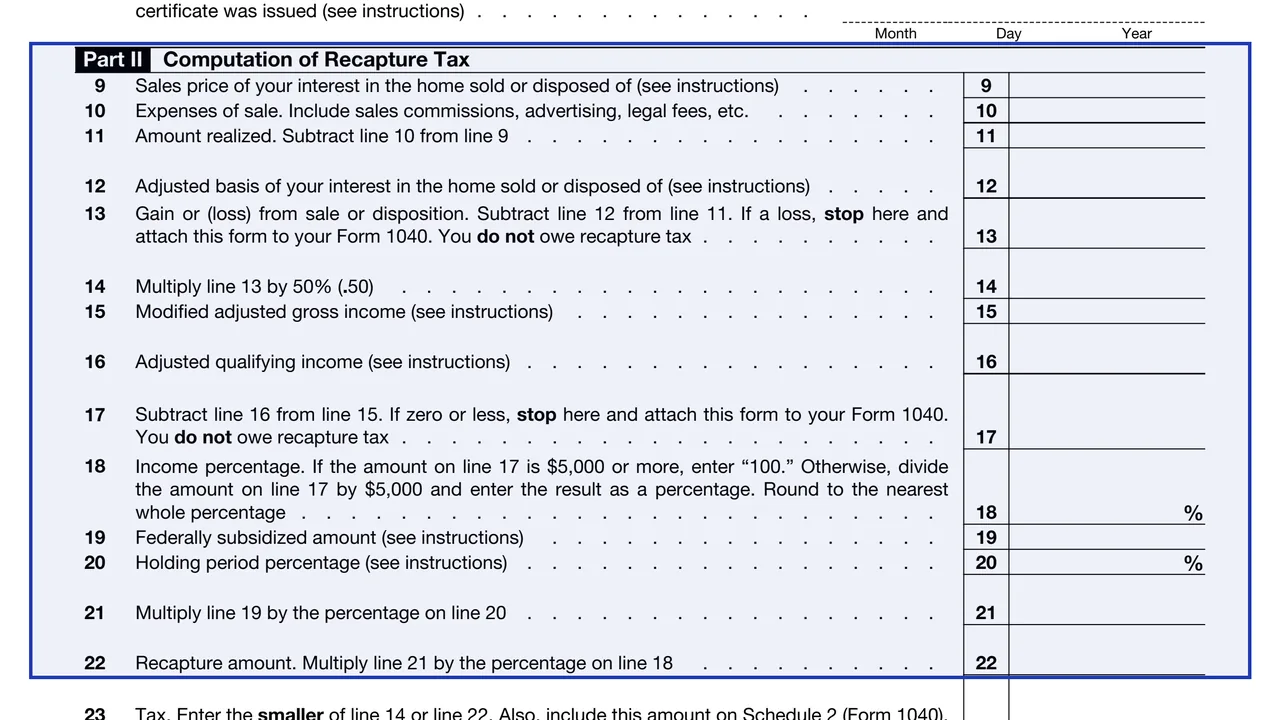
Part I describes the home and the subsidized loan: the property address, the issuer, the original lender and the key dates. Part II computes the recapture tax from the gain on the sale, the filer's income and the federally subsidized amount. The tax on line 23 is also included on Schedule 2 (Form 1040), line 17b, and the form is attached to the tax return.
You can fill out Form 8828 free in your browser on this page and download the result without an account.
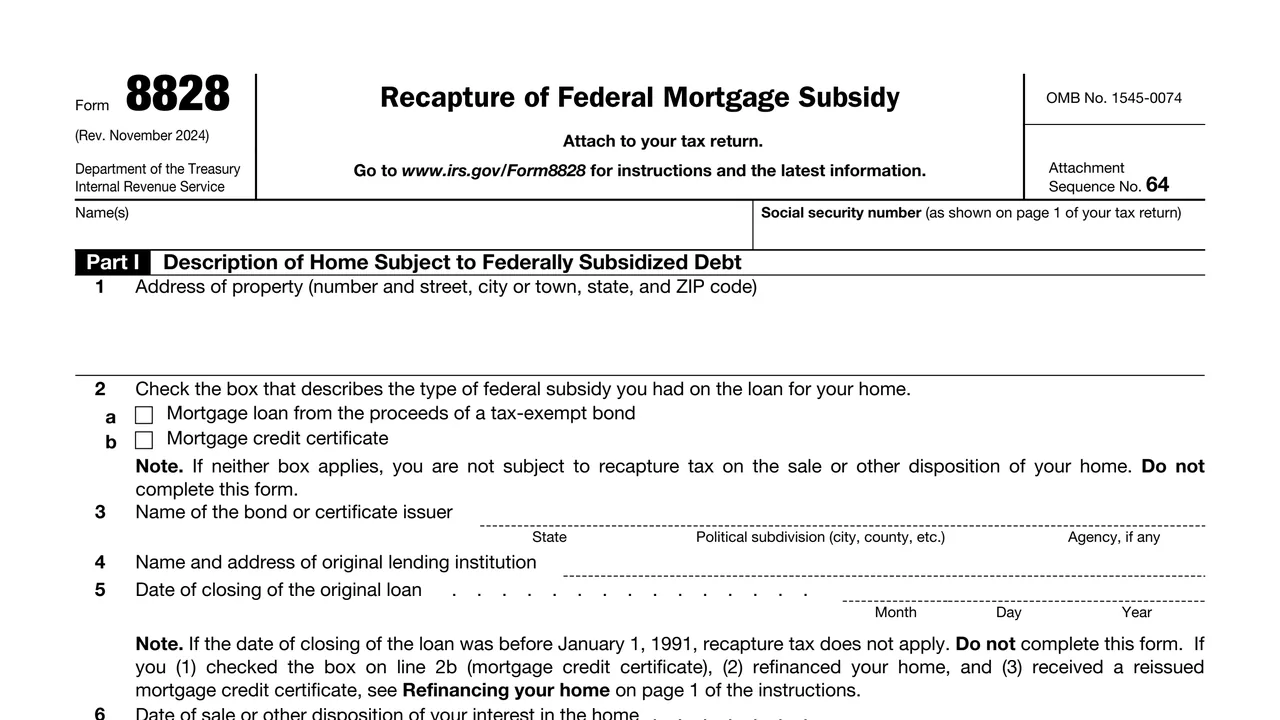
Property address, the type of federal subsidy, the bond or certificate issuer (state, political subdivision, agency), and the name and address of the original lending institution.
Closing date of the original loan, date of sale or disposition, the years and full months between them, and the date of full repayment of the original loan.
Sales price, expenses of sale, amount realized, adjusted basis, gain or loss, and the gain multiplied by 50% (.50).
Modified adjusted gross income, adjusted qualifying income, the difference between them, and the income percentage.
Federally subsidized amount, holding period percentage, recapture amount, and the tax, which is the smaller of line 14 or line 22.
Enter the name(s) and the social security number as shown on page 1 of the tax return.
Enter the property address, check box 2a or 2b for the type of subsidy, then enter the issuer and the name and address of the original lending institution.
Enter the original closing date, the sale or disposition date, the years and full months between them, and the date of full repayment, including a refinancing other than one for which a replacement mortgage credit certificate was issued.
Subtract expenses of sale from the sales price, subtract the adjusted basis to get the gain or loss, and multiply the gain by 50% (.50). If line 13 is a loss, the form says to stop there.
Subtract adjusted qualifying income from modified adjusted gross income. If line 17 is $5,000 or more, enter 100 on line 18. Otherwise divide line 17 by $5,000 and round to the nearest whole percentage.
Multiply the federally subsidized amount by the holding period percentage, then by the income percentage. Enter the smaller of line 14 or line 22 on line 23 and include it on Schedule 2 (Form 1040), line 17b.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. Lines 13 and 17 say to attach it to Form 1040 even when no recapture tax is owed.
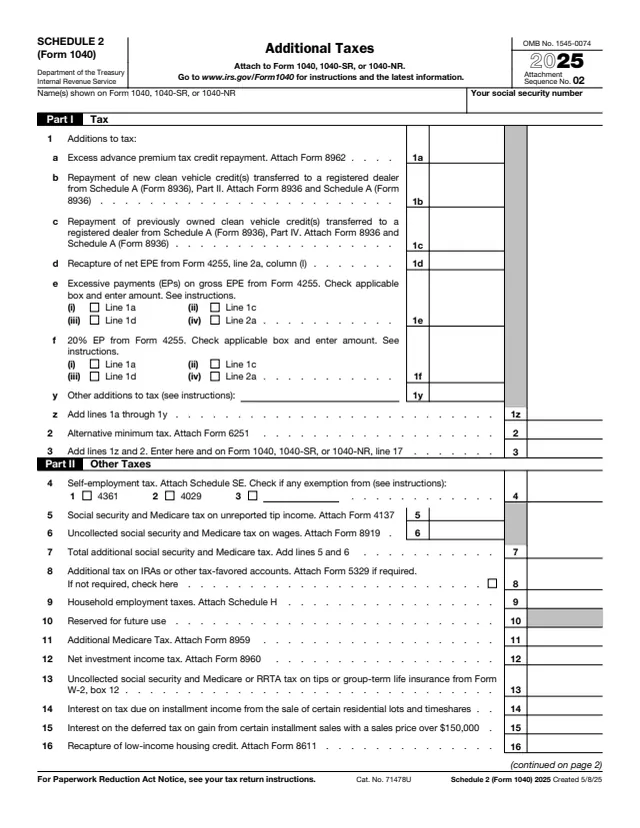
Line 23 says to include the tax on Schedule 2 (Form 1040), line 17b.
Lines 8, 9, 12, 15, 16, 19 and 20 say to see the instructions. The form points to www.irs.gov/Form8828 for instructions and the latest information.
If box 2b is checked, the home was refinanced and a reissued mortgage credit certificate was received, the form points to Refinancing your home on page 1 of the instructions.
The form is completed by the taxpayer who sold or otherwise disposed of a home with a federally subsidized loan, and is attached to that taxpayer's return.
No tool matches that search.
The About page says to use it to figure and report the recapture tax on the mortgage subsidy if you sold or otherwise disposed of your federally subsidized home.
Line 2 lists two: a mortgage loan from the proceeds of a tax-exempt bond, and a mortgage credit certificate. The form says that if neither applies, there is no recapture tax and the form is not completed.
The form says that if the date of closing of the loan was before January 1, 1991, recapture tax does not apply.
Line 13 says to stop there and attach the form to Form 1040, and that no recapture tax is owed.
Line 23 says to include it on Schedule 2 (Form 1040), line 17b.
The form says to enter 100 if line 17 is $5,000 or more. Otherwise divide line 17 by $5,000 and round to the nearest whole percentage.