Election boxes A to D
A, mixed straddle election. B, straddle-by-straddle identification election. C, mixed straddle account election. D, net section 1256 contracts loss election.
6781
Gains and Losses From Section 1256 Contracts and Straddles
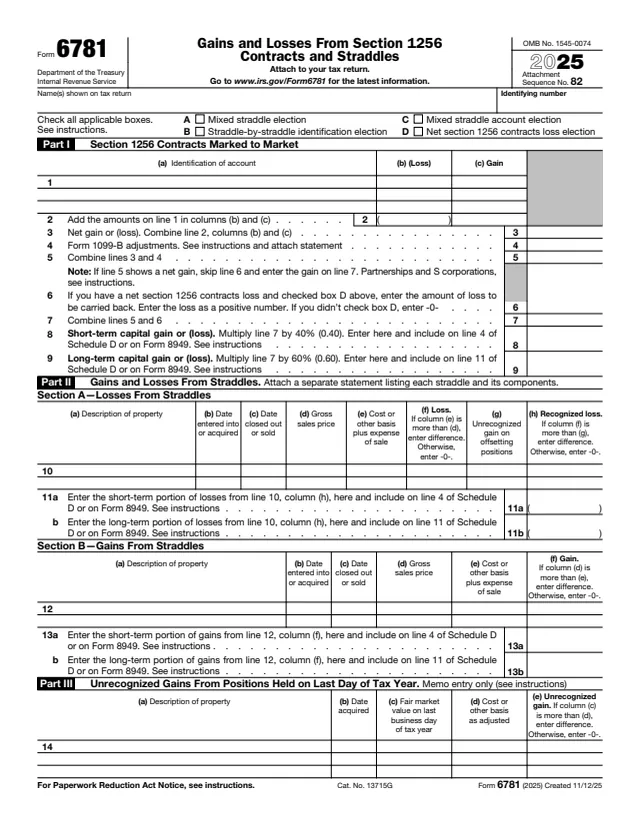
Form 6781 reports gains and losses from section 1256 contracts and straddles. The About Form 6781 page says it is used to report any gain or loss on section 1256 contracts under the mark-to-market rules, and gains and losses under section 1092 from straddle positions. The instructions define a section 1256 contract as any regulated futures contract, foreign currency contract, nonequity option, dealer equity option or dealer securities futures contract.
Under the mark-to-market rules, the instructions say each section 1256 contract held at year end is treated as if it were sold at fair market value on the last business day of the tax year. Capital gains and losses on these contracts are treated as 60% long term and 40% short term, regardless of how long the contracts were held. The 2025 form is attached to the tax return and carries its own instructions on pages 2 to 4.
You can fill out Form 6781 free in your browser on this page and download it without an account.
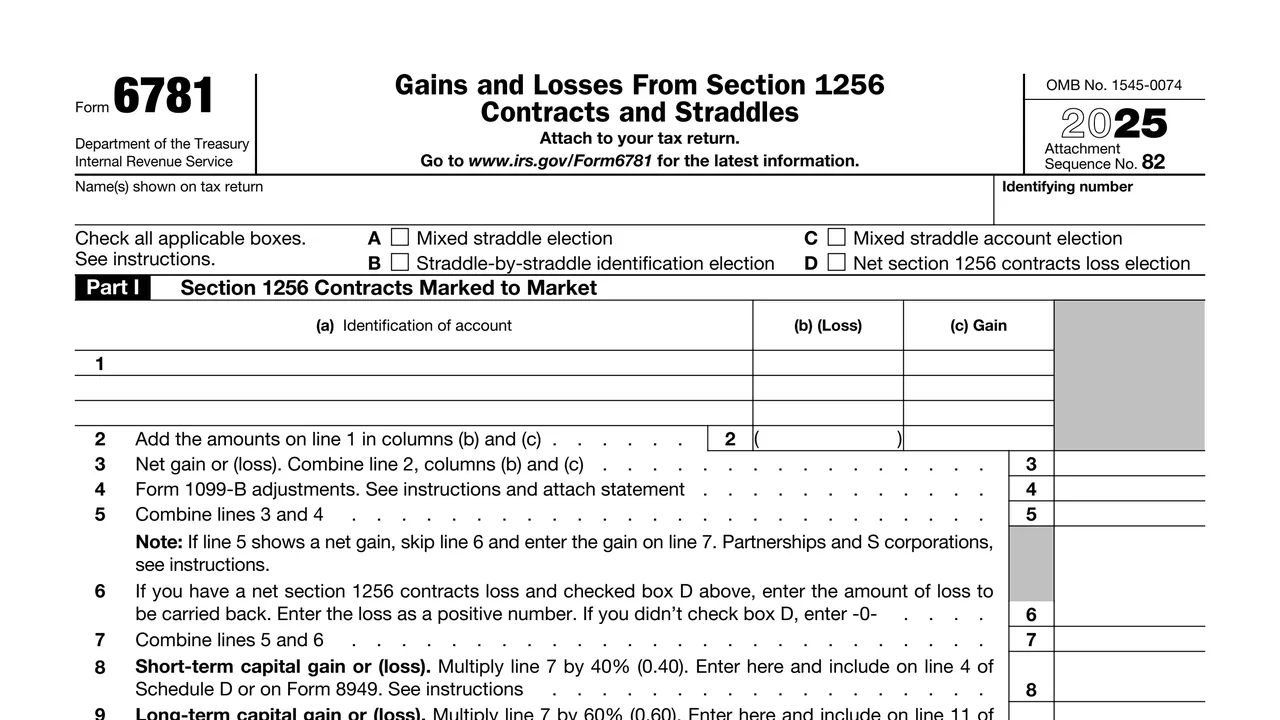
A, mixed straddle election. B, straddle-by-straddle identification election. C, mixed straddle account election. D, net section 1256 contracts loss election.
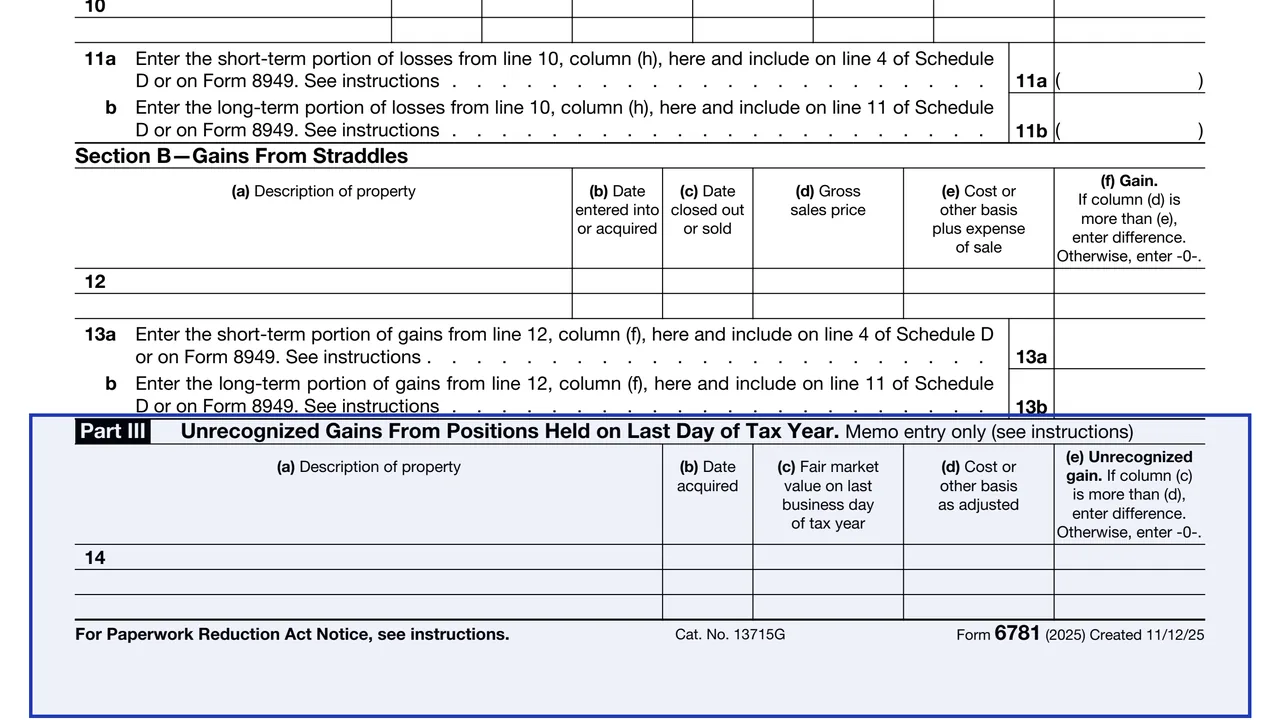
Each account with loss and gain columns, the totals and net gain or loss, Form 1099-B adjustments on line 4, and any loss carried back on line 6.
Line 8 is line 7 multiplied by 40% (0.40) as short-term gain or loss. Line 9 is line 7 multiplied by 60% (0.60) as long-term gain or loss.
Line 10 lists each position with dates, sales price, basis, loss, unrecognized gain on offsetting positions and the recognized loss. Lines 11a and 11b split it into short and long term.
Line 12 lists each position with dates, sales price, basis and gain. Lines 13a and 13b split the gain into short and long term.
A memo entry on line 14 for positions held on the last day of the tax year whose fair market value is more than their cost or other basis.
Check all boxes that apply. The instructions say a box A election applies for all later years and cannot be revoked without IRS consent.
List gains and losses from section 1256 contracts open at year end or closed out during the year. For a Form 1099-B, the instructions say to use the amount from box 11 and enter "Form 1099-B" and the broker's name in column (a).
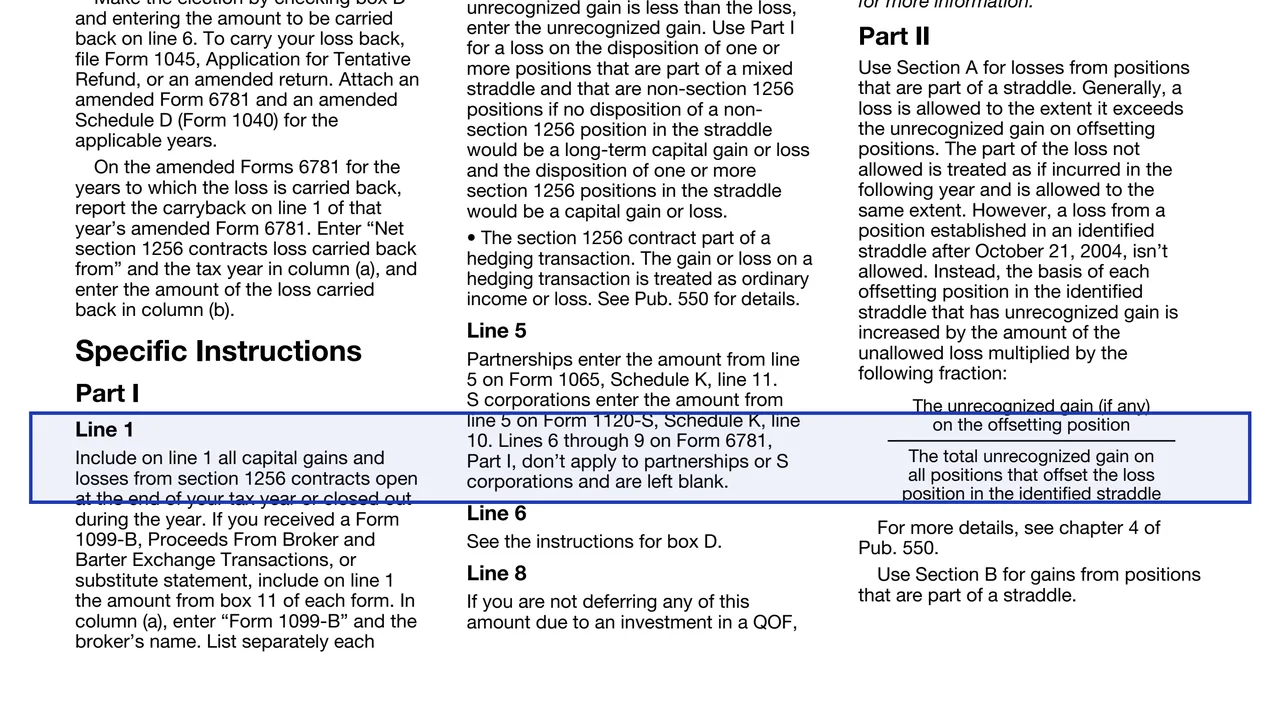
Enter the total of any adjustments for a straddle or hedging transaction included on a Form 1099-B and attach a statement listing them. The instructions say not to use line 4 for a QOF-related deferral.
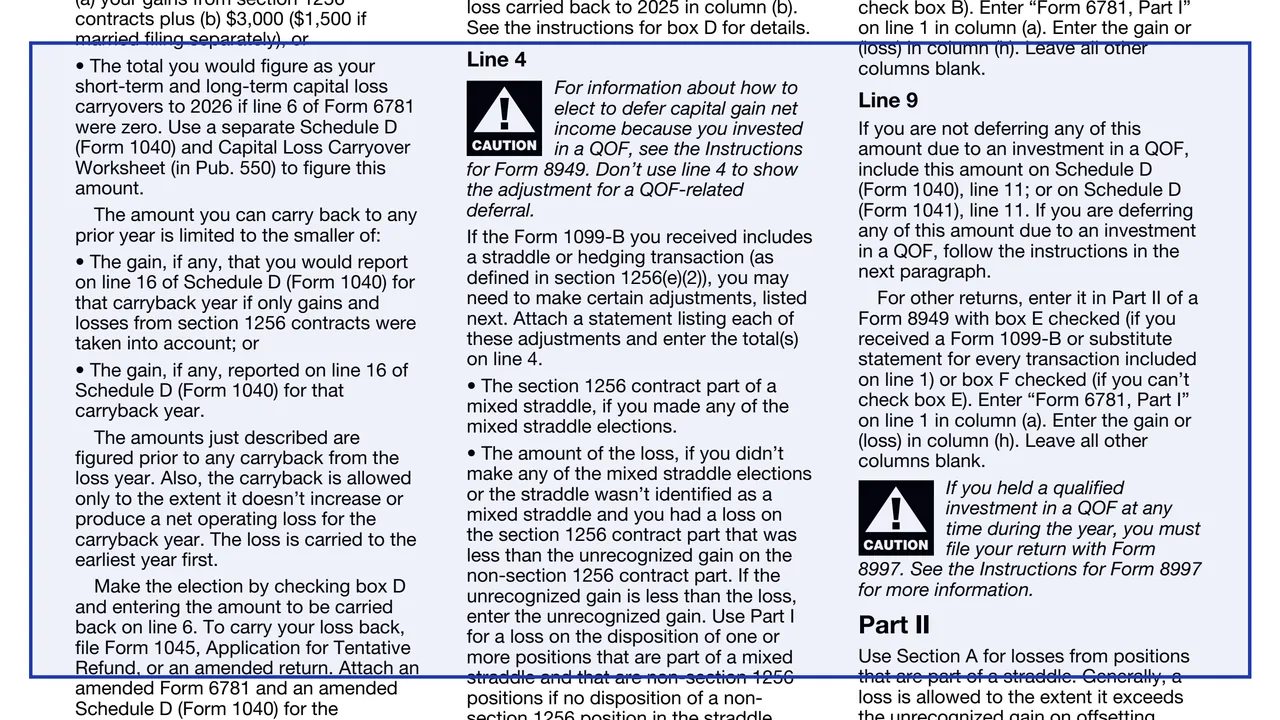
Enter a net section 1256 contracts loss to carry back only if box D is checked, otherwise enter -0-. The instructions say the loss can be carried back 3 years and that corporations, estates and trusts are not eligible for this election.
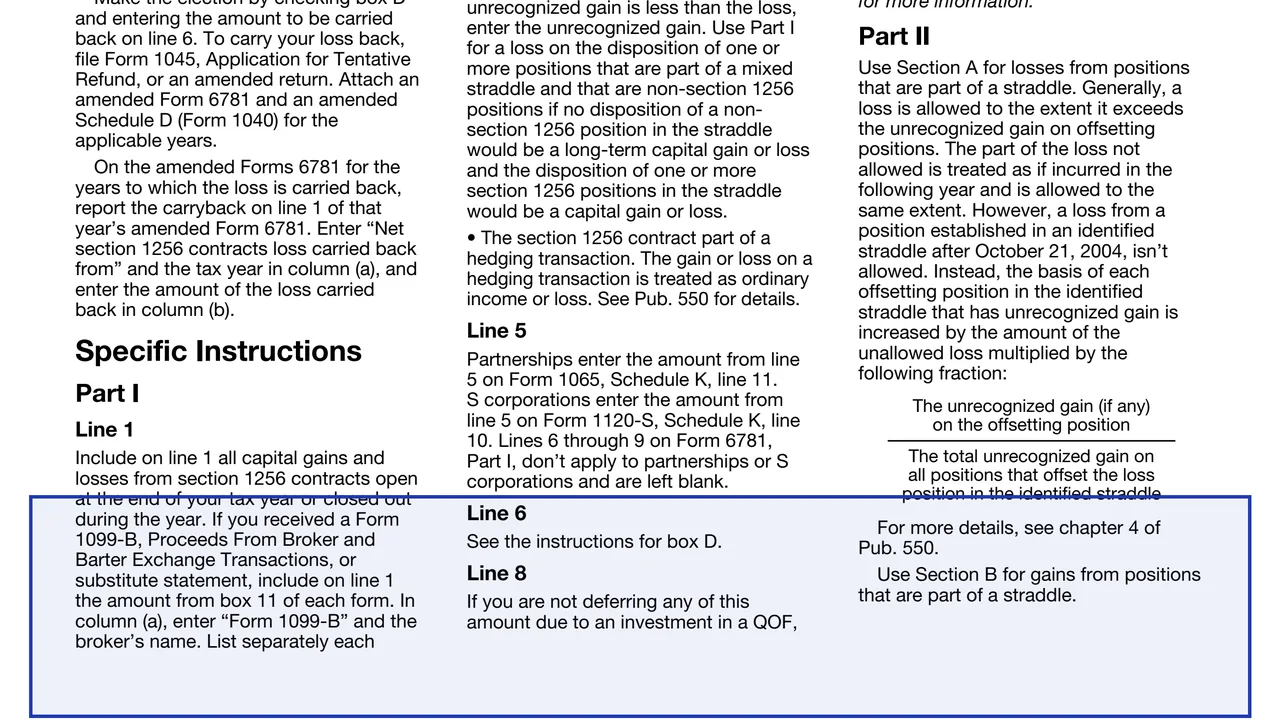
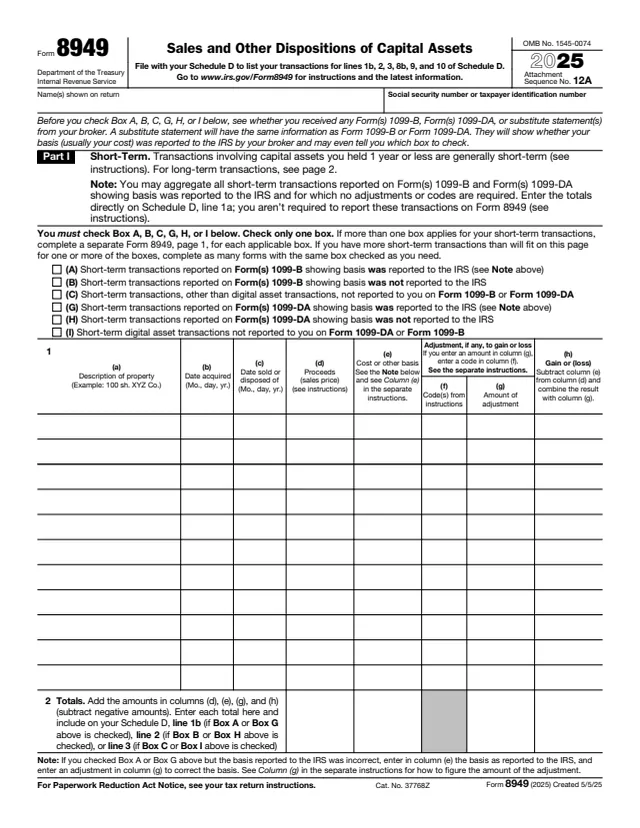
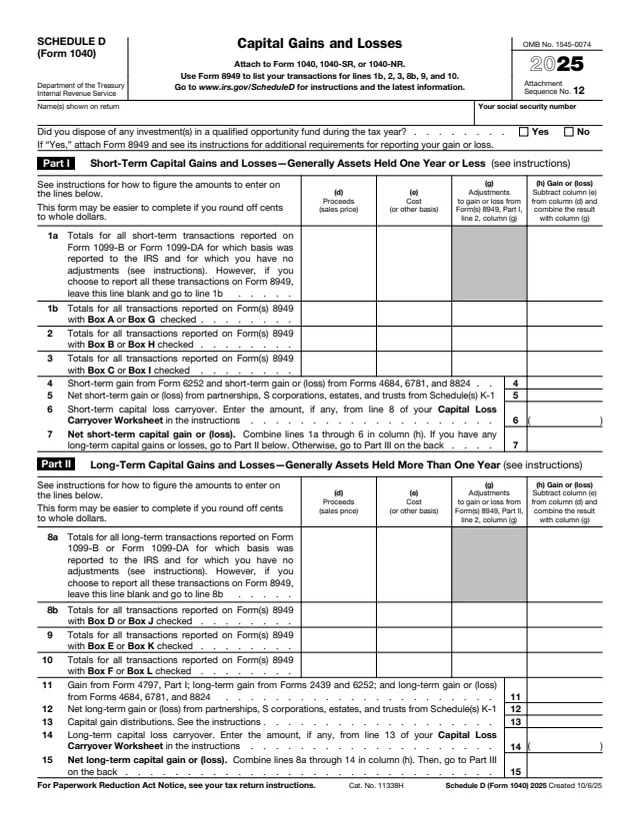
Multiply line 7 by 40% for line 8 and by 60% for line 9. The instructions say to include them on Schedule D (Form 1040) or Schedule D (Form 1041), lines 4 and 11, or on Form 8949 for other returns.
Attach a statement listing each straddle and its components, complete Section A for losses and Section B for gains, then list year-end positions with unrecognized gain in Part III. The instructions say Part III is not completed if there is no recognized loss on any position.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." It carries Attachment Sequence No. 82.
The instructions say to file Form 1045, Application for Tentative Refund, or an amended return, and to attach an amended Form 6781 and an amended Schedule D (Form 1040) for the applicable years.
The instructions say box C is made by the due date (without extensions) of the 2025 tax return to establish accounts for 2026, by checking box C and attaching the statement required by the regulations.
The instructions say a filer who held a qualified investment in a qualified opportunity fund at any time during the year files the return with Form 8997.
If an election is made under section 988(a)(1)(B) or 988(c)(1)(D), the instructions say to attach a list of the contracts covered, the net gain or loss from them and where it is reported.
8949
202 fields, 2 pages
1040
55 fields, 2 pages
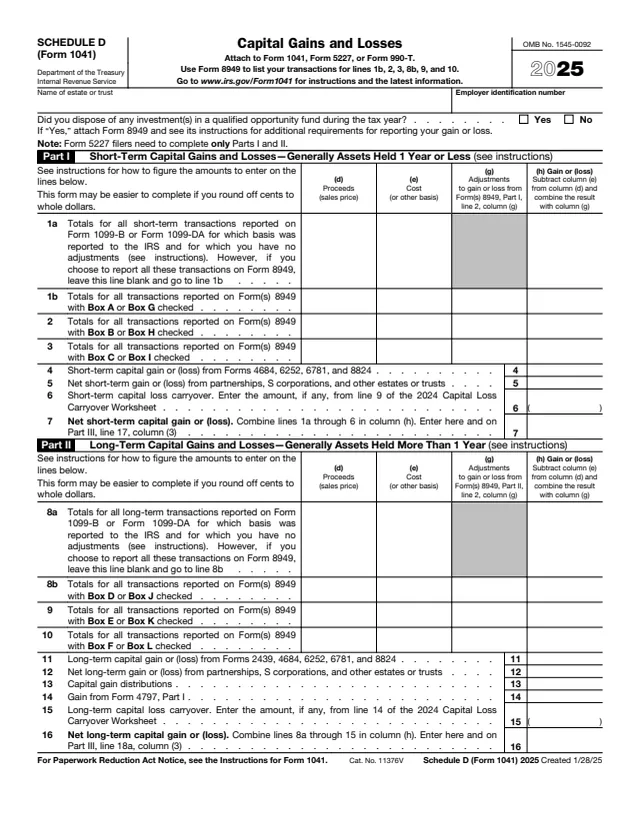
1041
87 fields, 2 pages
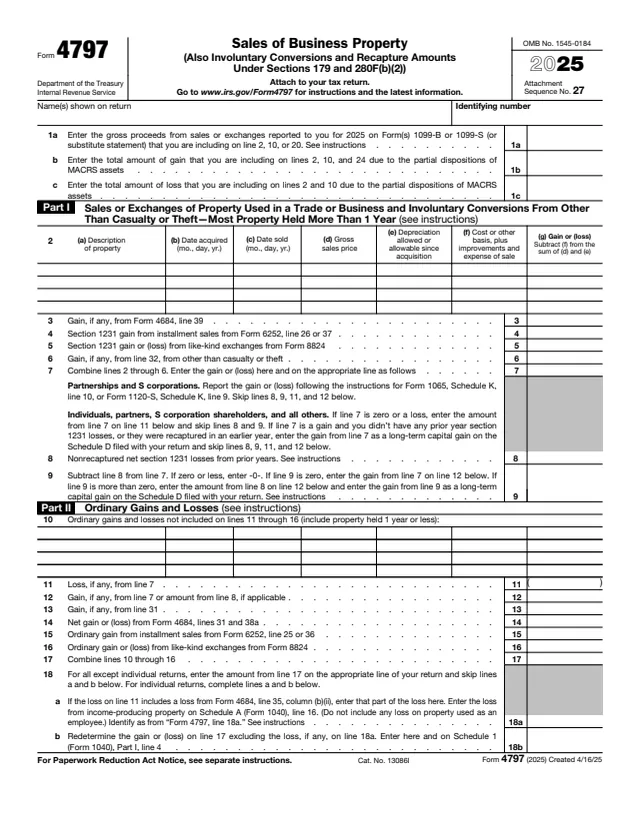
4797
182 fields, 2 pages
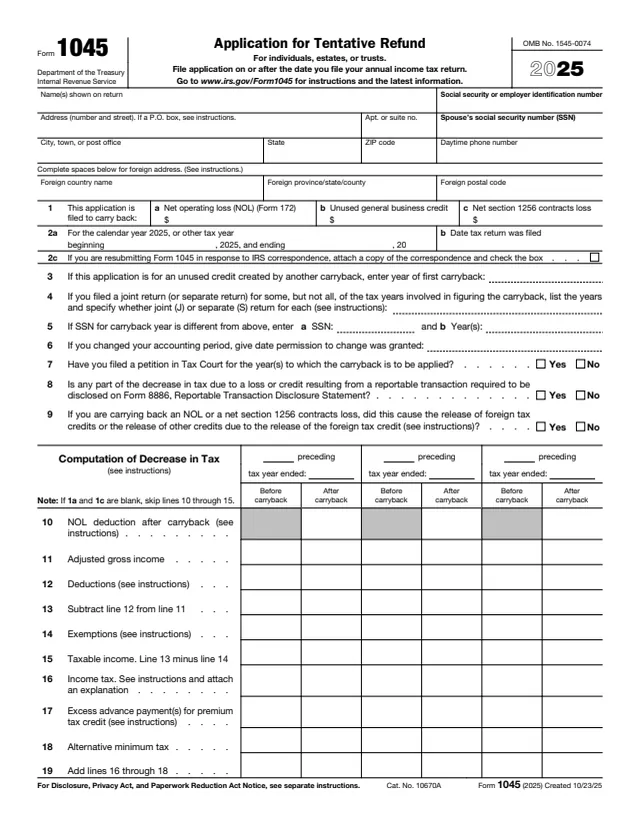
1045
193 fields, 2 pages
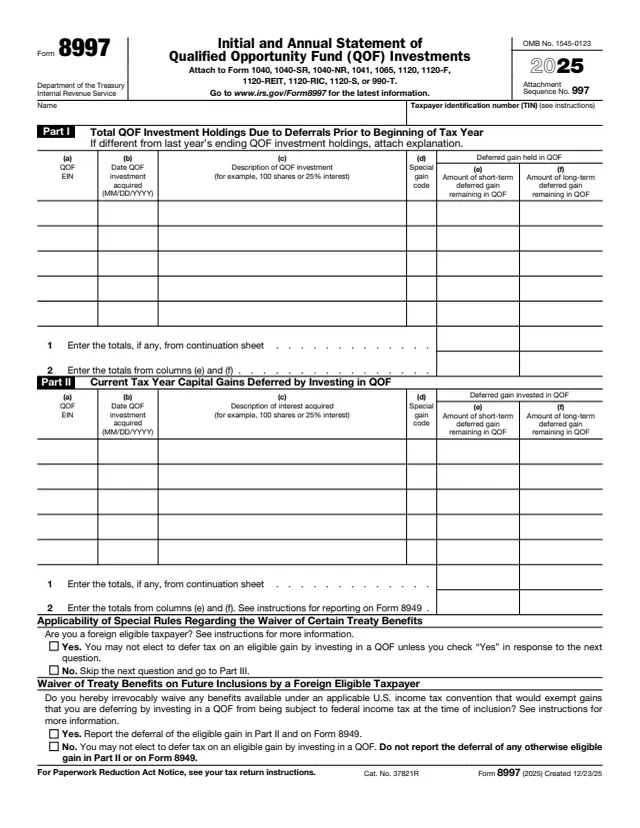
8997
143 fields, 4 pages
The form is attached to the income tax return of whoever had section 1256 contracts or straddles during the year. The instructions give line routing for individuals, estates and trusts, partnerships and S corporations.
No tool matches that search.
The instructions say it is any regulated futures contract, foreign currency contract, nonequity option, dealer equity option or dealer securities futures contract.
The instructions list securities future contracts, options on them, and interest rate, currency, basis, commodity, equity, equity index and credit default swaps, interest rate caps and floors, and similar agreements.
The instructions say capital gains and losses on section 1256 contracts are treated as 60% long term and 40% short term, regardless of how long the contracts were held.
The instructions say a straddle means offsetting positions with respect to personal property of a type that is actively traded.
The instructions say a net section 1256 contracts loss for 2025 can be carried back 3 years by checking box D, and that corporations, estates and trusts are not eligible for this election.
No. The instructions say lines 6 through 9 do not apply to partnerships or S corporations and are left blank.