Header and line 1
Names, SSN or EIN, spouse's SSN, address and daytime phone, then the amounts being carried back: 1a NOL (Form 172), 1b unused general business credit and 1c net section 1256 contracts loss.
1045
Application for Tentative Refund
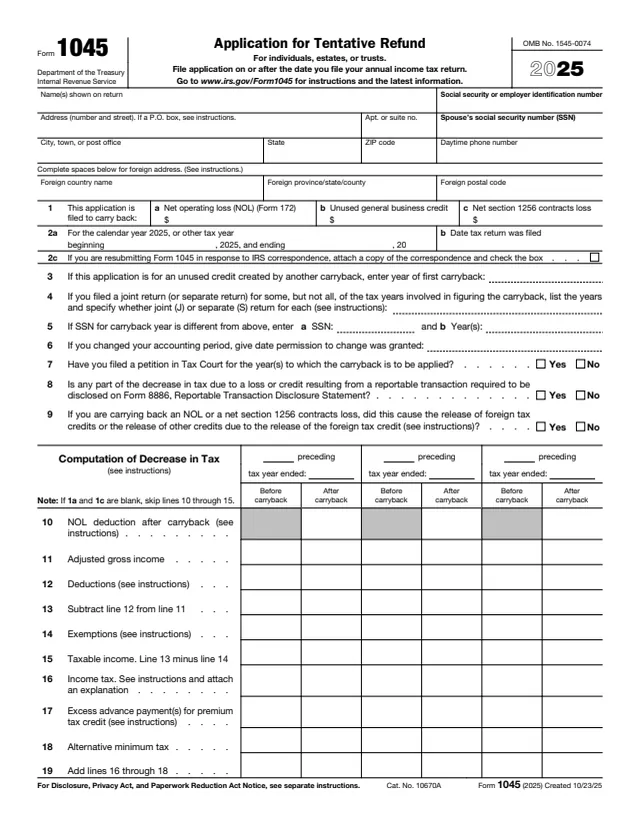
Form 1045, Application for Tentative Refund, is filed by an individual, estate or trust. The IRS About page says it is used to apply for a quick tax refund resulting from the carryback of a net operating loss (NOL), the carryback of an unused general business credit, the carryback of a net section 1256 contracts loss, or an overpayment of tax due to a claim of right adjustment under section 1341(b)(1).
The form recomputes the tax for each earlier year the loss or credit is carried back to, in pairs of before carryback and after carryback columns, and the decrease in tax is the amount applied for. The instructions say the IRS processes the application within 90 days of the later of two dates, and that the application isn't treated as a claim for credit or refund. Individuals can file Form 1040-X instead, and an estate or trust can file an amended Form 1041.
This page hosts the 2025 form. You can fill out the PDF free in your browser on this page and download it without an account.
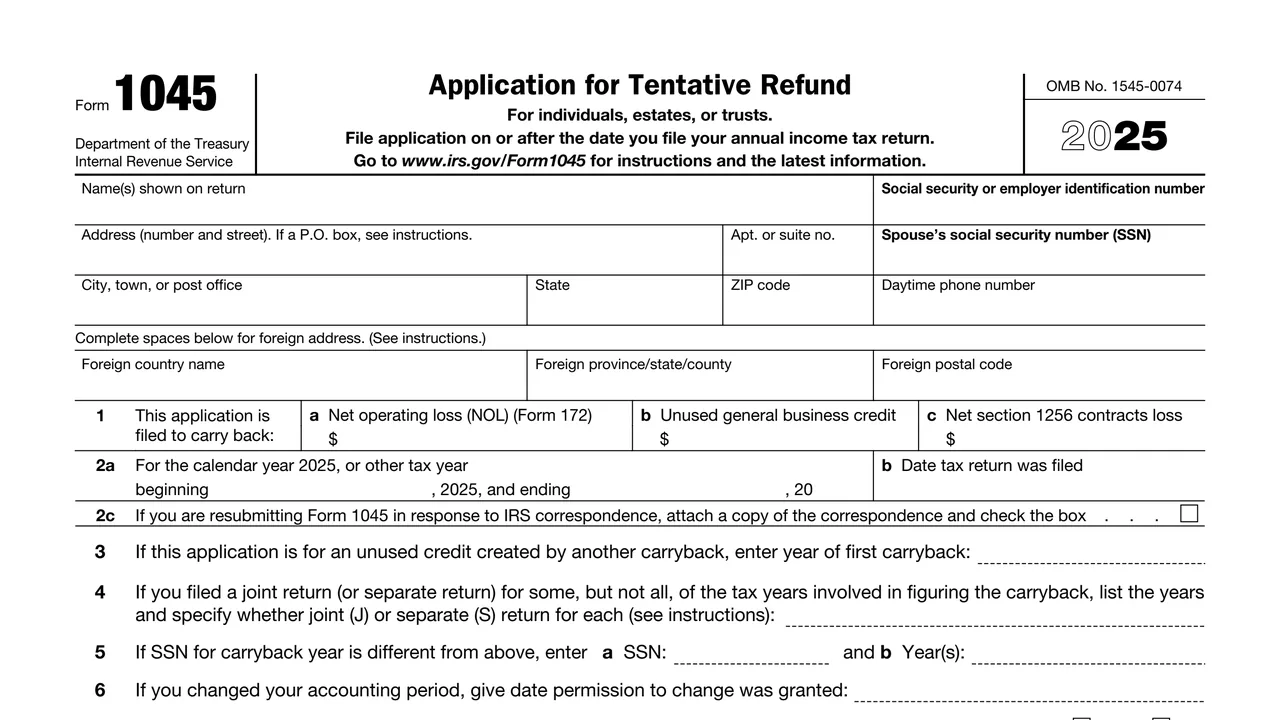
Names, SSN or EIN, spouse's SSN, address and daytime phone, then the amounts being carried back: 1a NOL (Form 172), 1b unused general business credit and 1c net section 1256 contracts loss.
The tax year and date the return was filed, a box for resubmitting after IRS correspondence, the year of first carryback, joint or separate years, a different SSN, accounting period changes, Tax Court petitions, reportable transactions and released foreign tax credits.
The computation of decrease in tax, in before carryback and after carryback columns for up to three preceding tax years: NOL deduction, AGI, deductions, exemptions, taxable income, income tax, excess advance premium tax credit and AMT.
General business credit, net premium tax credit and child tax credit, other credits, self-employment tax, Additional Medicare Tax, net investment income tax, other taxes, total tax and the decrease in tax on line 32.
The overpayment of tax due to a claim of right adjustment, then the routing number, account type and account number for any refund.
Your signature, your spouse's signature if Form 1045 is filed jointly, and the Paid Preparer Use Only section with PTIN and firm details.
Enter names and numbers as on the return. Use a P.O. box only if the post office doesn't deliver to the street address. For a foreign address, skip State and ZIP code and don't abbreviate the country. Then enter the amount carried back on line 1a, 1b or 1c.
Answer each question. Check line 2c and attach the IRS letter when resubmitting in response to IRS correspondence. For line 4, the instructions ask for detailed allocation schedules when filing status or spouses differ between years.
Start with the earliest carryback year. The instructions' example for a 2025 farming NOL carried back 2 years fills in 2nd preceding tax year ended 12/31/2023 in the first pair and 1st preceding tax year ended 12/31/2024 in the next.
Enter amounts as shown on the original or amended return in Before carryback. In After carryback, refigure AGI and the items based on AGI, then deductions and tax. The instructions say not to refigure the charitable contributions deduction.
Refigure the general business credit with Form 3800 and net investment income tax with Form 8960. The instructions say not to adjust self-employment tax or Additional Medicare Tax because of a carryback. Line 32 is line 30 minus line 31.
Enter any section 1341(b)(1) overpayment and attach the computation. Fill in direct deposit details for any refund. Sign and date; if filed jointly, both spouses sign.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say generally within 1 year after the end of the year in which the NOL, unused credit, net section 1256 contracts loss or claim of right adjustment arose, and not before the 2025 income tax return is filed. Filers affected by a federally declared disaster may have additional time.
A paper Form 1045 goes to the IRS service center for the place where you live, as shown in the instructions for the 2025 income tax return, in a separate envelope from that return. For e-filing, see Form 8453-TR.
Copies of the loss year return pages and schedules, Schedules K-1, K-2 and K-3 that contribute to the carryback, Forms 8886, and the forms refigured for the carryback years. The instructions say missing attachments may delay or disallow the application.
The IRS will process the application within 90 days from the later of the date the complete application is filed or the last day of the month that includes the due date, with extensions, of the 2025 return.
The instructions say a disallowed application can't be challenged in court, but a regular claim for credit or refund can still be filed before the limitation period expires.
The instructions say the IRS is phasing out paper refund checks under Executive Order 14247, and that filers with access to U.S. banking services should use direct deposit.
172
109 fields, 3 pages
1040-X
166 fields, 2 pages
1041
173 fields, 3 pages
8453-TR
36 fields, 2 pages
6781
71 fields, 4 pages
3800
1,921 fields, 9 pages
The form says it is for individuals, estates or trusts. The taxpayer, or the executors, administrators or fiduciary for an estate or trust, sign it and send it to the IRS. A paid preparer, if any, completes the Paid Preparer Use Only section.
No tool matches that search.
The instructions say individuals can claim a refund on Form 1040-X instead of Form 1045. Form 1040-X is used to carry back items to a section 965 year or to carry back released foreign tax credits or general business credits.
The instructions say within 90 days from the later of the date the complete application is filed or the last day of the month that includes the return's due date, including extensions.
No. The instructions say not to include Form 1045 in the same envelope as the 2025 income tax return, and not to file it before that return.
The instructions point to Form 8453-TR, E-file Declaration or Authorization for Form 1045/1139, for e-filing the application.
The instructions say that generally only an NOL from some farming losses and an NOL of some insurance companies can be carried back 2 years. The Instructions for Form 172 have the details.
No. The instructions say processing and paying the refund doesn't mean the IRS has accepted the application as correct, and excessive amounts may be assessed later.
All executors or administrators sign for an estate. The fiduciary or an authorized representative signs for a trust.