Header
The calendar or other tax year, the name shown on the return, the social security or employer identification number, the spouse's SSN, the address, a daytime phone number and foreign address spaces.
172
Net Operating Losses (NOLs)
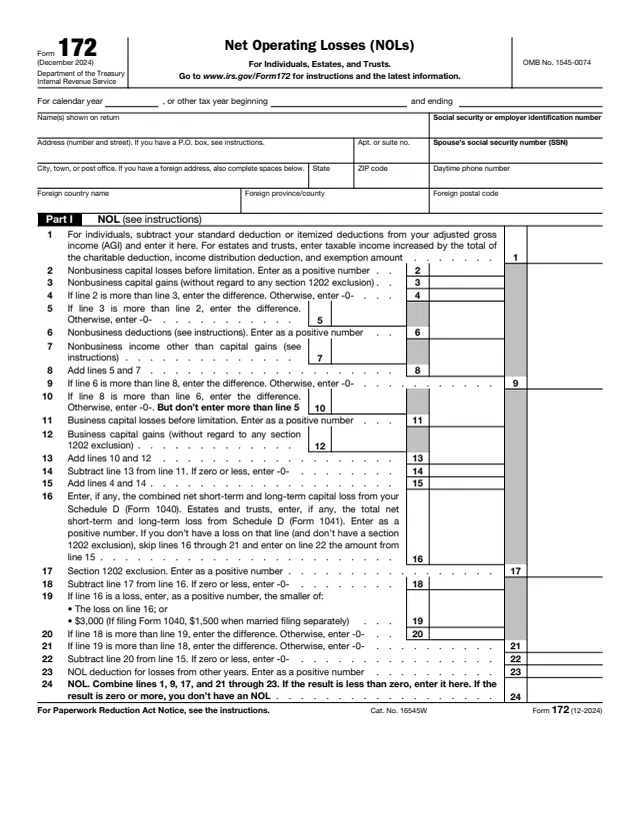
Form 172, Net Operating Losses (NOLs), is the IRS form individuals, estates and trusts use to figure the amount of a net operating loss (NOL) that is available for carrying back or forward. The IRS says that if your deductions for the year are more than your income for the year, you may have an NOL. The instructions say the form was created for taxpayers other than corporations, and that a loss from operating a business is the most common reason for an NOL.
Part I figures the NOL for the year. Part II figures the NOL carryover: how much of the loss is used up in another year and how much carries on to the next one. The instructions describe attaching Form 172, when it applies, to Form 1045, Form 1040-X, Form 1040 or Form 1041.
This page has the December 2024 edition. You can fill out the PDF free in your browser on this page and download it without an account.
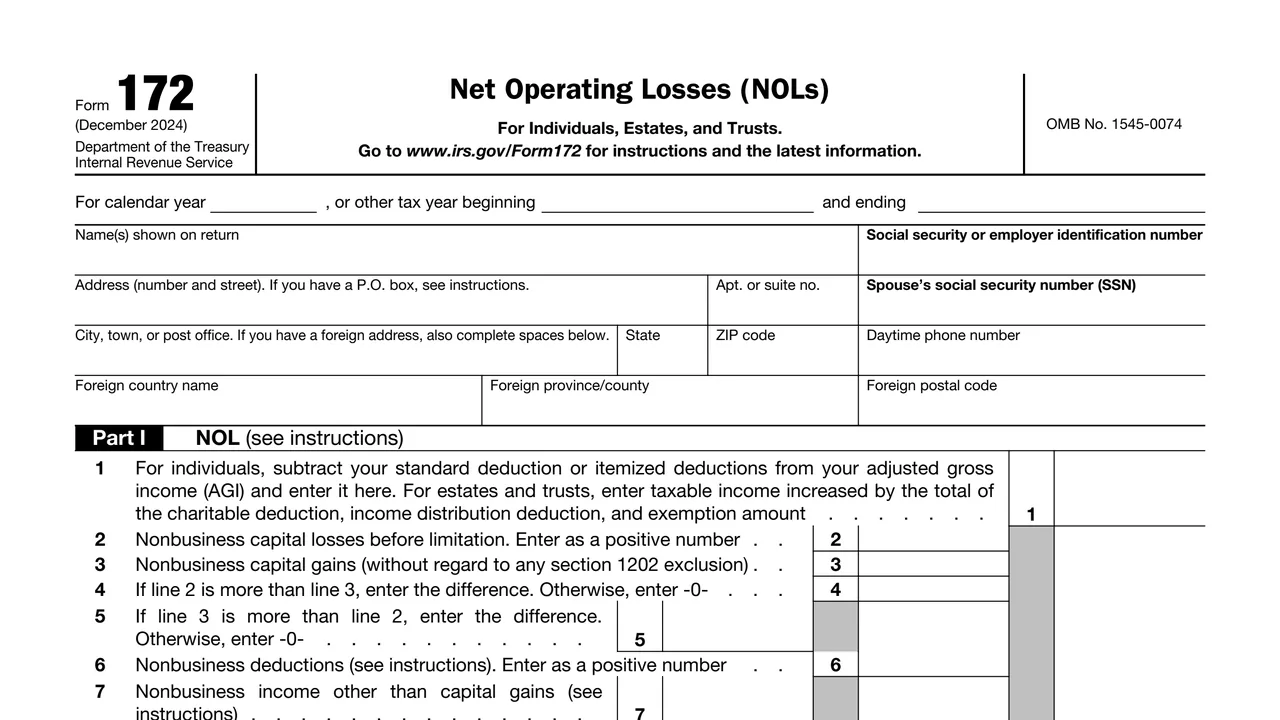
The calendar or other tax year, the name shown on the return, the social security or employer identification number, the spouse's SSN, the address, a daytime phone number and foreign address spaces.
The starting amount on line 1, then nonbusiness capital losses and gains, nonbusiness deductions and nonbusiness income other than capital gains.
Business capital losses and gains, the Schedule D loss, the section 1202 exclusion and a limit the form prints as $3,000 (If filing Form 1040, $1,500 when married filing separately).
Line 23 holds any NOL deduction for losses from other years. Line 24 combines lines 1, 9, 17 and 21 through 23. The form says a result of zero or more means there is no NOL.
Columns for the 2nd and 1st preceding tax years. Each column figures modified taxable income on line 9 and the NOL carryover to the subsequent year on line 10.
Individuals only. These lines refigure medical expenses at 7.5% of modified AGI, mortgage insurance premiums, charitable contributions and casualty and theft losses at 10%.
Above the name, enter the calendar year, or the beginning and ending months of a fiscal year. The instructions say to enter a P.O. box only if the post office doesn't deliver mail to the home, and not to abbreviate a foreign country name.
Individuals subtract the standard deduction or itemized deductions from AGI. Estates and trusts enter taxable income increased by the charitable deduction, income distribution deduction and exemption amount.
Line 6 holds nonbusiness deductions such as IRA, HSA and alimony deductions, most itemized deductions and the standard deduction. Line 7 holds nonbusiness income such as dividends, investment interest, pensions and social security benefits. The instructions treat wages as business income.
Enter the net capital loss from Schedule D (Form 1040) or Schedule D (Form 1041) as a positive number, and any section 1202 exclusion on line 17. With no loss there and no exclusion, the form says to skip lines 16 through 21 and enter line 15 on line 22.
Enter the total NOL deduction for losses from other years on line 23, then combine lines 1, 9, 17 and 21 through 23 on line 24. A result below zero is the NOL.
Complete one column before the next, starting with the earliest carryback year, and enter the date each carryback year ended. The form says to complete lines 11 through 33 only for years with itemized deductions when line 3, 4 or 5 is more than zero.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 172, if it applies, to Form 1045 or Form 1040-X for a carryback, or to Form 1040 or Form 1041 for a carryforward, with a Form 172 for each NOL.
The instructions say Form 1045 is generally filed on or after the date the NOL year return is filed, but not later than 1 year after the end of the NOL year.
Generally filed for the carryback year within 3 years after the due date, including extensions, of the NOL year return. A separate Form 1040-X is used for each carryback year.
Individuals list the NOL deduction as a negative figure on Schedule 1 (Form 1040). Estates and trusts include it on Form 1041. A statement showing the 80% limitation is attached when it applies.
The choice is made with a statement attached to the original return filed by the due date, including extensions. The instructions say it is generally irrevocable.
The instructions say to keep records for a tax year that generates an NOL for 3 years after the carryback or carryforward is used, or 3 years after the carryforward expires.
1045
193 fields, 2 pages
1040-X
166 fields, 2 pages
1040
73 fields, 2 pages
1041
173 fields, 3 pages
461
18 fields, 1 page

1040
199 fields, 2 pages
The instructions say individuals, estates, and trusts use Form 172 to figure the amount of the NOL that is available for carrying back or forward.
No tool matches that search.
The IRS says that if your deductions for the year are more than your income for the year, you may have an NOL. The instructions say a loss from operating a business is the most common reason.
No. The instructions say the form was created for taxpayers other than corporations. It is for individuals, estates and trusts.
The instructions say NOLs arising in tax years after 2020 can generally only be carried to a later year. Certain farming losses may be carried back 2 years.
For NOLs arising after 2017 and carried to a year after 2020, the instructions say the deduction can't exceed 80% of taxable income figured without the NOL deduction or sections 199A or 250.
The instructions describe attaching it, when it applies, to Form 1045, Form 1040-X, Form 1040 or Form 1041.
The instructions say an excess business loss figured on Form 461 is treated as an NOL carried forward, and they include a worksheet that combines it with the Form 172 result.