Header and line A
The name or names shown on the return, the identifying number, and the IRS-issued registration number for anyone making a transfer election.
8864
Biodiesel, Renewable Diesel, or Sustainable Aviation Fuels Credit
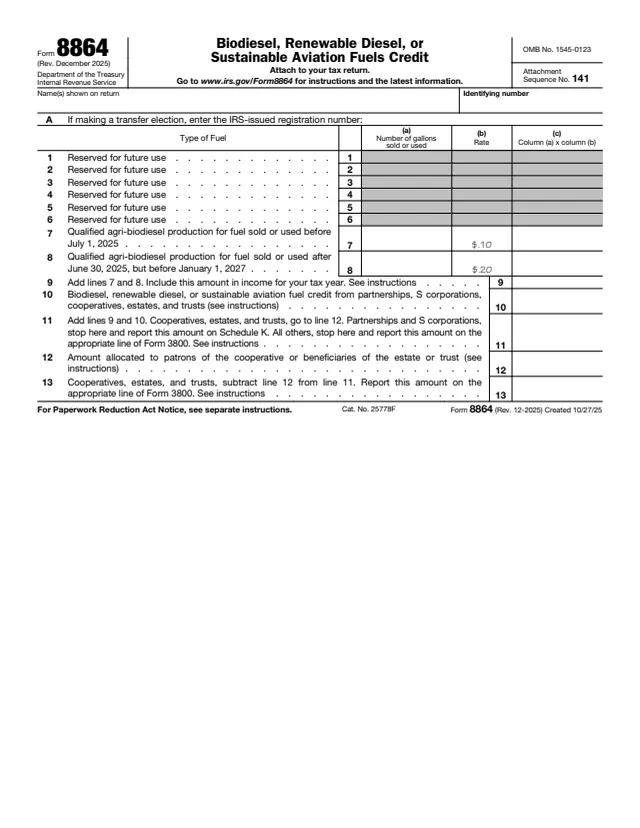
Form 8864 is titled Biodiesel, Renewable Diesel, or Sustainable Aviation Fuels Credit. The December 2025 instructions say to use it to claim the section 40A small agri-biodiesel producer credit, for the tax year in which the sale or use occurs.
The instructions also say the biodiesel credit, biodiesel mixture credit and renewable diesel credit under section 40A, and the section 40B sustainable aviation fuels credit, expired for fuel sold or used after December 31, 2024. On this revision, lines 1 through 6 read "Reserved for future use." The December 2025 form is still used to report those credits received from a fiscal-year partnership, S corporation, cooperative, estate or trust whose tax year began in 2024.
The form is attached to the filer's tax return. You can fill out Form 8864 free in your browser on this page and download the result without an account.
The name or names shown on the return, the identifying number, and the IRS-issued registration number for anyone making a transfer election.
All six lines are marked "Reserved for future use" on the December 2025 revision.
Gallons sold or used, the rate and the result: $.10 for fuel sold or used before July 1, 2025, and $.20 for fuel sold or used after June 30, 2025, but before January 1, 2027.
The total of lines 7 and 8, credit from partnerships, S corporations, cooperatives, estates and trusts, and the combined total.
For cooperatives, estates and trusts: the amount allocated to patrons or beneficiaries, and the remainder reported on Form 3800.
If applicable, enter the pre-filing registration number received from the IRS. The instructions say pre-filing registration is completed before electing to transfer the credit.
Enter the gallons of qualified agri-biodiesel production in column (a) and multiply by the printed rate in column (b). The instructions say fuel sold or used after June 30, 2025, must be exclusively derived from feedstock produced or grown in the United States, Mexico, or Canada.
Add lines 7 and 8. The form says to include this amount in income. The instructions say it goes under other income even if the credit can't all be used, and is subtracted when figuring alternative minimum taxable income.
Use it only for credit allocated from a pass-through entity. The instructions say the entity tells the recipient the number of gallons and its productive capacity, because the 15 and 60 million gallon limits also apply at the partner or similar level.
Add lines 9 and 10. Partnerships and S corporations report it on Schedule K. Others report it on Form 3800, Part III, line 1l, with any SAF credit on line 1ff, the instructions say. Cooperatives, estates and trusts go on to line 12.
Enter the amount allocated to patrons or beneficiaries on line 12, then subtract it from line 11 on line 13 for Form 3800. The instructions say an allocating entity gives each patron or beneficiary a statement.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. The instructions say to claim the credit for the tax year in which the sale or use occurs.
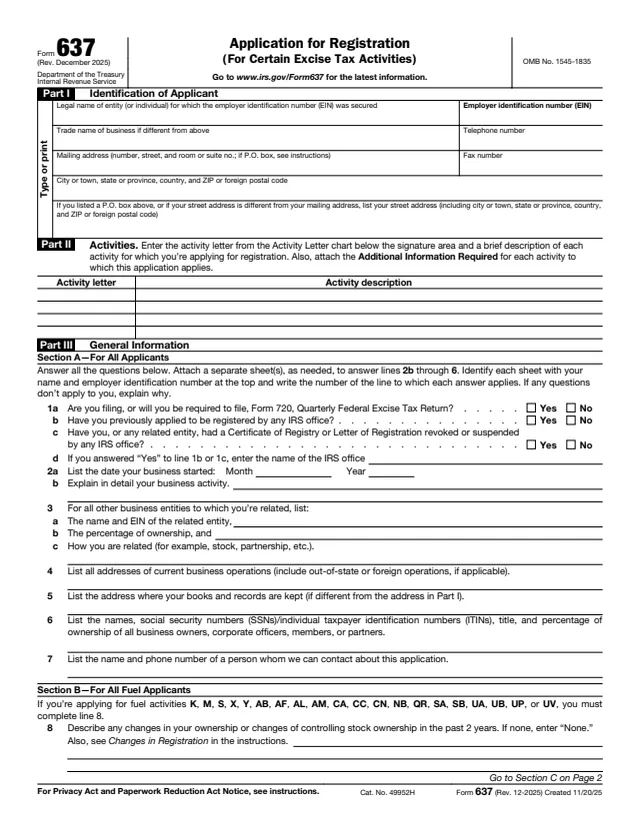
The instructions say all producers claiming the small agri-biodiesel producer credit must be registered with the IRS, and point to Form 637, Application for Registration.
The instructions say a section 6418 transfer election is allowed for fuel sold or used after June 30, 2025, and requires a pre-filing registration at IRS.gov/Register for Elective Payment or Transfer of Credits before the return is filed.
The instructions say tax is due on each gallon on which a credit was claimed if the fuel is used other than as a fuel, used to create a mixture after a retail purchase, separated from a mixture, or put to a nonqualified use. It is reported on Form 720, Part II, IRS No. 117.
The instructions say the small agri-biodiesel producer credit is extended through December 31, 2026, and is not claimed for fuel sold or used after 2026.

3800
1,921 fields, 9 pages
637
50 fields, 7 pages
720
715 fields, 8 pages
4136
485 fields, 4 pages
8849
27 fields, 4 pages
8582-CR
52 fields, 2 pages
The instructions describe a business credit form, used by fuel producers and by pass-through entities that claim or allocate the credit.
No tool matches that search.
The instructions say to use it to claim the section 40A small agri-biodiesel producer credit. Lines 1 through 6 are reserved on the December 2025 revision.
The instructions say the biodiesel, biodiesel mixture and renewable diesel credits, and the section 40B sustainable aviation fuels credit, expired for fuel sold or used after December 31, 2024.
The form prints $.10 per gallon for fuel sold or used before July 1, 2025, and $.20 for fuel sold or used after June 30, 2025, but before January 1, 2027.
The instructions say taxpayers whose only source for the credit is a partnership, S corporation, cooperative, estate or trust are not required to file it, and can report the credit directly on Form 3800.
Yes. The form says to include the line 9 amount in income, and the instructions say it is subtracted when figuring alternative minimum taxable income.
The instructions say eligible taxpayers, partnerships and S corporations can elect under section 6418 to transfer all or part of the credit to an unrelated third party for cash, after completing a pre-filing registration.