Section I: Applicability
Whether the plan is a governmental plan under 414(d), whether the employer is a church or QCCO, and whether the plan provides employer contributions other than matching contributions.
15417-C
403(b) Plan Coverage and Nondiscrimination Requirements for Employer Contributions (Other than Matching Contributions) Worksheet 5B – Determination of 403(b) Status
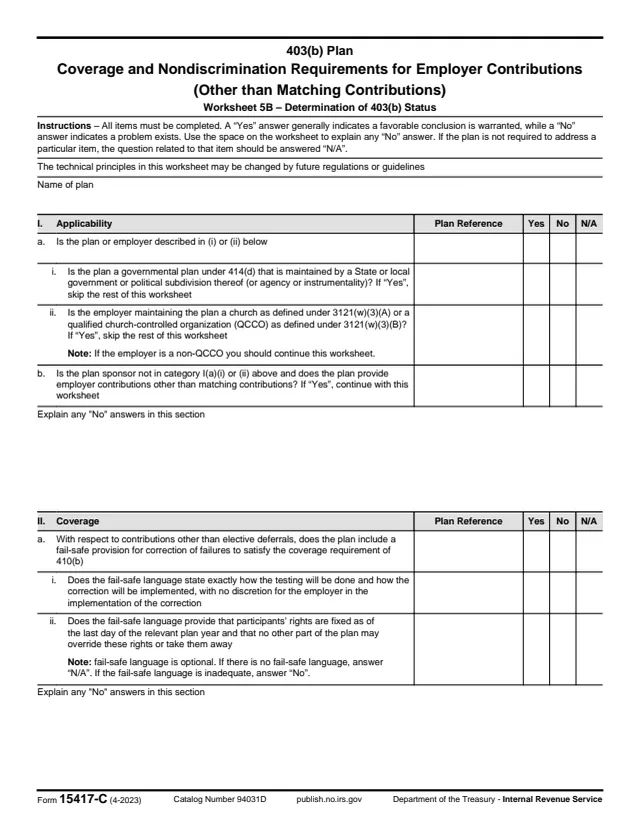
Form 15417-C (4-2023) is an IRS worksheet titled 403(b) Plan Coverage and Nondiscrimination Requirements for Employer Contributions (Other than Matching Contributions). Its title also calls it Worksheet 5B, Determination of 403(b) Status. It goes through a named 403(b) plan question by question, with a Plan Reference column and Yes, No and N/A boxes on every item.
The instructions printed at the top of page 1 say "All items must be completed." They explain that a "Yes" answer generally indicates a favorable conclusion is warranted, while a "No" answer indicates a problem exists, and each section has space to explain any "No" answer. An item the plan is not required to address is answered "N/A". The form also notes that its technical principles may be changed by future regulations or guidelines.
The worksheet does not say who fills it out or where it goes, and no separate instructions are linked to it. You can fill it out free in your browser on this page and download the result without an account.
Whether the plan is a governmental plan under 414(d), whether the employer is a church or QCCO, and whether the plan provides employer contributions other than matching contributions.
Whether the plan has a fail-safe provision for correcting failures of the 410(b) coverage requirement, how testing and correction are done, and whether participants' rights are fixed as of the last day of the plan year.
Section III points matching and after-tax contributions to Worksheet 11A. Section IV asks about the design-based uniform allocation safe harbor and five permitted disparity questions under 401(l).
Whether the plan's definition of compensation satisfies 414(s), both for computing contributions under a design-based safe harbor formula and for testing nondiscrimination.
Whether benefits, rights and features (BRFs) are available in a nondiscriminatory manner and are not conditioned on the participant making, or failing to make, elective deferrals.
Employer nonelective contributions for former participants: a nondiscriminatory basis, no cash option, includible compensation under 1.403(b)-4(d)(1), and the limit to the earlier of death or five years after the year employment ended.
Enter the name of the 403(b) plan in the box at the top of page 1.
Answer items I(a)(i), I(a)(ii) and I(b). The form says a "Yes" to I(a)(i) or I(a)(ii) means skipping the rest of the worksheet, and a "Yes" to I(b) means continuing.
Check one box for each item. Each row also has a Plan Reference column; the form gives no further directions for it. An item the plan is not required to address is answered "N/A".
Fail-safe language is optional: if there is none, answer "N/A", and if it is inadequate, answer "No". Item IV(b) is completed only for a permitted disparity formula. A "No" on VII(a) skips the remainder of the worksheet.
Each section ends with a space headed Explain any "No" answers in this section. The instructions at the top say to use that space for every "No".
Item VII(d) says to review the "Limitations" Worksheet 6A for rules imputing includable compensation, and Section III sends matching and after-tax contributions to Worksheet 11A.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The worksheet prints no mailing address, filing method, recipient or deadline, and it has no signature line.
The IRS listing gives only the PDF. The worksheet's directions are the short paragraph at the top of page 1 and the notes printed under some items.
Each page footer prints Form 15417-C (4-2023), Catalog Number 94031D, Department of the Treasury, Internal Revenue Service.
The title calls it Worksheet 5B in the Determination of 403(b) Status series. The IRS listing titles Form 15417-D as Worksheet 6A and Form 15417-F as Worksheet 11A, the two worksheets this form names.
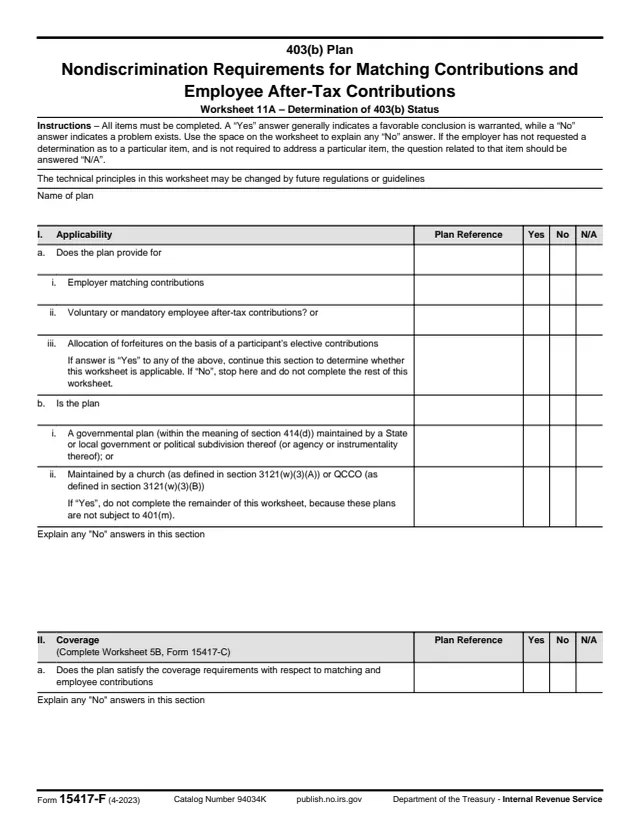
15417-F
286 fields, 6 pages
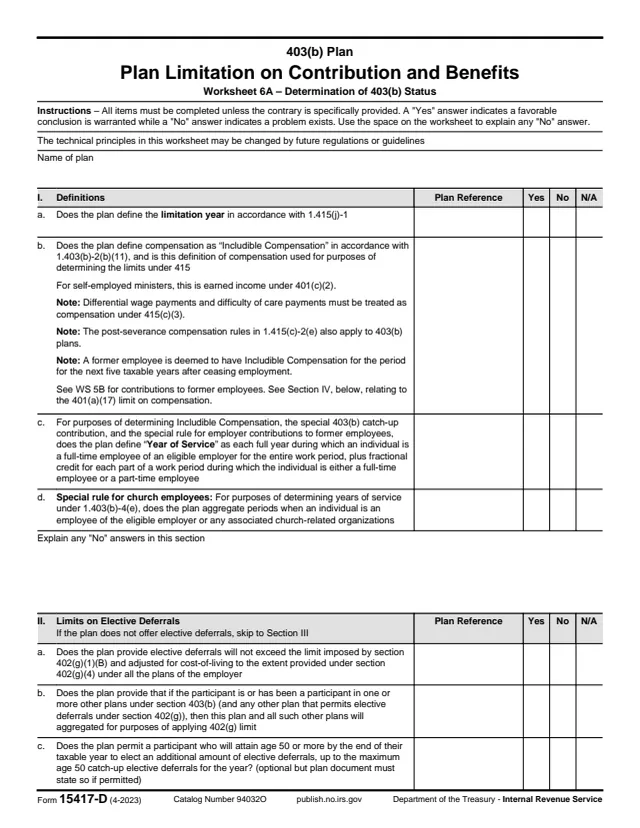
15417-D
105 fields, 3 pages
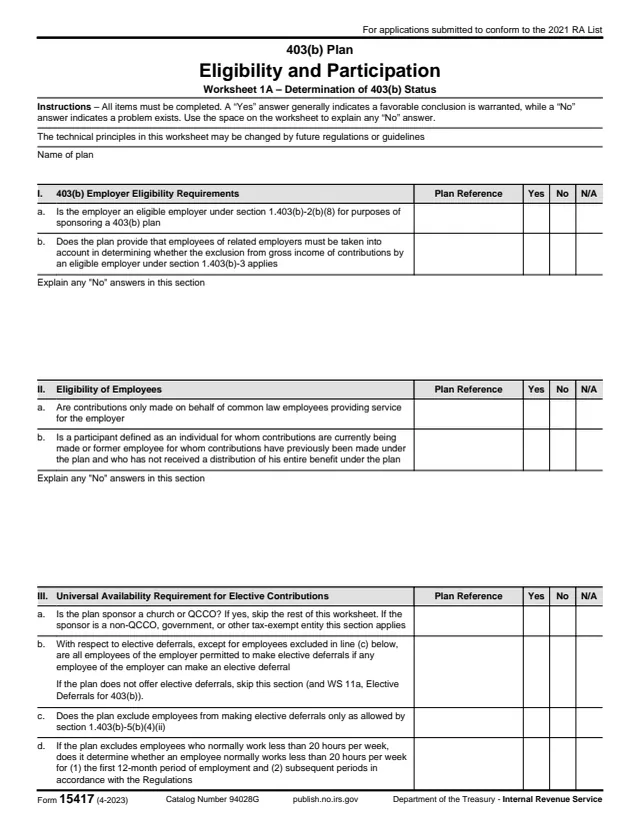
15417
81 fields, 2 pages
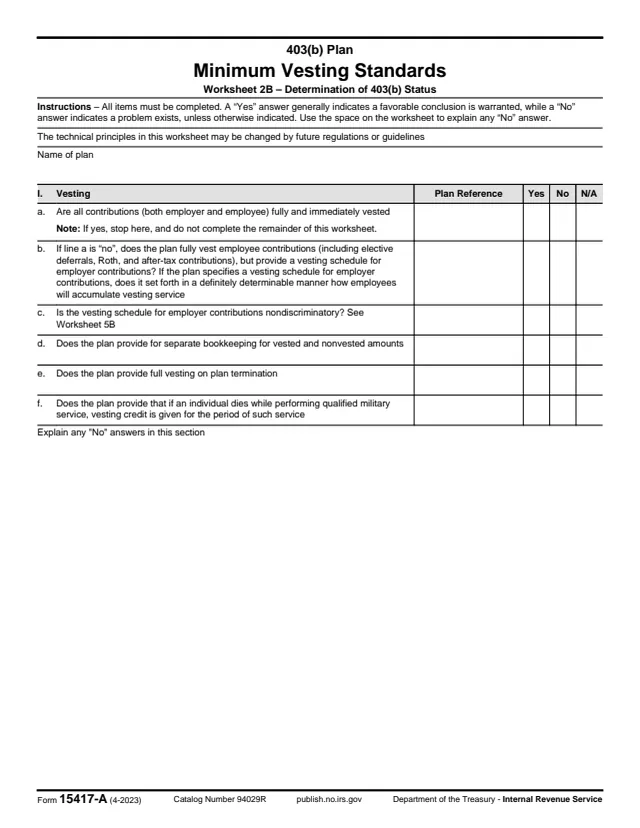
15417-A
26 fields, 1 page
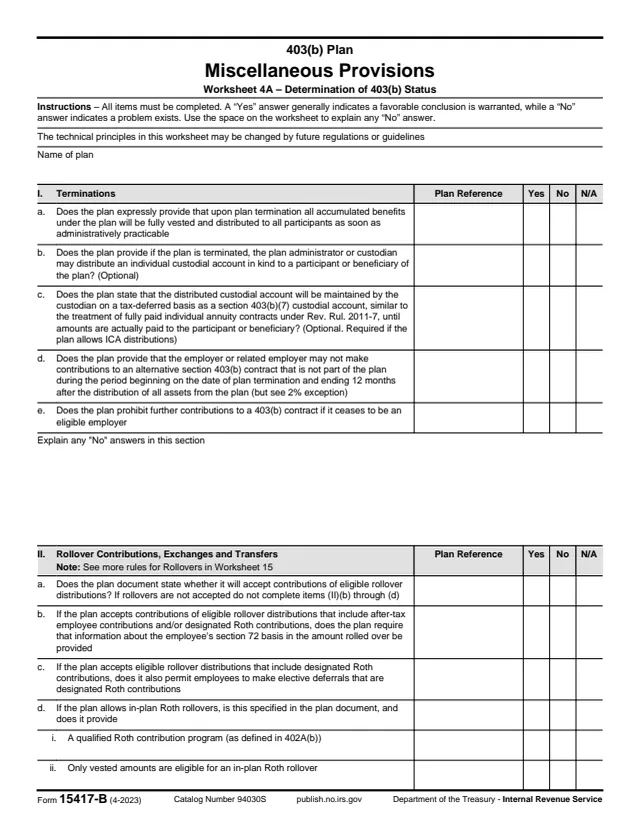
15417-B
133 fields, 3 pages
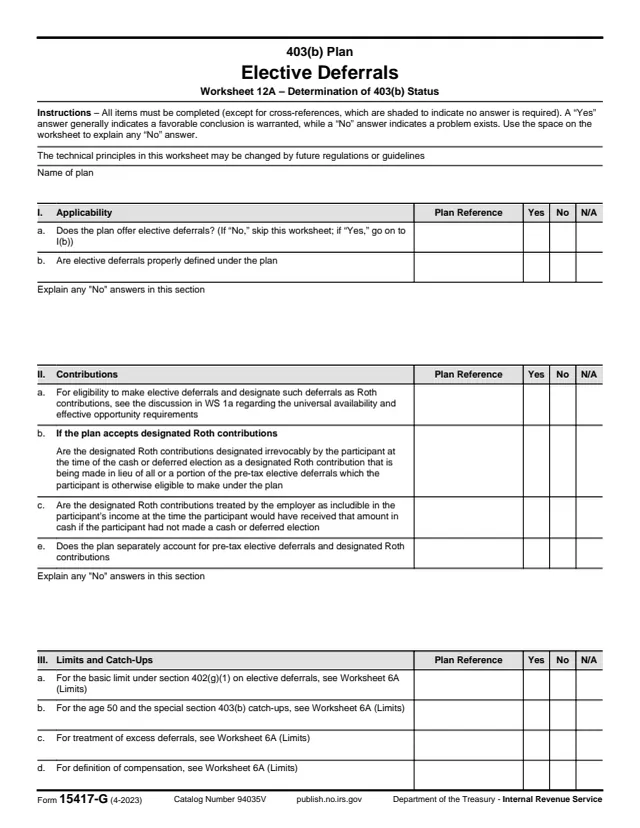
15417-G
88 fields, 2 pages
The worksheet does not name who completes it or who receives it. Its Section I decides which 403(b) plans the rest of the worksheet applies to.
No tool matches that search.
The worksheet does not say. It asks about the provisions of a named 403(b) plan and has no preparer, signature or recipient lines.
Section I says to skip the rest of the worksheet if the plan is a governmental plan under 414(d) maintained by a State or local government, or if the employer is a church or a qualified church-controlled organization.
The form says a "Yes" answer generally indicates a favorable conclusion is warranted, while a "No" answer indicates a problem exists. Each section has space to explain any "No" answer.
Section III says to complete Worksheet 11A with respect to matching or after-tax employee contributions.
The note in Section II says fail-safe language is optional. With no fail-safe language the answer is "N/A", and with inadequate language the answer is "No".
No separate instructions are linked to it. The directions are the paragraph at the top of page 1 and the notes under individual items.