Exemption type
Boxes for Individual Exemption or Blanket Exemption.
1363
Export Exemption Certificates
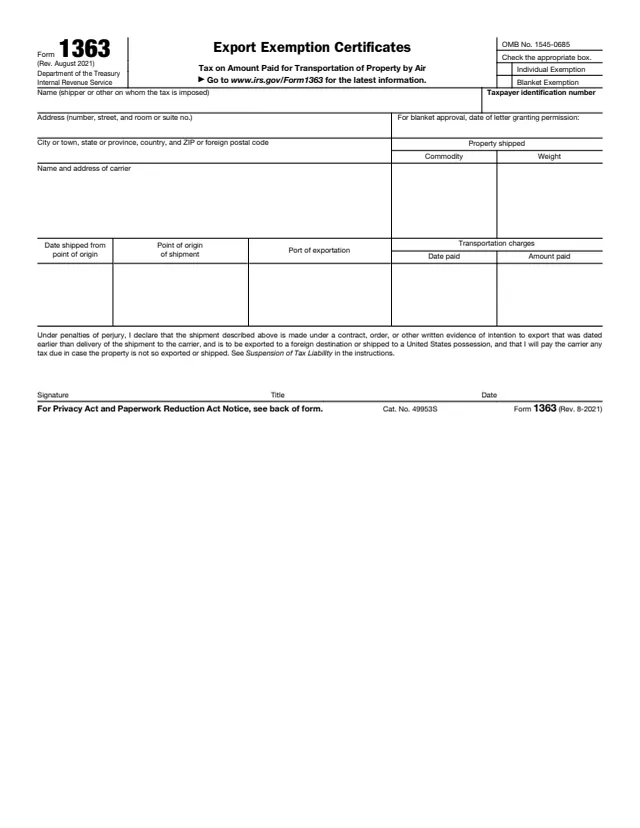
Form 1363 is an export exemption certificate for the tax on the amount paid for transportation of property by air. The IRS About page says: "File Form 1363 with the carrier to suspend the liability for the 6.25% tax on transportation of property by air."
The instructions on page 2 explain that the section 4271 tax applies when the transportation begins and ends in the United States, and that the amount paid is exempt when property is exported (including shipment to a U.S. possession) by continuous movement. One certificate can cover a single shipment (Individual Exemption) or, with IRS permission, many shipments (Blanket Exemption).
The shipper gives the original to the carrier and keeps a copy. The form says not to file it with the IRS office named in its paperwork notice. You can fill it out free in your browser on this page and download the result without an account.
Boxes for Individual Exemption or Blanket Exemption.
Name of the shipper or other person on whom the tax is imposed, taxpayer identification number and address.
For blanket approval, the date of the IRS letter granting permission.
Name and address of carrier, property shipped (commodity and weight), date shipped from point of origin, point of origin of shipment and port of exportation.
The date paid and amount paid for the transportation.
A statement under penalties of perjury about written evidence of intent to export and the promise to pay any tax due if the property is not exported, then signature, title and date.
Check Individual Exemption for a single shipment, or Blanket Exemption when the IRS has granted permission for one.
The instructions say to request it by letter to Department of the Treasury, Internal Revenue Service, Mail Stop 5701G, Cincinnati, OH 45999, then complete a separate certificate for each air carrier.
Enter the shipper's name, taxpayer identification number and address, the approval letter date for a blanket exemption, then the carrier's name and address.
Enter commodity and weight, the shipping date, point of origin, port of exportation and the transportation charges. The instructions say the description should be brief, and a general description is sufficient for a blanket exemption.
Sign with title and date, give the original to the carrier and keep a copy with the shipping papers. A blanket certificate goes to the carrier on or before payment of the first covered charge.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Give the original to the air carrier and keep a copy. The form says not to file it with the IRS Tax Products Coordinating Committee address printed in its paperwork notice.
The instructions say the certificate suspends liability for the tax for a period of 6 months starting from the date the property is shipped from point of origin.
The person liable for the tax furnishes proof to the carrier, such as a copy of the export bill of lading, a memorandum from the captain of the vessel, customs official or a foreign consignee, or a shipper's export declaration.
The carrier then collects the tax. If proof of exportation reaches the carrier after collection, the instructions say credit or refund may be obtained under section 6415(a).
The instructions say to keep a blanket certificate at least 3 years after the last day of the month of the final shipment it covers, and individual shipment records at least 3 years after the month of shipment.
The shipper or other person on whom the tax is imposed completes and signs it, and gives the original to the air carrier.
No tool matches that search.
The section 4271 6.25% tax on the amount paid for transportation of property by air, which the instructions say applies when the transportation begins and ends in the United States.
No. The form says to give the original to the carrier and keep a copy. A request for blanket exemption permission goes to the IRS by letter.
One Form 1363 used for numerous export shipments over an indefinite period, with IRS permission. The instructions say it remains in effect until withdrawn.
6 months starting from the date the property is shipped from point of origin, according to the instructions.
A copy of export bill of lading, a memorandum from the captain of the vessel, customs official, or a foreign consignee, and/or a shipper's export declaration. A statement that the documents are available may also be used.
The instructions say exemption certificates do not have to be numbered consecutively, but proof of exportation goes to the carrier along with Form 1363.