Issuer and recipient boxes
The issuer's or provider's name, address and telephone number, the issuer's TIN, and the recipient's TIN, name and address.
1099-H
Health Coverage Tax Credit (HCTC) Advance Payments
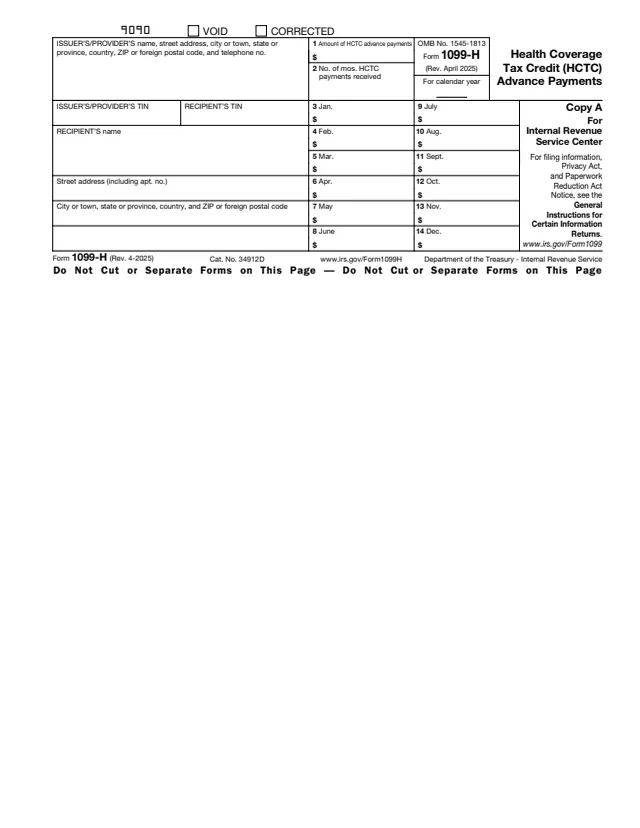
Form 1099-H, Health Coverage Tax Credit (HCTC) Advance Payments, is an information return. The IRS About page says to file it if any advance payments were received during the calendar year of qualified health insurance payments for the benefit of eligible trade adjustment assistance (TAA), Reemployment TAA, or Pension Benefit Guaranty Corporation (PBGC) pension recipients and their qualifying family members.
The instructions say providers of qualified health insurance coverage that receive HCTC advance payments from the Department of the Treasury file the form and furnish a statement to the recipient. Under Notice 2004-47, the IRS HCTC Program files the returns and furnishes the statements unless the provider elects to do it itself.
The form has Copy A for the IRS and Copy B for the recipient, with boxes for the yearly total, the number of months and the amount for each month. The instructions, also revised April 2025, say to use them for tax year 2025 and later years until a superseding revision is issued. You can fill it out free in your browser on this page and download it without an account.
The issuer's or provider's name, address and telephone number, the issuer's TIN, and the recipient's TIN, name and address.
The total HCTC advance payments of qualified health insurance costs made on the recipient's behalf during the year.
Copy A labels it the number of months HCTC payments received. Copy B labels it the number of months of HCTC advance payments and reimbursement credits paid to the recipient.
One box for each month from January through December. The recipient instructions say their total equals the amount in box 1.
Enter the provider's name, address, telephone number and TIN, then the recipient's TIN, name and address. The instructions allow the recipient's TIN to be truncated on recipient statements but not on documents filed with the IRS.
Enter the total advance payments of health insurance premiums received for the recipient from January 1 through December 31. The instructions say this cannot exceed 72.5% of the total health insurance premium for the individual.
Enter the number of months payments were received on behalf of the recipient. The instructions say this number cannot be more than 12.
Enter each month's advance payment in the box for that month. The instructions note that payments may arrive before the month they are for, and say to enter the amounts in the correct box.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
For filing with the IRS, the instructions point to part E in the current General Instructions for Certain Information Returns and to Pub. 1220.
The HCTC Program furnishes Copy B or an acceptable substitute statement to each recipient, unless the provider elects to furnish it.
The instructions say the IRS will not assert the penalties under sections 6721 and 6722 against a provider that allows the HCTC Program to file and furnish Forms 1099-H.
The instructions say expired ITINs may continue to be used for information return purposes.
8885
18 fields, 1 page
1096
55 fields, 3 pages

1040
199 fields, 2 pages
1040-NR
171 fields, 2 pages
1040-SS
132 fields, 3 pages
A health insurance provider, or the IRS HCTC Program on its behalf, files the form. The recipient gets Copy B.
No tool matches that search.
The provider of qualified health insurance coverage that received HCTC advance payments, or the IRS HCTC Program on the provider's behalf.
The recipient instructions say the statement is provided because the recipient received HCTC advance payments of health coverage insurance premiums, which were forwarded directly to the health insurance provider.
The recipient instructions point to Form 8885, Health Coverage Tax Credit, and its instructions for qualified recipients and how to figure any credit on Form 1040, 1040-SR, 1040-NR, 1040-SS, or 1040-PR.
The instructions say the number cannot be more than 12.
The recipient instructions say the total of the amounts in boxes 3 through 14 equals the amount in box 1.
The April 2025 revision. Its instructions, also revised April 2025, say to use them for tax year 2025 and later years until a superseding revision is issued.