Owner details
Name of owner, U.S. taxpayer identification number, permanent address, expatriation date, and a current mailing address if different.
W-8CE
Notice of Expatriation and Waiver of Treaty Benefits
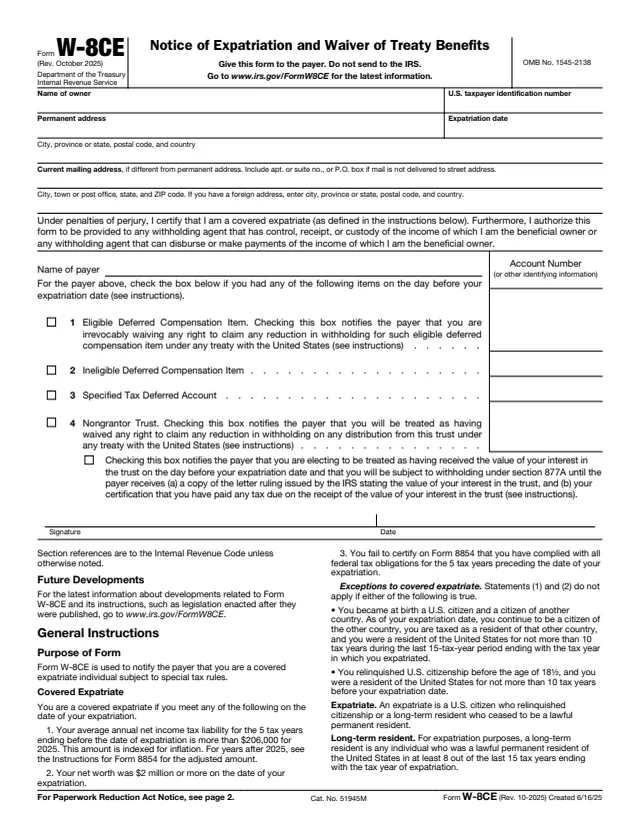
Form W-8CE is the Notice of Expatriation and Waiver of Treaty Benefits. The form says it is used to notify the payer that you are a covered expatriate individual subject to special tax rules.
A covered expatriate gives it to each payer of certain items held on the day before the expatriation date: an eligible or ineligible deferred compensation item, a specified tax deferred account, or an interest in a nongrantor trust. The owner certifies under penalties of perjury that they are a covered expatriate, and the payer may then have to withhold tax under section 877A or report information to the IRS. The form says "Give this form to the payer. Do not send to the IRS."
This is the October 2025 revision. You can fill out Form W-8CE free in your browser on this page and download it without an account.
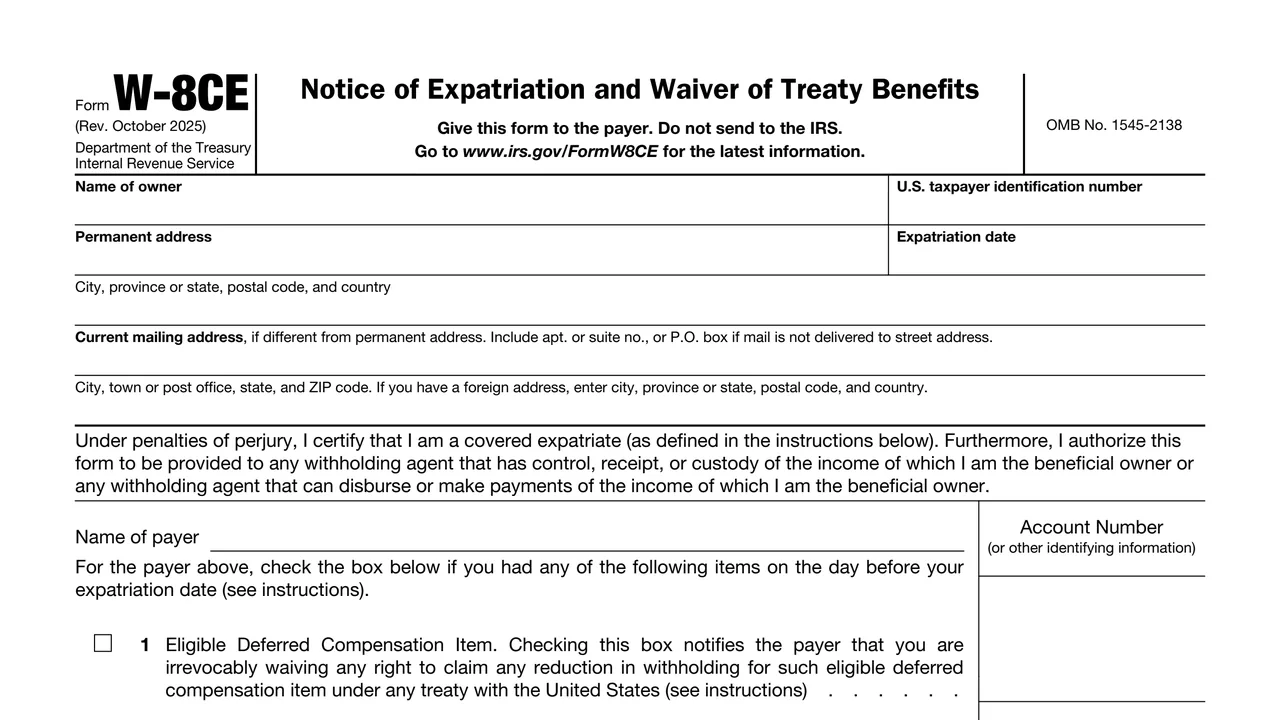
Name of owner, U.S. taxpayer identification number, permanent address, expatriation date, and a current mailing address if different.
A statement under penalties of perjury that you are a covered expatriate, authorizing the form to be given to any withholding agent of your income.
Name of payer and the account number or other identifying information for the items listed below.
Eligible deferred compensation item, ineligible deferred compensation item, and specified tax deferred account.
Nongrantor trust, with a second box to elect to be treated as having received the value of your trust interest on the day before expatriation.
The owner's signature and the date.
Enter your name, U.S. TIN, addresses and expatriation date: the date you relinquished U.S. citizenship or ceased to be a lawful permanent U.S. resident.
Enter the payer's name and the account number or other identifying information. Each payer gets its own form.
Box 1 is for an eligible deferred compensation item, which the instructions say meets three conditions, including an irrevocable treaty waiver on Form 8854. Box 2 is for an item that does not.
Check it for a specified tax deferred account. The instructions list individual retirement plans (other than section 408(k) or (p) arrangements), 529 and 529A programs, Coverdell ESAs, HSAs and Archer MSAs.
Check box 4 if you were a beneficiary of a nongrantor trust the day before expatriation. The election box below it is made on Form 8854 with an IRS valuation letter ruling attached.
Sign and date, give the form to the payer, and keep a copy for your own records.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to give Form W-8CE to each payer of the income and keep a copy for your own records. It is not sent to the IRS.
The instructions say on the earlier of (a) the day before the first distribution on or after the expatriation date, or (b) thirty (30) days after the expatriation date, for each account, deferred compensation item or trust interest.
The instructions say "all expatriates must file Form 8854 with the Internal Revenue Service."
For an eligible deferred compensation item, the payer instructions say to withhold 30% on any taxable payment to the covered expatriate.
For an ineligible deferred compensation item or a specified tax deferred account, the payer advises the covered expatriate within 60 days of receipt of the form of the value on the day before expatriation.
The instructions say the election is not valid unless your income tax return is filed by the due date, including extensions, with Form 8854 attached to Form 1040 or Form 1040-NR.
8854
208 fields, 5 pages
W-8
23 fields, 1 page
W-8
36 fields, 1 page
W-8EXP
67 fields, 3 pages
W-8
148 fields, 8 pages
1040-NR
171 fields, 2 pages
The instructions say covered expatriates give Form W-8CE to the payer if they had any of the items in boxes 1 through 4 on the day before their expatriation date. The payer receives it.
No tool matches that search.
No. The form says to give it to the payer and not send it to the IRS.
Each payer of an eligible or ineligible deferred compensation item, a specified tax deferred account, or a distribution from a nongrantor trust.
The instructions say on the earlier of the day before the first distribution on or after the expatriation date, or thirty (30) days after the expatriation date.
The form says it notifies the payer that you are irrevocably waiving any right to claim any reduction in withholding on that item under any treaty with the United States.
The instructions say it is the date you relinquished U.S. citizenship or the date on which you ceased to be a lawful permanent U.S. resident.
No. The instructions say all expatriates file Form 8854 with the IRS. Form W-8CE goes to payers.