Step 1: Personal Information
Name, social security number, address, and three filing status boxes: single or married filing separately, married filing jointly or qualifying surviving spouse, and head of household.
W-4P
Withholding Certificate for Periodic Pension or Annuity Payments
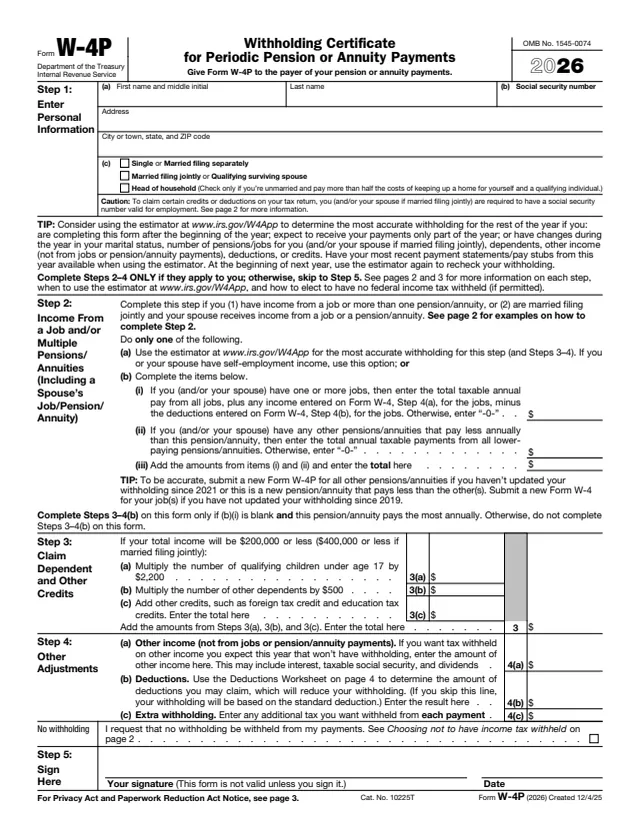
Form W-4P is the certificate a person who receives periodic pension or annuity payments gives to the payer so the payer can withhold the correct amount of federal income tax. The About page says it covers periodic pension, annuity (including commercial annuities), profit-sharing and stock bonus plan, and individual retirement arrangement (IRA) payments. The form defines periodic payments as installments made at regular intervals, for example annually, quarterly or monthly, over a period of more than 1 year.
The form says "Give Form W-4P to the payer of your pension or annuity payments." It is not for a nonperiodic payment or an eligible rollover distribution, including a lump-sum pension payment: the form points those to Form W-4R. It also says not to use Form W-4P for payments to nonresident aliens and foreign estates.
This is the 2026 edition. Its instructions are on pages 2 and 3, and page 4 holds the Step 4(b) Deductions Worksheet. You can fill out the PDF free in your browser on this page and download it without an account.
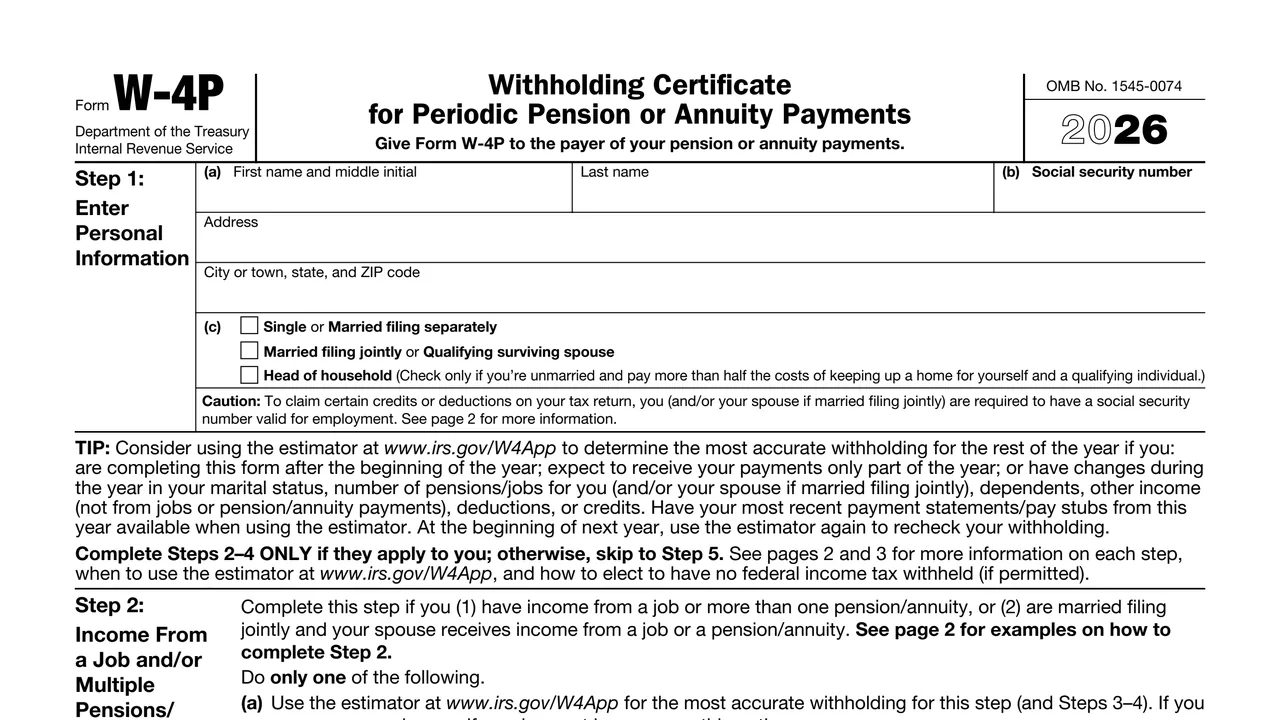
Name, social security number, address, and three filing status boxes: single or married filing separately, married filing jointly or qualifying surviving spouse, and head of household.
Two options: the estimator at www.irs.gov/W4App, or items (i) to (iii) for job pay and lower-paying pensions or annuities.
For total income of $200,000 or less ($400,000 or less if married filing jointly): qualifying children under age 17 times $2,200, other dependents times $500, and other credits.
4(a) other income not from jobs or pensions, 4(b) deductions from the worksheet, and 4(c) extra withholding from each payment.
A box to request that no withholding be withheld, then the signature and date. The form says it is not valid unless signed.
Page 4 has 17 lines covering qualified tips, overtime, passenger vehicle loan interest, seniors age 65 or older, adjustments, itemized deductions and the standard deduction. The total goes to Step 4(b).
Enter your name, social security number and address, and check your anticipated filing status. The instructions say this determines the standard deduction and tax rates used to compute withholding.
Do only one option. Use the estimator, which the form says to use if you or your spouse have self-employment income, or fill in items (i) to (iii). In the form's example, a single filer with a $50,000 pension and a $25,000 job enters $25,000 in Step 2(b)(i) and 2(b)(iii).
The form says to complete Steps 3 to 4(b) on this form only if Step 2(b)(i) is blank and this pension or annuity pays the most annually. With a job, those steps go on the Form W-4 for the job.
Multiply the number of qualifying children under age 17 by $2,200 and other dependents by $500, then add other credits such as the foreign tax credit and education tax credits.
Enter other income such as interest, taxable social security and dividends on 4(a), the Deductions Worksheet line 17 amount on 4(b), and any extra tax per payment on 4(c). The form says skipping 4(b) bases withholding on the standard deduction.
Sign and date. To elect no federal income tax withholding, the instructions say to check the No withholding box and complete only Steps 1(a), 1(b) and 5.
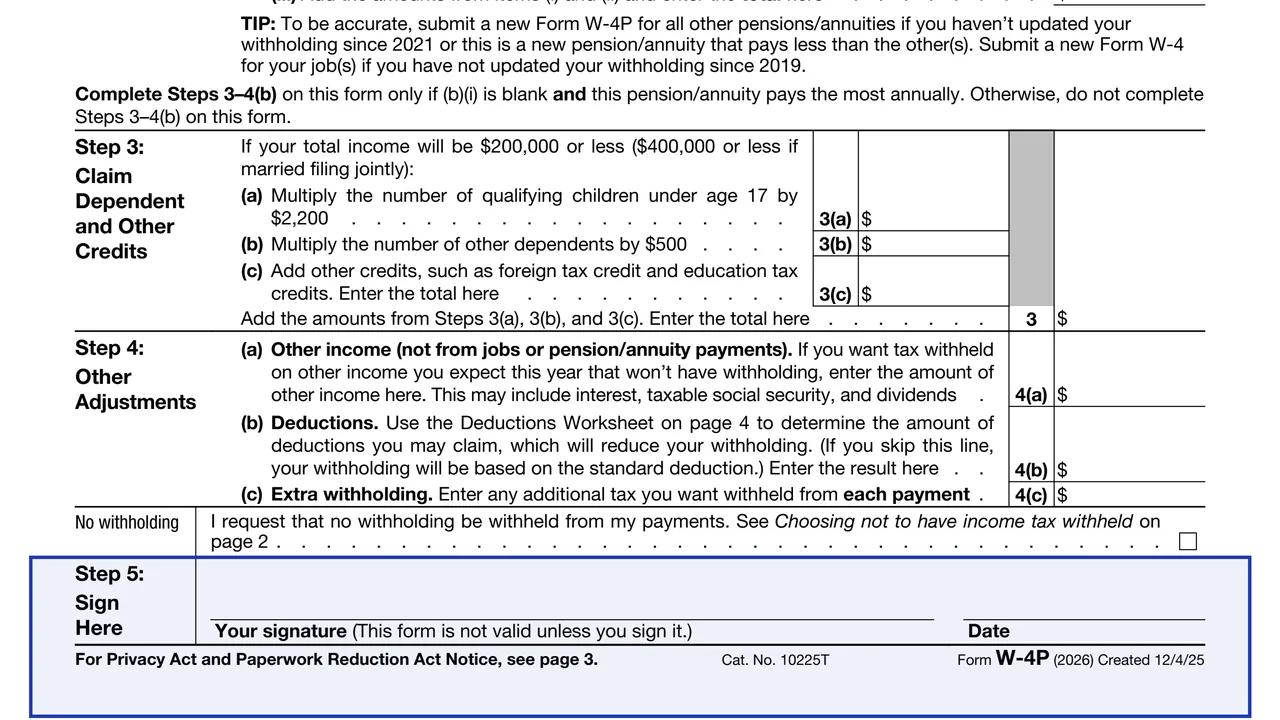
The form says to complete Steps 2 to 4 only if they apply, and otherwise to skip to Step 5.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Give Form W-4P to the payer of your pension or annuity payments." A separate Form W-4P goes to each payer of a pension, annuity or other periodic payment.
The form says that if no Form W-4P is given, no SSN is provided, or the IRS reports an incorrect SSN, the payer withholds as if the filing status is single with no adjustments in Steps 2 through 4.
The form says the current withholding election, or the default rate, remains in effect unless a new Form W-4P is submitted.
The form says to submit a new Form W-4P if the tax situation changes, or to start withholding after choosing none. It suggests the estimator at www.irs.gov/W4App for changes during the year.
The form says too little withholding generally means tax owed at filing and possibly a penalty unless timely estimated tax payments are made. It points to Form 1040-ES for estimated tax.
Page 4 is marked "Keep for your records." Only its line 17 total is entered on the form, in Step 4(b).
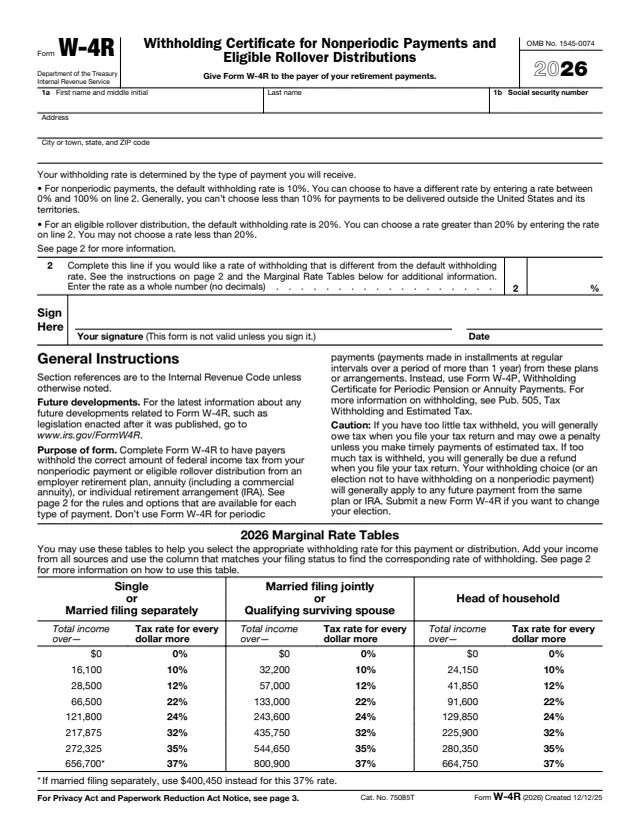
W-4R
6 fields, 3 pages
W-4
48 fields, 5 pages
1040-ES
118 fields, 16 pages
1040
54 fields, 2 pages
1040
33 fields, 1 page
1040
73 fields, 2 pages
The person who receives the periodic payments fills it out and gives it to the payer. The form says to submit a separate Form W-4P for each pension, annuity or other periodic payment.
No tool matches that search.
The form says to give it to the payer of your pension or annuity payments. The form gives no IRS mailing address.
The form says you can check the No withholding box and complete Steps 1(a), 1(b) and 5. It also says U.S. citizens and resident aliens generally cannot elect this for payments delivered outside the United States and its territories.
The form says to submit a separate Form W-4P for each one. With no job, Steps 3 to 4(b) go only on the form for the pension or annuity that pays the most annually, and are left blank on the others.
No. The form says to use Form W-4R for nonperiodic payments and eligible rollover distributions, including a lump-sum pension payment.
The form says the payer withholds as if your filing status is single with no adjustments in Steps 2 through 4. For payments that began before 2026, the current election or default rate stays in effect.
On the Step 4(b) Deductions Worksheet on page 4, lines 1a to 3b. The worksheet total on line 17 goes in Step 4(b). The form points to the Instructions for Schedule 1-A (Form 1040) for who qualifies.