Items 1 to 6: loan and borrowers
VA loan number, the lender's loan number and VA identification number, date of report, the Veteran's name, Social Security number and present address, and any co-obligor's name and Social Security number.
26-1820
Report and Certification of Loan Disbursement
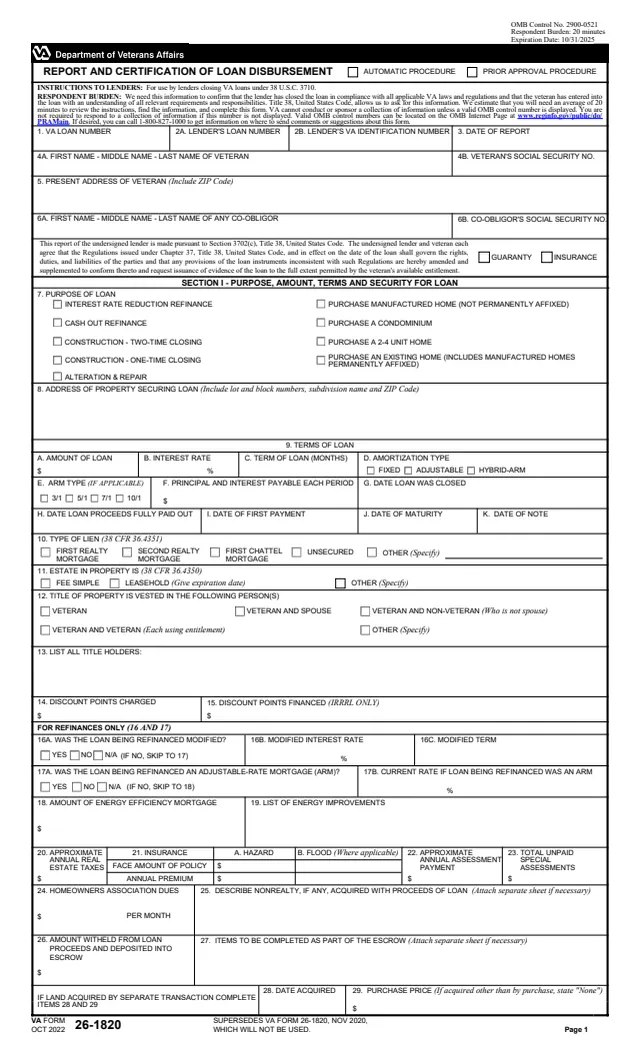
VA Form 26-1820 is the U.S. Department of Veterans Affairs Report and Certification of Loan Disbursement. Its instructions to lenders say it is for use by lenders closing VA loans under 38 U.S.C. 3710. The respondent burden note says VA needs the information to confirm that the lender closed the loan in compliance with all applicable VA laws and regulations and that the Veteran entered into the loan with an understanding of all relevant requirements and responsibilities.
The form is three pages. Section I gives the purpose, amount, terms and security for the loan. Section II is the lender's certification, signed by a lender representative. Section III holds the Veteran's certifications, which the form says are executed by the Veteran on the date the loan is closed, plus voluntary information for government monitoring purposes. Boxes at the top mark the automatic or prior approval procedure, and guaranty or insurance.
You can fill out the PDF free in your browser on this page and download the result without an account.
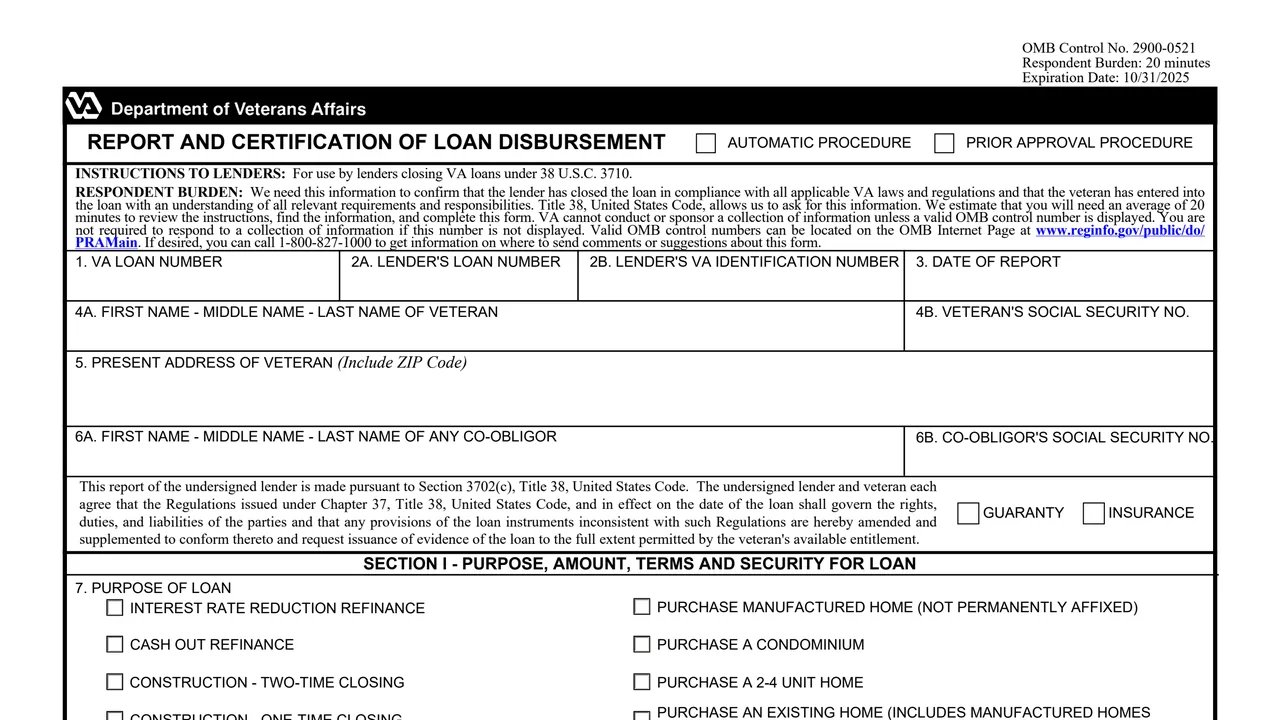
VA loan number, the lender's loan number and VA identification number, date of report, the Veteran's name, Social Security number and present address, and any co-obligor's name and Social Security number.
Purpose of the loan, from refinances and construction to purchases, the property address, the loan terms and key dates, the type of lien, the estate in property and who holds title.
Discount points charged and financed (IRRRL only), questions for refinances on modified loans and adjustable-rate mortgages, and any energy efficiency mortgage amount with its list of improvements.
Approximate annual real estate taxes, hazard and flood insurance, special assessments, homeowners association dues, nonrealty bought with loan proceeds, escrow deposits and land acquired by separate transaction.
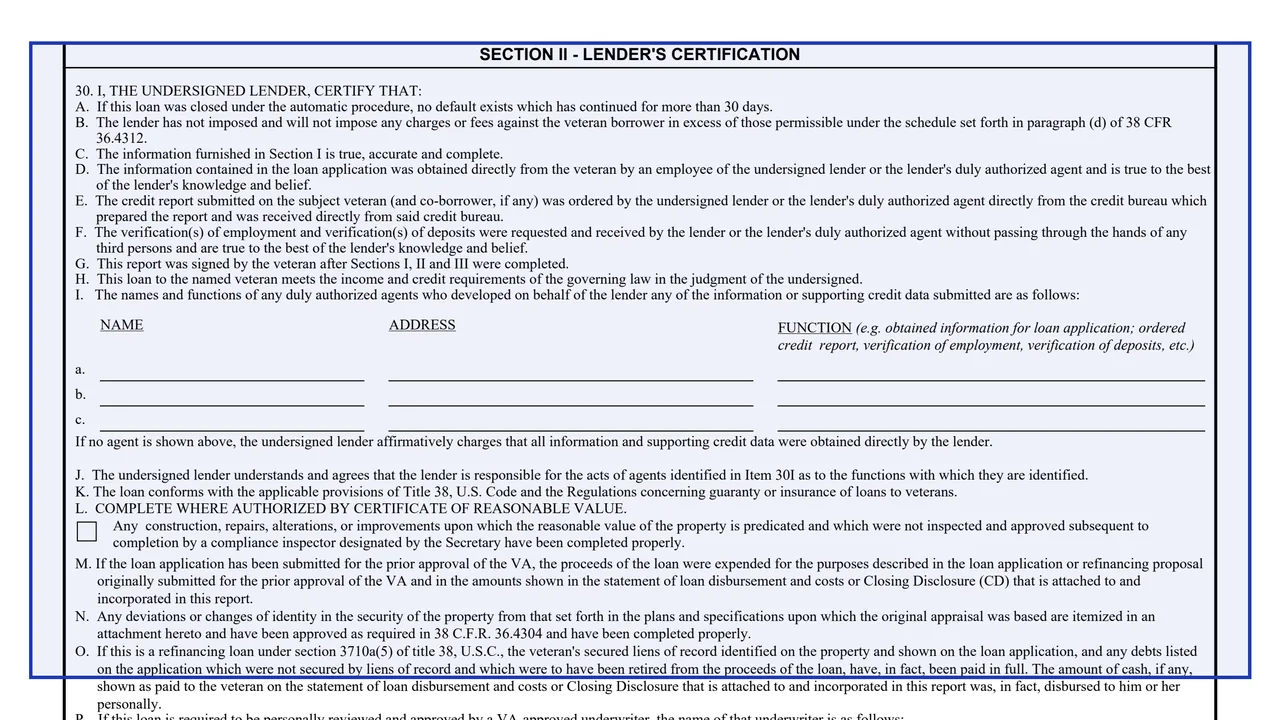
Item 30 certifications A to P, the underwriter's name and VA ID number, the lender's name, address and telephone, and the date and signature and title of the lender representative.
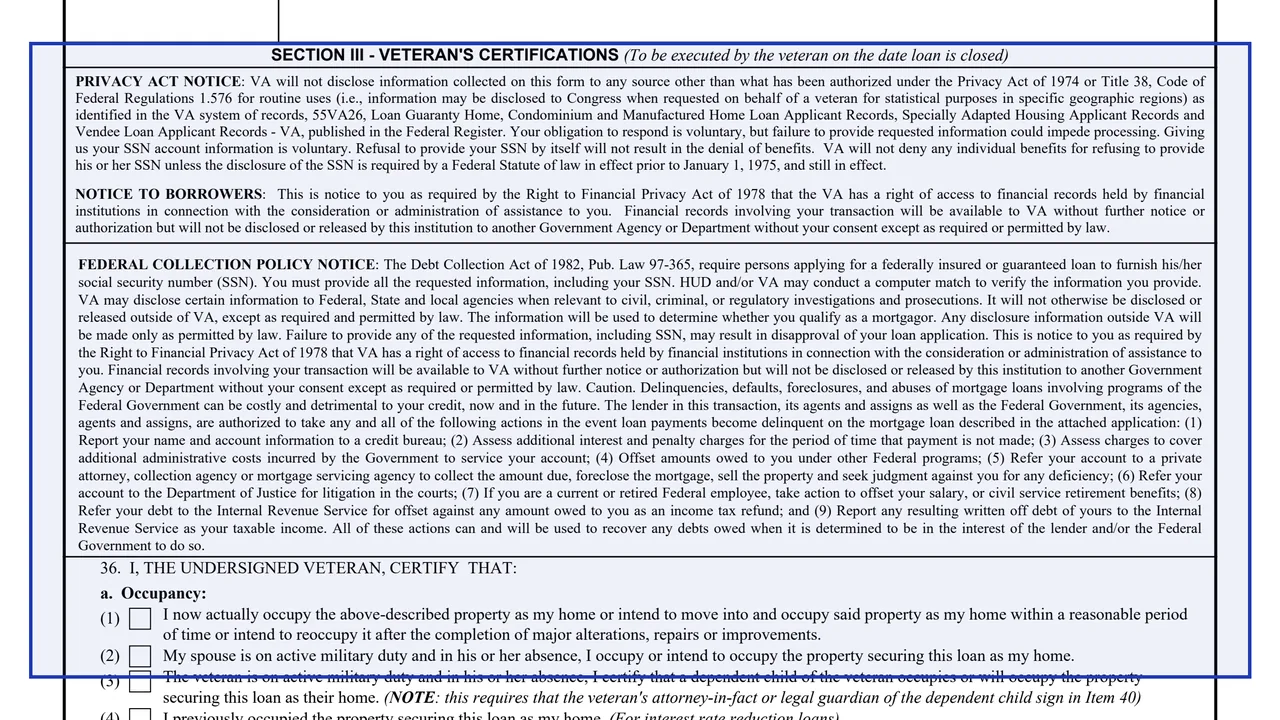
Occupancy, the reasonable value of the property as determined by VA, nondiscrimination, the statement that VA does not warrant the condition or value of the property, Certificate of Eligibility conditions and the signatures.
At the top, check automatic procedure or prior approval procedure, and guaranty or insurance.
Enter the loan identification, purpose, terms, lien, title, escrow and property cost items. The form says to attach a separate sheet if necessary for Items 25 and 27.
A lender representative signs and dates Section II after naming any agents and the underwriter. For prior approval loans, the certification refers to an attached statement of loan disbursement and costs or Closing Disclosure.
The Veteran checks the occupancy and reasonable value statements in Section III and signs Item 40 on the date the loan is closed. Item 30G certifies the Veteran signed after Sections I, II and III were completed.
A co-obligor signs Item 41. The form says the Veteran's spouse also signs Item 41 when occupancy item (2) or (5) is checked.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form is a report of the undersigned lender made under Section 3702(c), Title 38, United States Code. It prints no mailing address.
For a loan submitted for prior approval, the lender's certification refers to the statement of loan disbursement and costs or Closing Disclosure (CD) attached to and incorporated in the report.
The respondent burden note says you can call 1-800-827-1000 to get information on where to send comments or suggestions about this form. It estimates an average of 20 minutes to complete.
The October 2022 edition supersedes the November 2020 edition, which will not be used. It carries OMB Control No. 2900-0521 with an expiration date of 10/31/2025 printed on it.
26-1880
61 fields, 4 pages
26-1805
67 fields, 2 pages
26-8923
28 fields, 1 page
26-0503
2 fields, 1 page
26-6393
104 fields, 1 page
The form is a lender's report, with certifications from the Veteran and others named on the loan.
No tool matches that search.
Its instructions say it is for use by lenders closing VA loans under 38 U.S.C. 3710. The lender completes Sections I and II, and the Veteran executes Section III on the date the loan is closed.
Section III says it is executed by the Veteran on the date the loan is closed. The lender certifies in Item 30G that the report was signed by the Veteran after Sections I, II and III were completed.
Items 37 and 38 are marked as voluntary information for government monitoring purposes. A Veteran or co-obligor who does not wish to complete them initials the box instead.
No. In Item 36d the Veteran certifies: I am aware that VA does not warrant the condition or value of the property.
Item 36b has two statements for this case, one for a Veteran who knew of the valuation when signing the contract and one for a Veteran who did not. Each says the Veteran has paid or will pay the difference in cash from their own resources at or prior to loan closing.
The Privacy Act notice says giving your SSN is voluntary. The Federal Collection Policy Notice on the same page says the Debt Collection Act of 1982 requires persons applying for a federally insured or guaranteed loan to furnish their SSN, and that failure to provide it may result in disapproval of the loan application.