Header
Name as shown on Form 8849, EIN, total refund, the period of claim in MMDDYYYY format, and the claimant's registration number box, printed with the prefix CC.
8849
Registered Credit Card Issuers
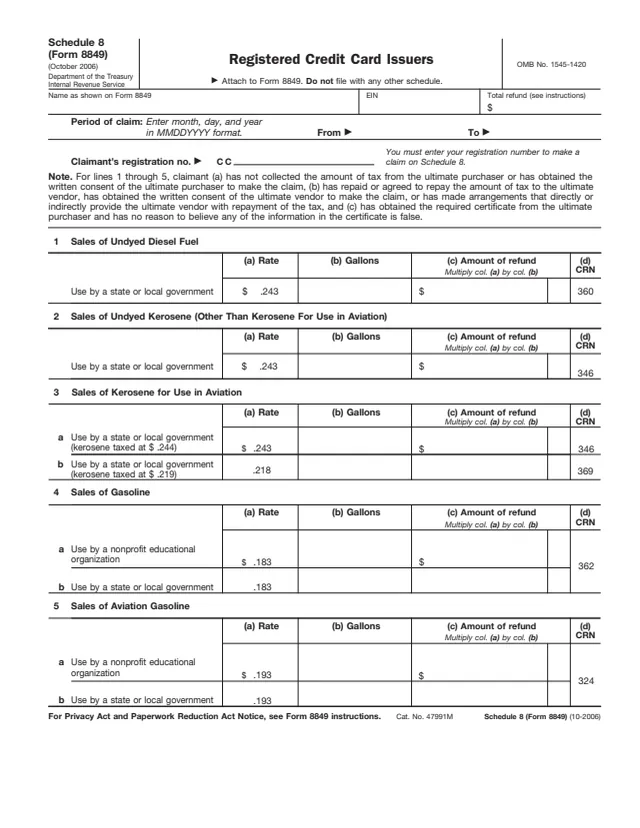
Schedule 8 (Form 8849), Registered Credit Card Issuers, is used by registered credit card issuers to make a claim for refund or payment of tax paid on certain sales of taxable fuel (diesel fuel, kerosene and gasoline) to state and local governments and certain sales of gasoline to nonprofit educational organizations. The instructions say the fuel must have been purchased with a credit card issued to the state or local government or nonprofit educational organization by the credit card issuer making the claim.
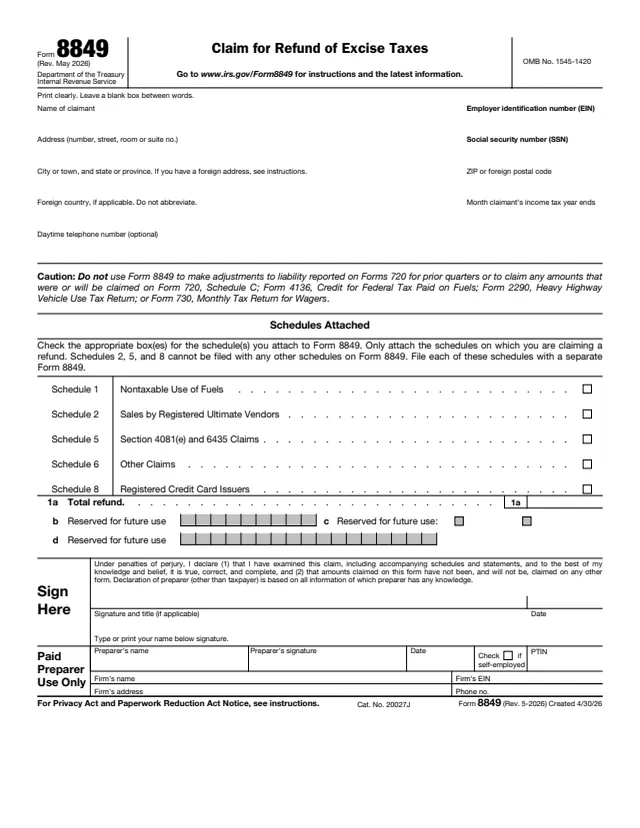
The schedule is attached to Form 8849, Claim for Refund of Excise Taxes, and the form says "Do not file with any other schedule." Its instructions are printed on page 2 of the PDF.
This page has the October 2006 edition, the Schedule 8 PDF linked from the IRS About page for Form 8849. Its rates and its reference to Pub. 510, Excise Taxes for 2006, are as printed in that edition. You can fill it out free in your browser on this page and download the result without an account.
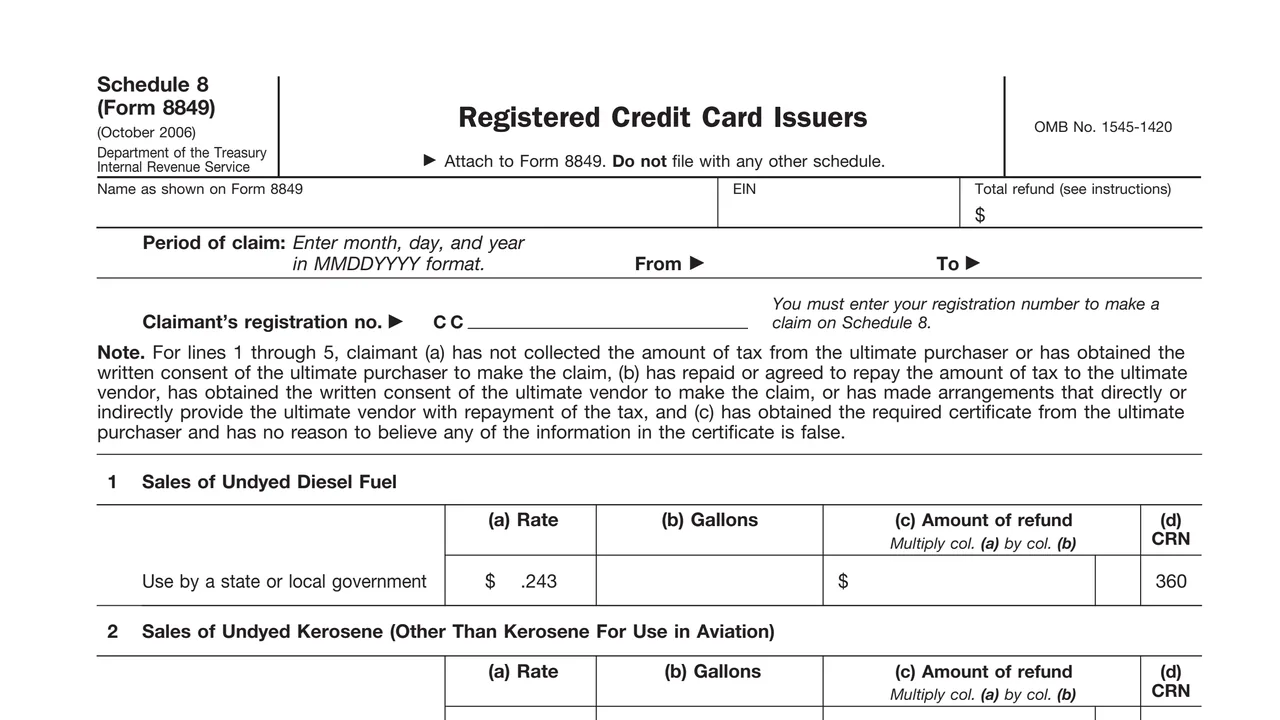
Name as shown on Form 8849, EIN, total refund, the period of claim in MMDDYYYY format, and the claimant's registration number box, printed with the prefix CC.
Three conditions about collecting or repaying the tax, written consent of the ultimate purchaser or ultimate vendor, and the required certificate from the ultimate purchaser.
Sales of undyed diesel fuel and of undyed kerosene (other than kerosene for use in aviation) for use by a state or local government.
Lines 3a and 3b, split by the rate at which the kerosene was taxed, for use by a state or local government.
Use by a nonprofit educational organization on lines 4a and 5a, and use by a state or local government on lines 4b and 5b.
Each line has a printed rate, gallons, the amount of refund (column (a) multiplied by column (b)) and a CRN.
Enter the name as shown on Form 8849 and the EIN, then the From and To dates of the period of claim in MMDDYYYY format.
The schedule says the registration number is required to make a claim on Schedule 8.
Lines 1 through 5 assume the claimant meets conditions (a), (b) and (c) in the note, including the required certificate. The instructions point to Model Certificate R in Pub. 510.
For each fuel and use that applies, enter the gallons in column (b) and multiply by the rate in column (a) to get column (c).
The instructions say to add all amounts in column (c) and enter the result in the total refund box at the top of the schedule.
Attach Schedule 8 to Form 8849. The instructions say to write "Registered Credit Card Issuer Claim" on the envelope and mail it to the address under Where To File in the Form 8849 instructions.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach the schedule to Form 8849, write "Registered Credit Card Issuer Claim" on the envelope, and mail it to the address under Where To File in the Form 8849 instructions.
The instructions say the claim must be for taxable fuel sold during a period that is at least 1 week, and the amount of the claim must be at least $200. Amounts from lines 1 through 5 may be combined.
The instructions say the claim must be filed by the last day of the first quarter following the earliest quarter of the claimant's income tax year included in the claim.
The instructions say a calendar-year claimant's claim for diesel fuel sold during September and October must be filed by December 31.
If the requirements are not met for lines 1 through 3, the instructions point to Annual Claims in the Form 8849 instructions.
The form says to attach it to Form 8849 and "Do not file with any other schedule."
8849
27 fields, 4 pages
637
50 fields, 7 pages
8849 Sch. 1
205 fields, 4 pages
8849 Sch. 2
147 fields, 5 pages
8849 Sch. 3
81 fields, 3 pages
8849 Sch. 6
26 fields, 1 page
The schedule is filed by a credit card issuer that the IRS has registered. The state or local government or nonprofit educational organization that bought the fuel is the ultimate purchaser described in the note above line 1.
No tool matches that search.
The instructions say it is used by registered credit card issuers that meet the conditions in the note above line 1.
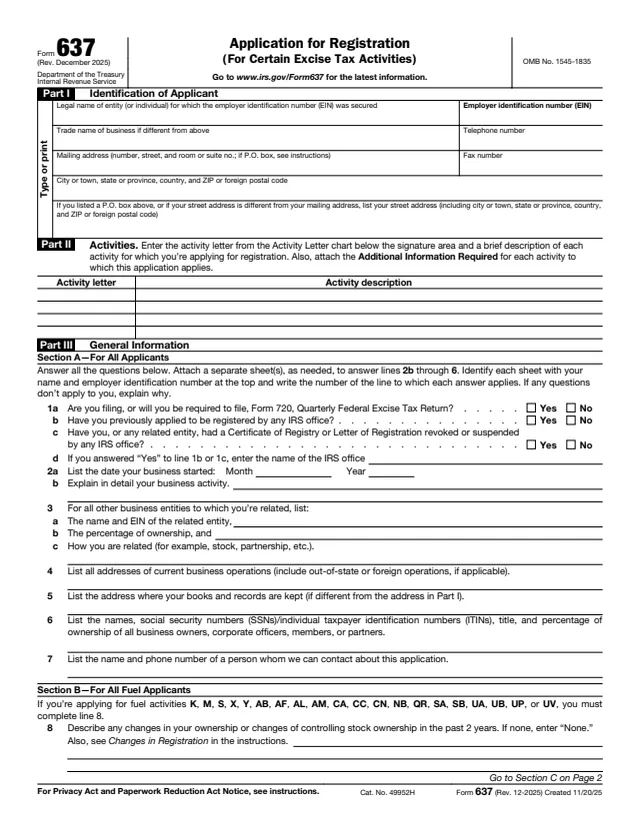
The instructions point to Form 637, Application for Registration (For Certain Excise Tax Activities).
The instructions say at least $200, for fuel sold during a period of at least 1 week. Amounts from lines 1 through 5 may be combined.
It is attached to Form 8849 and mailed to the address under Where To File in the Form 8849 instructions, with "Registered Credit Card Issuer Claim" written on the envelope.
No. The form says to attach it to Form 8849 and not to file it with any other schedule.
The October 2006 edition, which is the Schedule 8 PDF linked from the IRS About page for Form 8849.