Header and registration number
Name as shown on Form 8849, EIN or SSN, the total refund box, and the claimant's registration number with its prefix.
8849 Sch. 3
Certain Fuel Mixtures and the Alternative Fuel Credit
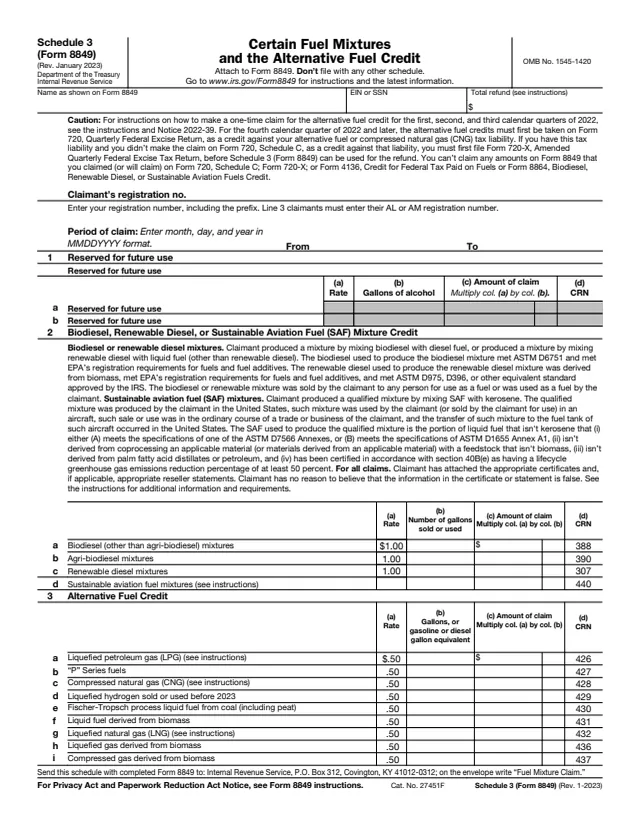
Schedule 3 (Form 8849), Certain Fuel Mixtures and the Alternative Fuel Credit, is the IRS schedule for claims on sales or uses of biodiesel mixtures, renewable diesel mixtures, sustainable aviation fuel (SAF) mixtures and alternative fuels. It is attached to Form 8849, Claim for Refund of Excise Taxes, and the form says not to file it with any other schedule.
The schedule has two active claim lines. Line 2 covers biodiesel, agri-biodiesel, renewable diesel and SAF mixtures. Line 3 covers the alternative fuel credit for fuels such as liquefied petroleum gas (LPG), compressed natural gas (CNG) and liquefied natural gas (LNG). Line 1 is reserved for future use. Its instructions are printed on pages 2 and 3 of the same PDF.
The current revision is January 2023. A note on the IRS About page, dated April 11, 2025, says to use the January 2023 revision of Schedule 3 (Form 8849) to report any allowable claims for 2024. You can fill out the PDF free in your browser on this page and download it without an account.
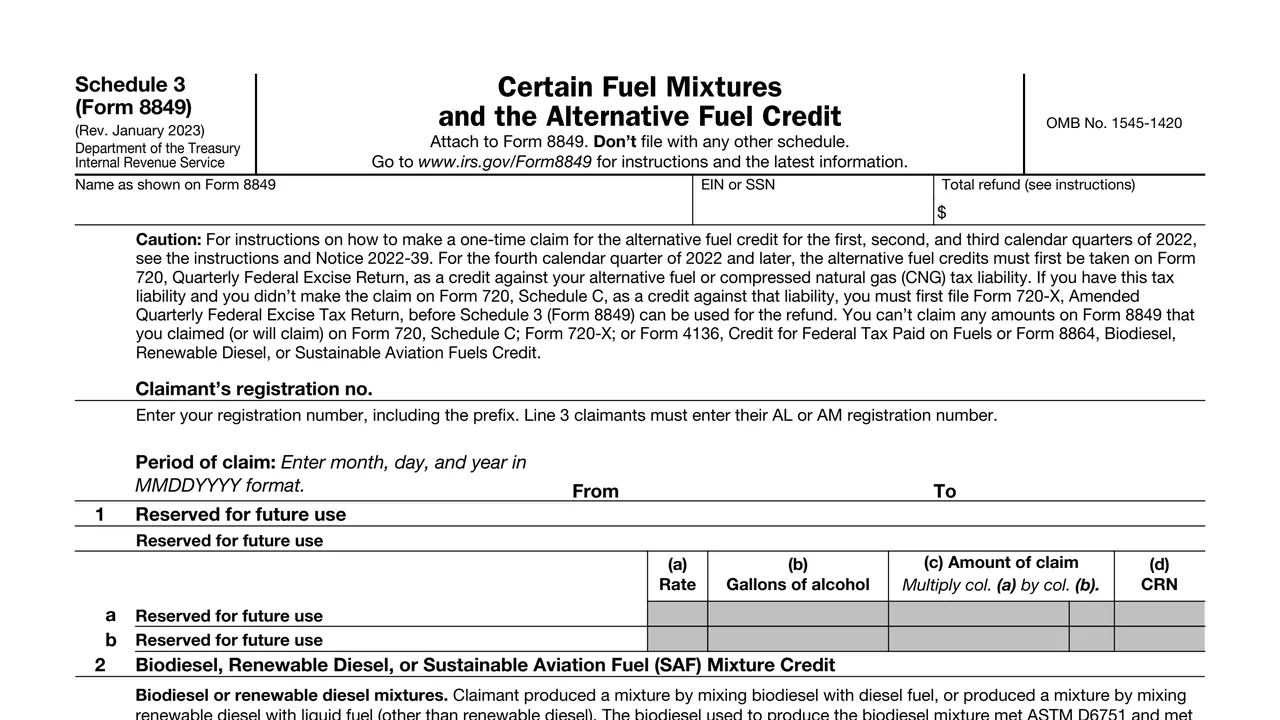
Name as shown on Form 8849, EIN or SSN, the total refund box, and the claimant's registration number with its prefix.
From and To dates, entered as month, day and year in MMDDYYYY format.
Line 1 and its sub-lines 1a and 1b are marked reserved for future use.
Biodiesel (other than agri-biodiesel) mixtures, agri-biodiesel mixtures and renewable diesel mixtures at a printed rate of $1.00 (CRNs 388, 390 and 307), and SAF mixtures (CRN 440, see instructions).
Lines 3a to 3i at a printed rate of $.50: LPG, P Series fuels, CNG, liquefied hydrogen sold or used before 2023, Fischer-Tropsch liquid fuel from coal, liquid fuel derived from biomass, LNG, and liquefied or compressed gas derived from biomass.
Each row has a rate, the gallons (or gasoline or diesel gallon equivalent) sold or used, the amount of claim (column (a) times column (b)), and the CRN.
Enter the name and EIN or SSN as shown on Form 8849, the registration number with its prefix, and the period of claim in MMDDYYYY format.
Enter the gallons sold or used. The instructions give claim rates for some fuels: CNG at 121 cubic feet per GGE, LPG at 5.75 pounds or 1.353 gallons per GGE, and LNG at 6.06 pounds or 1.71 gallons per DGE.
Multiply the rate by the gallons or gallon equivalents. The instructions give this example: 10,000 gallons of LPG divided by 1.353 = 7,391 GGE, times $0.50 = $3,695.50.
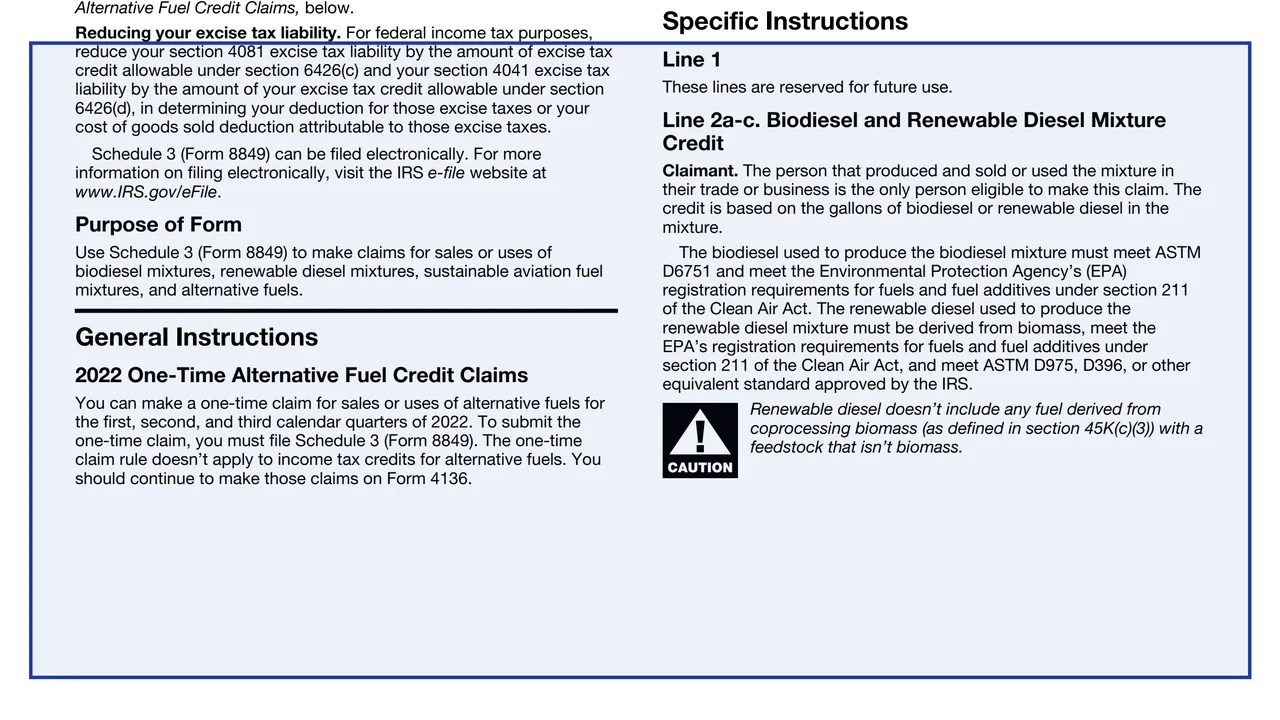
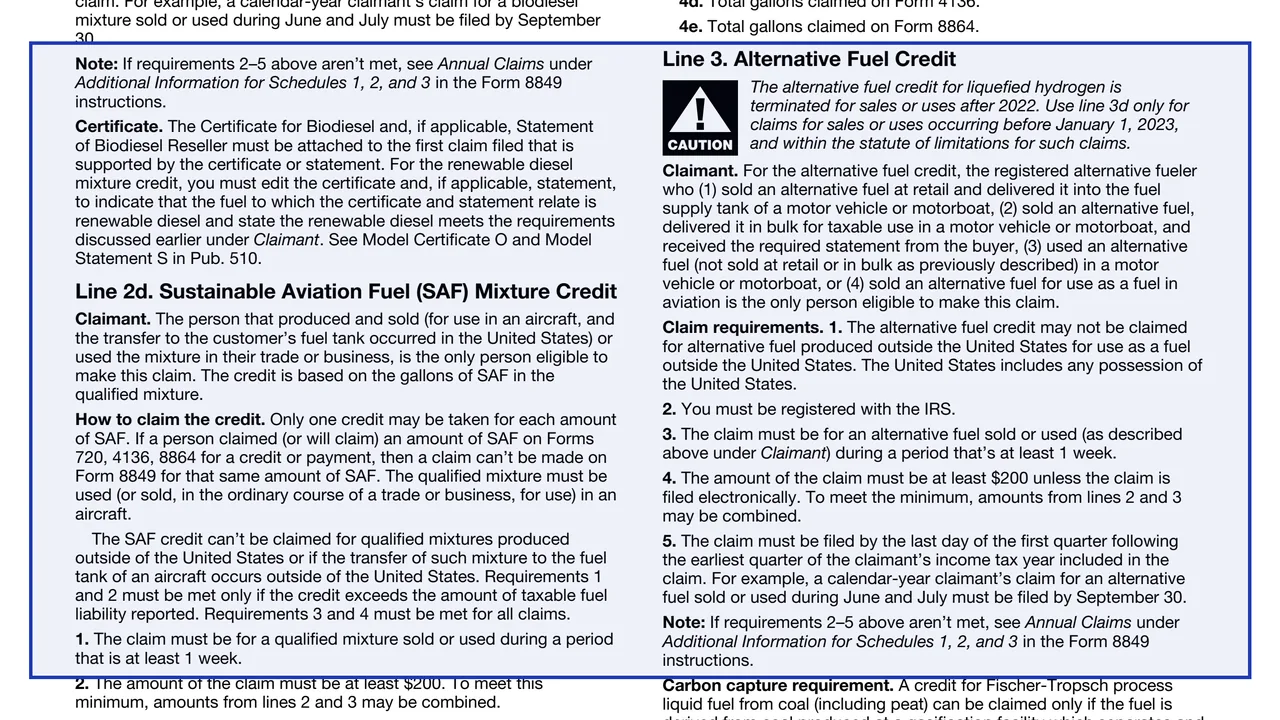
The Certificate for Biodiesel and, if applicable, the Statement of Biodiesel Reseller are attached to the first claim they support. For SAF, the instructions list the Certificate for SAF Synthetic Blending Component, the reseller statement and the Declaration for SAF Qualified Mixture.
The instructions say the claim is at least $200 unless it is filed electronically, and amounts from lines 2 and 3 may be combined to meet the minimum.
Add all amounts in column (c) and enter the result in the total refund box at the top of page 1.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to send the schedule with completed Form 8849 to: Internal Revenue Service, P.O. Box 312, Covington, KY 41012-0312, and to write "Fuel Mixture Claim" on the envelope.
The instructions say Schedule 3 (Form 8849) can be filed electronically and point to the IRS e-file website at www.IRS.gov/eFile.
The instructions say the claim is filed by the last day of the first quarter following the earliest quarter of the claimant's income tax year included in the claim. A calendar-year claim for June and July is filed by September 30.
The claim covers fuel sold or used during a period of at least 1 week. If the requirements are not met, the instructions point to Annual Claims in the Form 8849 instructions.
The instructions say only one credit may be taken for any one gallon. A gallon claimed on Form 720, Form 720-X, Form 8864 or Form 4136 cannot also be claimed on Form 8849.
The form says that for the fourth calendar quarter of 2022 and later, alternative fuel credits are first taken on Form 720 against alternative fuel or CNG tax liability, and Form 720-X is filed first if that was not done.
8849
27 fields, 4 pages
720
715 fields, 8 pages
720-X
120 fields, 2 pages
4136
485 fields, 4 pages
8864
32 fields, 1 page
637
50 fields, 7 pages
The schedule is filed by businesses that produce fuel mixtures or sell or use alternative fuels. For each line, the instructions name the only person eligible to make the claim.
No tool matches that search.
No. The form says to attach it to Form 8849 and not to file it with any other schedule.
$1.00 for lines 2a to 2c and $.50 for lines 3a to 3i. Line 2d, for SAF mixtures, has no printed rate and says to see the instructions.
The instructions say the claim is at least $200 unless it is filed electronically. Amounts from lines 2 and 3 may be combined to meet it.
The instructions say the credit for liquefied hydrogen is terminated for sales or uses after 2022. Line 3d is only for sales or uses before January 1, 2023, within the statute of limitations.
The form prints Internal Revenue Service, P.O. Box 312, Covington, KY 41012-0312, with "Fuel Mixture Claim" written on the envelope.
The IRS About page has a note dated April 11, 2025 to use the January 2023 revision of Schedule 3 (Form 8849) to report any allowable claims for 2024.