Claimant information
Name, address, EIN, SSN, ZIP or foreign postal code, foreign country, the month the claimant's income tax year ends and an optional daytime phone number.
8849
Claim for Refund of Excise Taxes
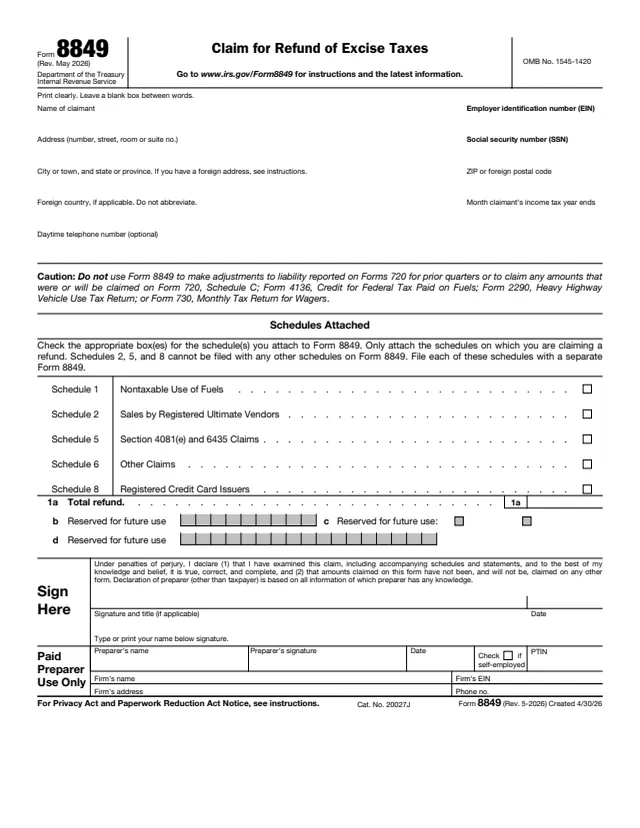
Form 8849 is the IRS form for claiming a refund of excise taxes. The form itself is one page: the claimant's name, address, EIN or SSN and the month the income tax year ends, a box for each schedule attached, the total refund on line 1a, and a signature. The details of each claim go on the schedules.
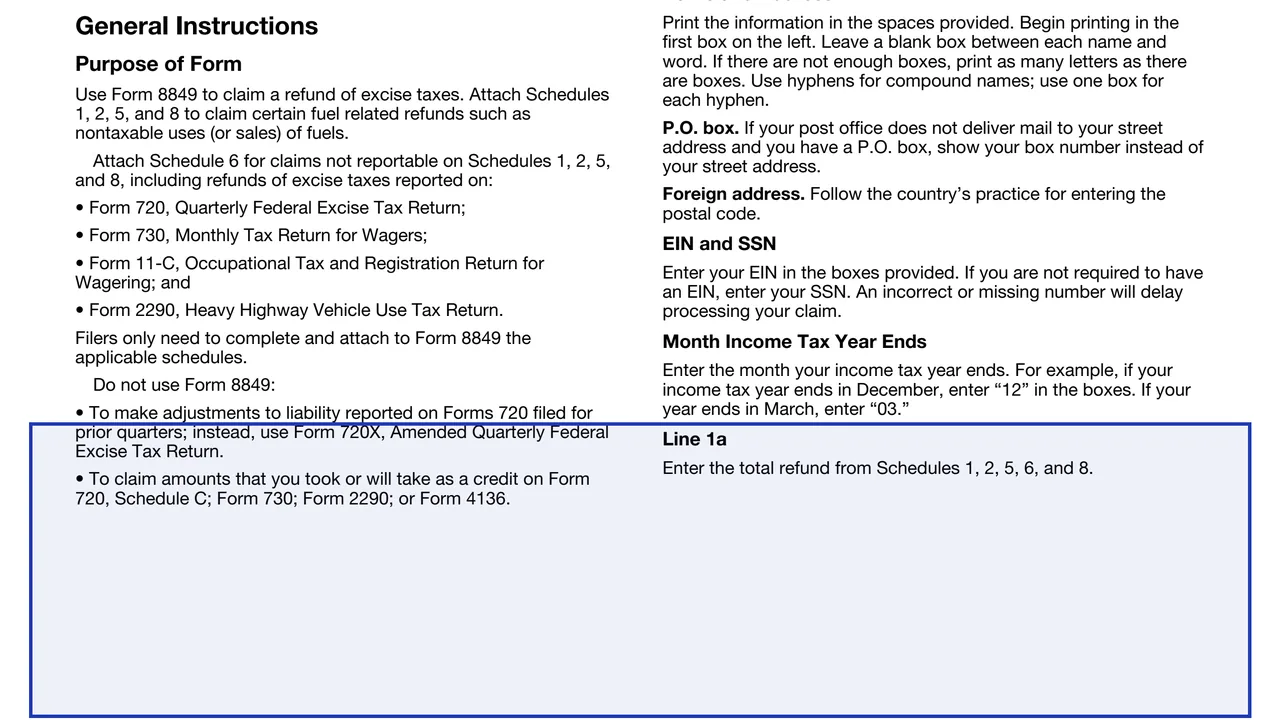
The instructions say to attach Schedules 1, 2, 5 and 8 to claim certain fuel related refunds, such as nontaxable uses or sales of fuels, and Schedule 6 for claims not reportable on those schedules, including refunds of excise taxes reported on Form 720, Form 730, Form 11-C and Form 2290.
The form says not to use it to adjust liability reported on Form 720 for prior quarters, or to claim amounts that were or will be claimed on Form 720, Schedule C, Form 4136, Form 2290 or Form 730. You can fill out the PDF free in your browser on this page and download it without an account.
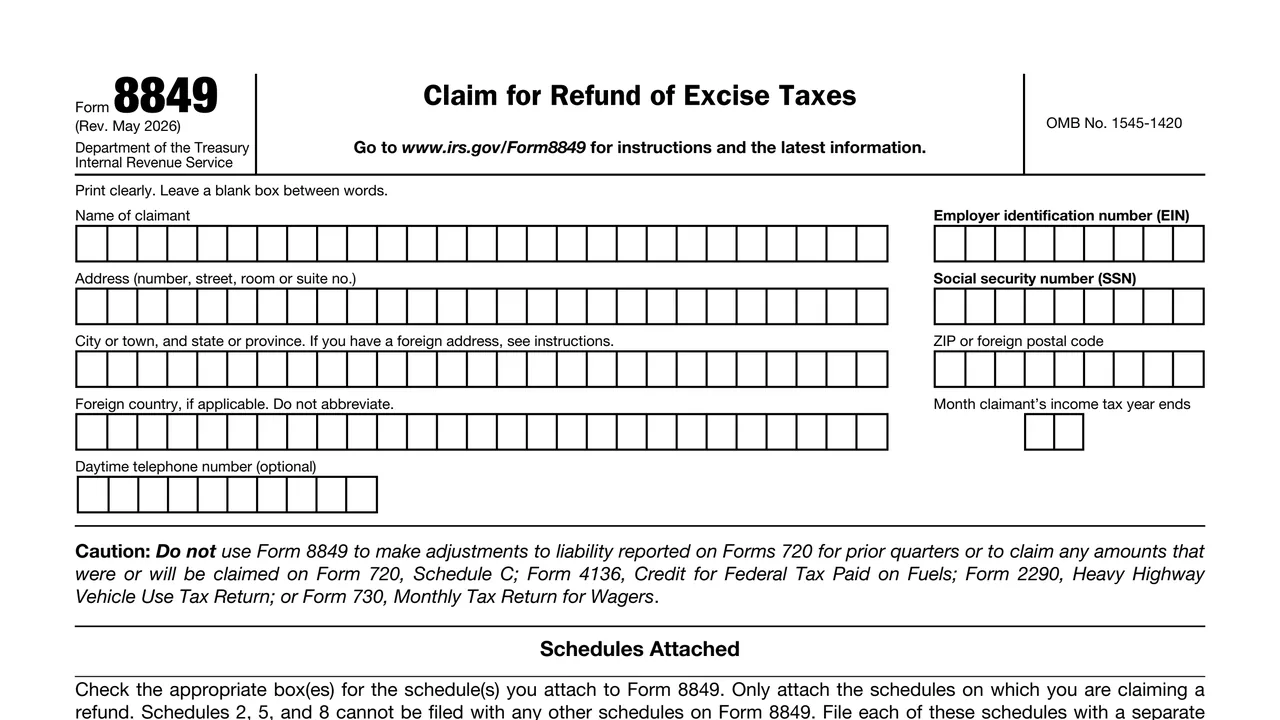
Name, address, EIN, SSN, ZIP or foreign postal code, foreign country, the month the claimant's income tax year ends and an optional daytime phone number.
A note that the form is not for adjusting prior quarter Form 720 liability or for amounts claimed on Form 720 Schedule C, Form 4136, Form 2290 or Form 730.
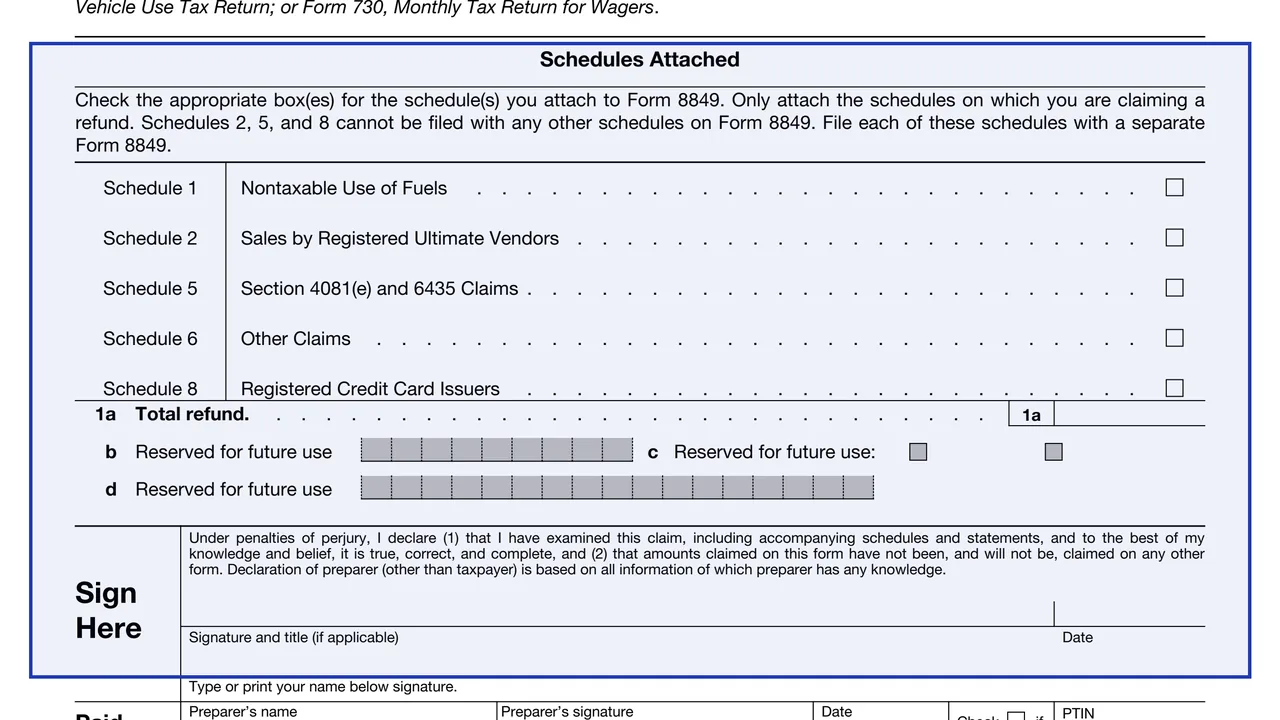
Boxes for Schedules 1, 2, 5, 6 and 8. The form says Schedules 2, 5 and 8 cannot be filed with any other schedules, and each is filed with a separate Form 8849.
The total refund from the attached schedules. Lines 1b, 1c and 1d are reserved for future use.
A declaration under penalties of perjury that the claim is true, correct and complete and that the amounts have not been and will not be claimed on any other form, then signature, title, date and printed name.
The preparer's name, signature, date and PTIN, a self-employed box, and the firm's name, EIN, address and phone number.
Print in the boxes starting at the left, leaving a blank box between words and using one box for each hyphen. The instructions say to show a P.O. box only if the post office does not deliver to the street address.
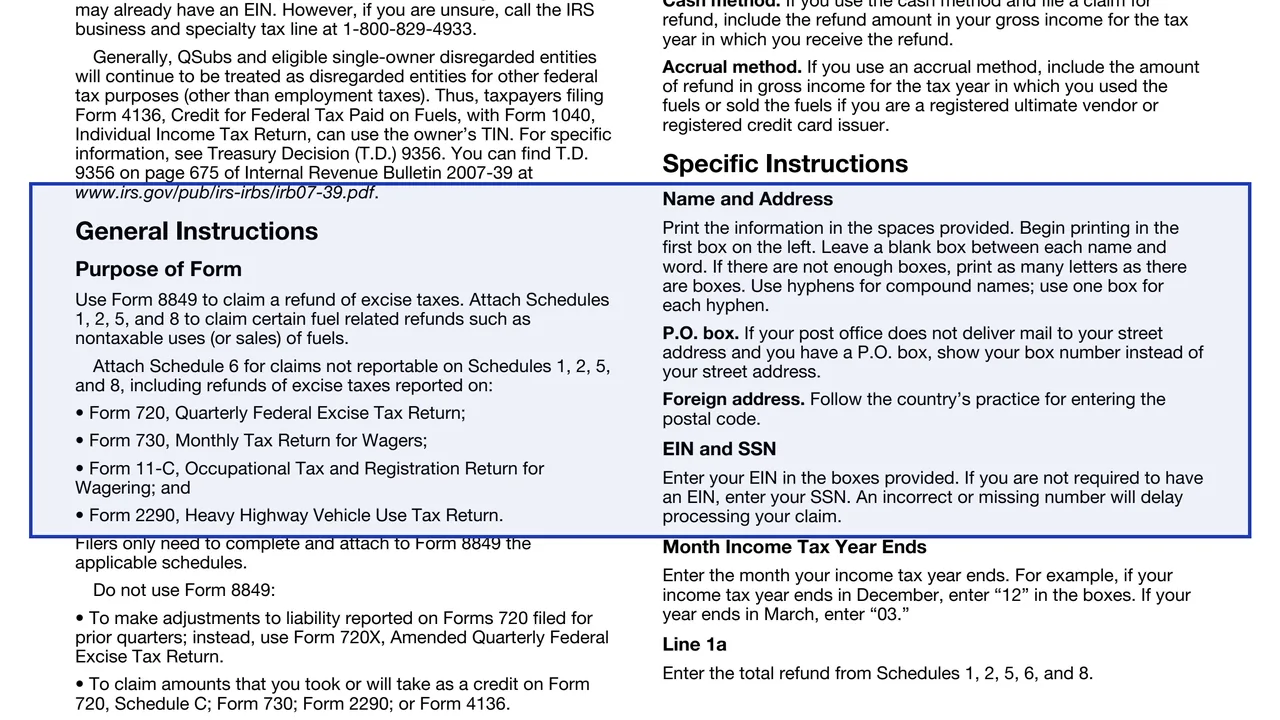
Enter the EIN. The instructions say to enter an SSN only if the claimant is not required to have an EIN, and that an incorrect or missing number will delay processing.
Enter two digits for the month, for example 12 for a year that ends in December or 03 for one that ends in March.
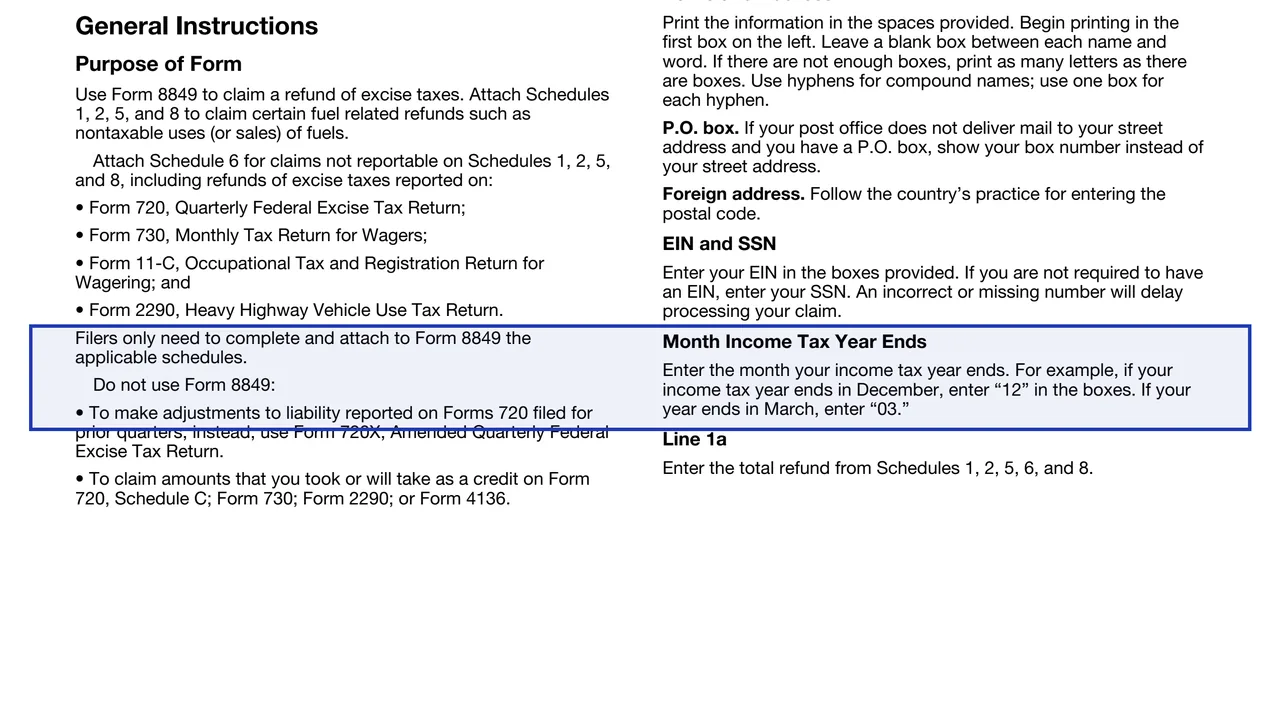
Check the box for each schedule attached, and attach only schedules on which a refund is claimed. The instructions list what each schedule generally carries: EIN or SSN, period of the claim, type of use number, rate, gallons and refund amount.
Enter the total refund from Schedules 1, 2, 5, 6 and 8.
A person with authority to sign for the claimant signs, dates and prints a name. A paid preparer enters a PTIN and, if working for a firm, the firm's name and EIN.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to send Form 8849 to Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0002.
The form says to send Form 8849 to Internal Revenue Service, P.O. Box 312, Covington, KY 41012-0312, and notes that IRS designated private delivery services cannot deliver to P.O. boxes.
The form says it can be filed electronically through an electronic return originator (ERO), transmitter or intermediate service provider (ISP) in the IRS e-file program for excise taxes.
The form says an annual claim is generally made on Form 4136, but the United States, states and certain exempt organizations use Schedule 1 and file the annual Form 8849 within the 3 years following the close of the taxable year.
The form says to include the refund in gross income if the tax was claimed as an expense deduction that reduced income tax liability.
The form lists the IRS business and specialty tax line at 1-800-829-4933 and points to Pub. 510 and Pub. 225 for fuel tax credits and refunds.
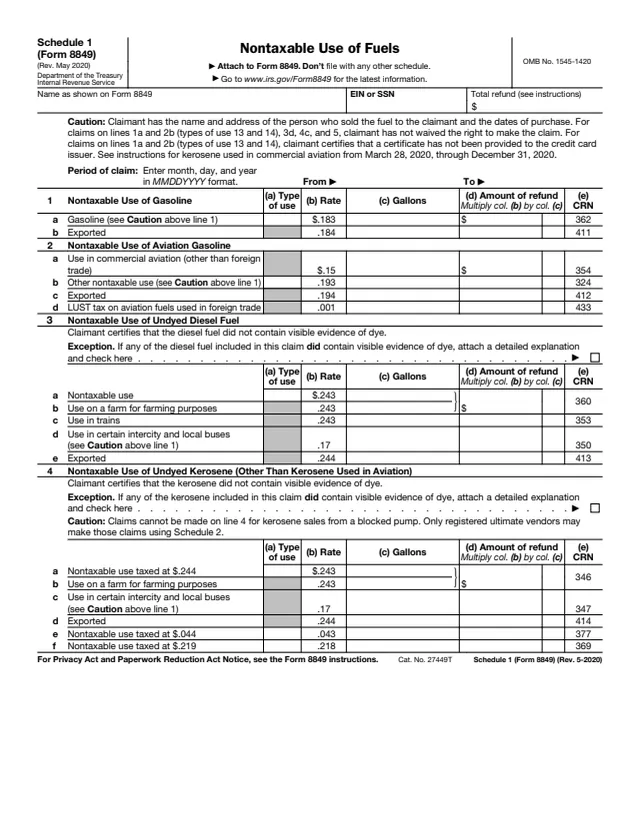
8849 Sch. 1
205 fields, 4 pages
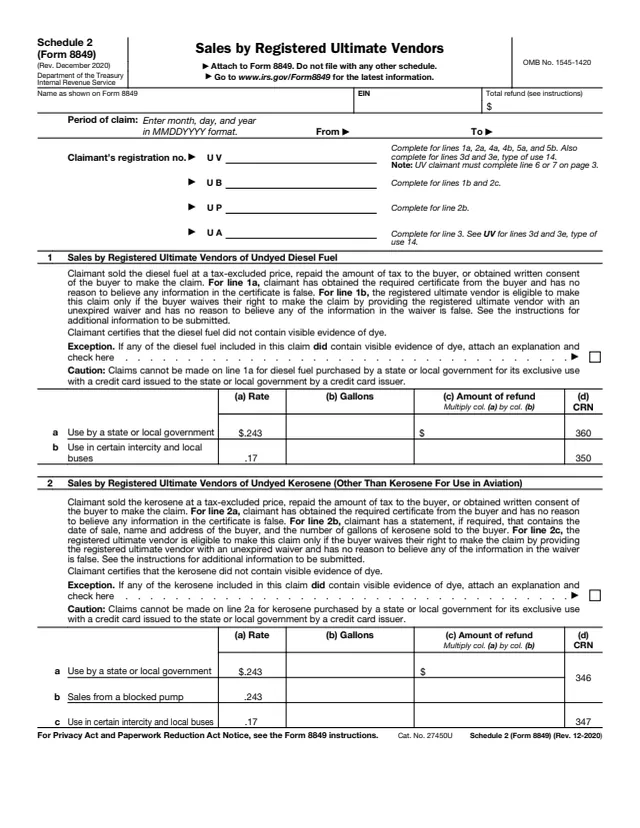
8849 Sch. 2
147 fields, 5 pages
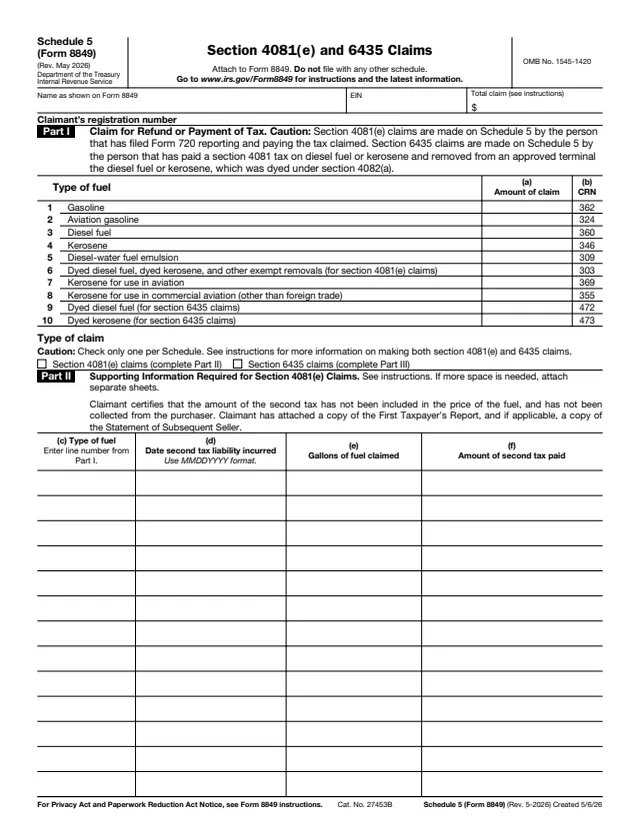
8849 Sch. 5
130 fields, 2 pages
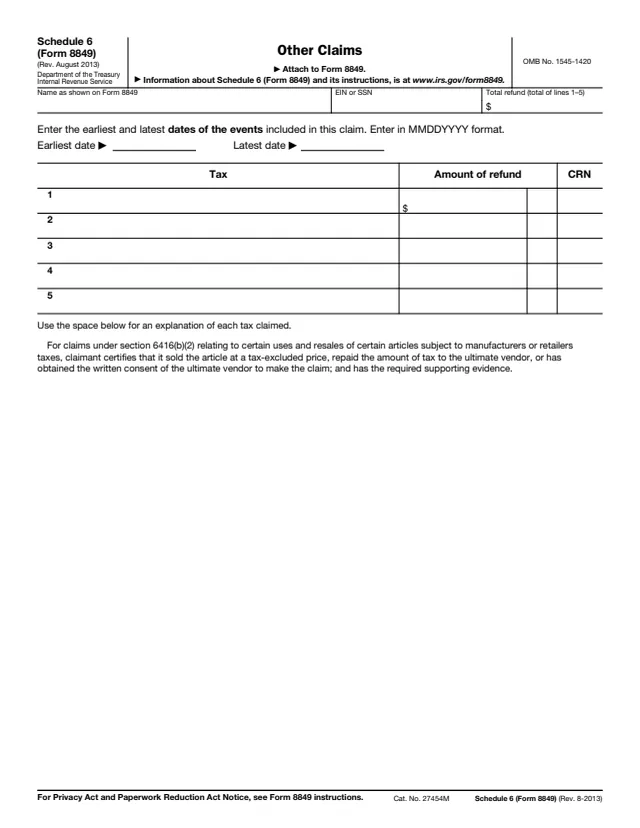
8849 Sch. 6
26 fields, 1 page
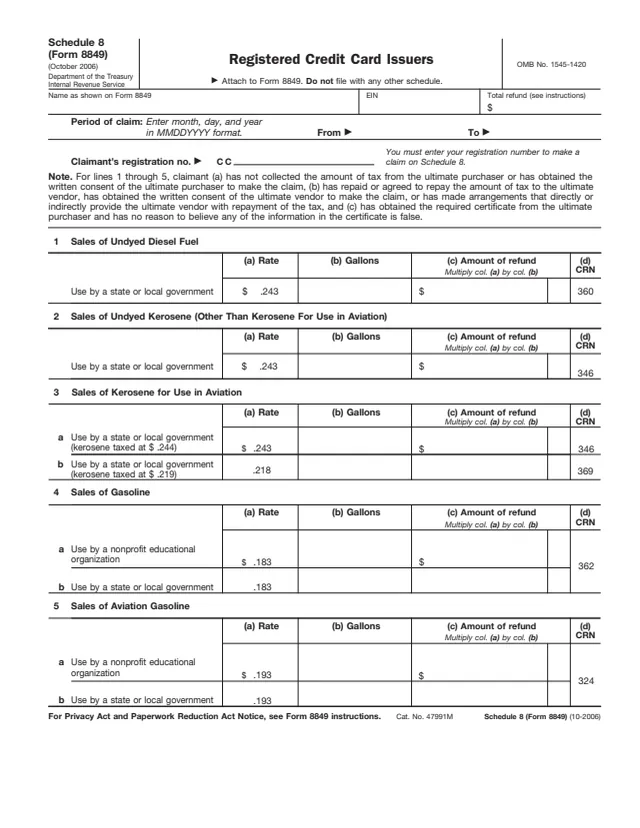
8849
30 fields, 2 pages
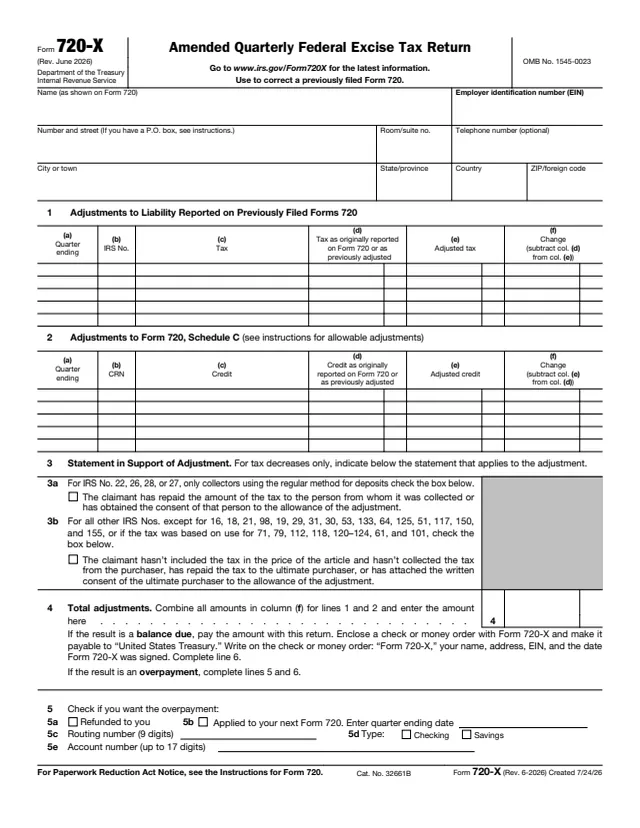
720-X
120 fields, 2 pages
The claimant files it. The instructions say the form is signed by a person with authority to sign it for the claimant, and that a paid preparer who is not an employee of the filing entity also signs. Which schedule is attached depends on the claim.
No tool matches that search.
The form says Schedules 2, 5 and 8 cannot be filed with any other schedules, and each of them is filed with a separate Form 8849.
No. The instructions say adjustments to liability reported on Forms 720 for prior quarters go on Form 720-X, Amended Quarterly Federal Excise Tax Return.
Yes. The form says it can be e-filed through an ERO, transmitter or ISP participating in the IRS e-file program for excise taxes.
It depends on the schedule. The form gives Cincinnati, OH 45999-0002 for Schedules 1 and 6, and P.O. Box 312, Covington, KY 41012-0312 for Schedules 2, 5 and 8.
The form says the section 6427 payments for fuel mixtures and alternative fuels expired for sales, uses or removals after 2024. For claims on or before December 31, 2024, it points to the August 2014 Form 8849 and the January 2023 Schedule 3.
The form says to include it in gross income if the tax was deducted as an expense that reduced income tax liability: in the year received under the cash method, or the year the fuel was used or sold under an accrual method.