Lines 1 and 2
The payer's or filer's name, address, contact name, telephone number and email, and the payer's nine-digit taxpayer identification number.
8809
Application for Extension of Time To File Information Returns
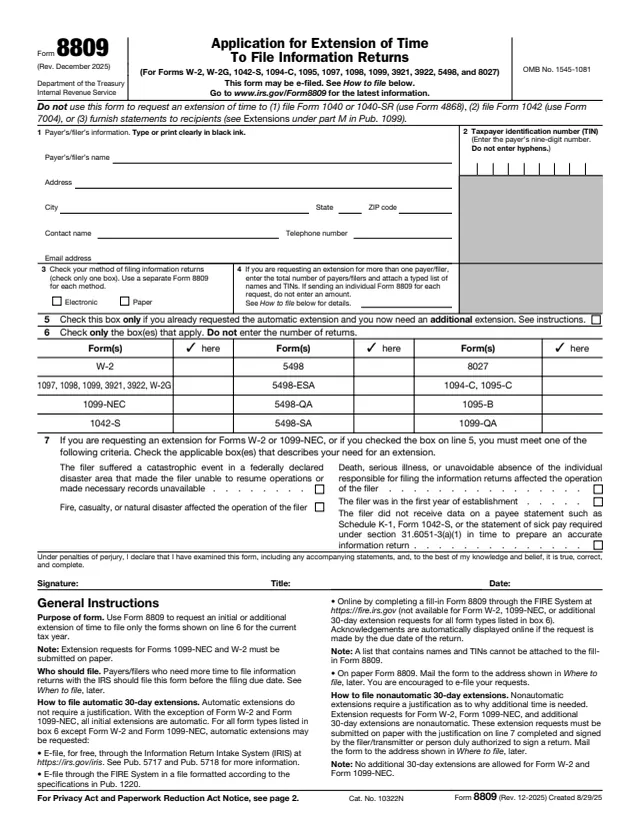
Form 8809, Application for Extension of Time To File Information Returns, is used by payers and filers to request an initial or additional extension of time to file the forms listed on line 6 for the current tax year. The form covers Forms W-2, W-2G, 1042-S, 1094-C, 1095, 1097, 1098, 1099, 3921, 3922, 5498 and 8027.
The form says not to use it for an extension to file Form 1040 or 1040-SR (use Form 4868), to file Form 1042 (use Form 7004), or to furnish statements to recipients. An approved extension only extends the due date for filing the information returns with the IRS.
For most forms the first 30-day extension is automatic and can be e-filed through IRIS or the FIRE System. Requests for Forms W-2 and 1099-NEC, and additional 30-day extensions, are nonautomatic and go on paper with line 7 completed. The instructions are on the PDF itself. You can fill out the PDF free in your browser on this page and download it without an account.
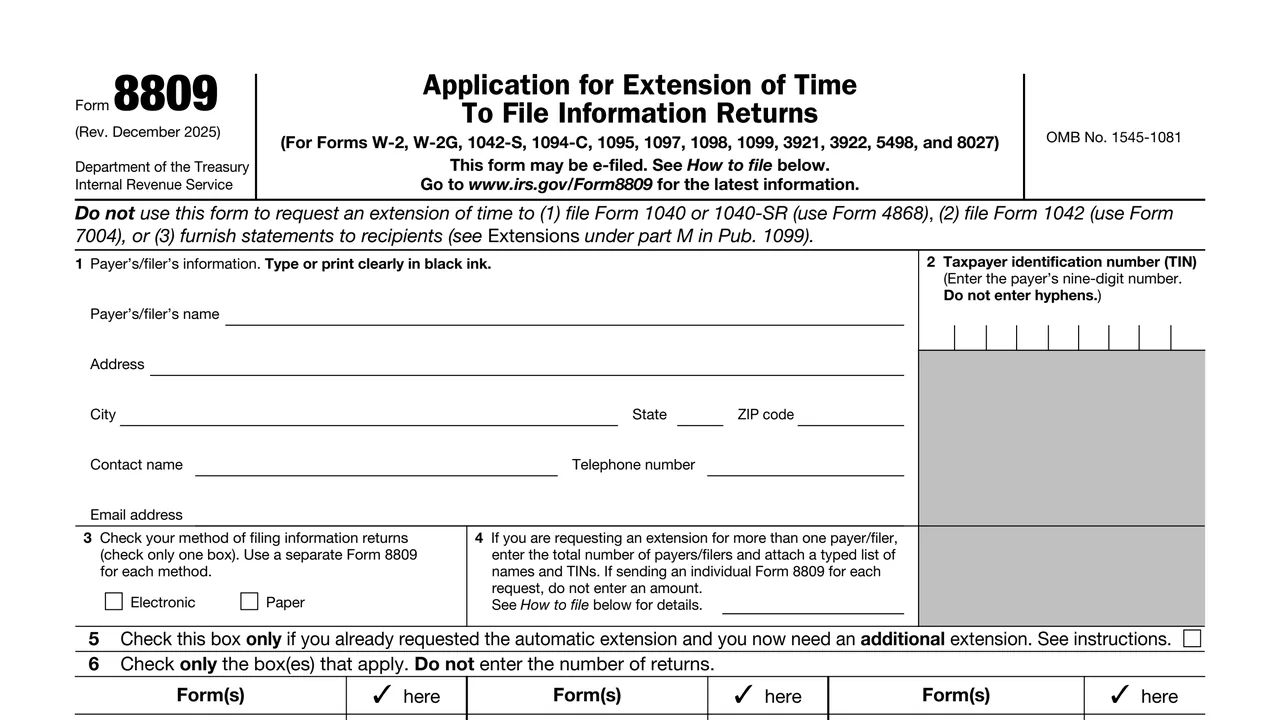
The payer's or filer's name, address, contact name, telephone number and email, and the payer's nine-digit taxpayer identification number.
The method of filing the information returns: Electronic or Paper. The form says to check only one and use a separate Form 8809 for each method.
Line 4 for the number of payers or filers in a multiple request. Line 5 for an additional extension after the automatic one.
Check boxes for the forms: W-2, the 1097, 1098, 1099, 3921, 3922 and W-2G group, 1099-NEC, 1042-S, the 5498 forms, 8027, 1094-C and 1095-C, 1095-B and 1099-QA.
The criteria for a nonautomatic or additional extension, such as a catastrophic event in a federally declared disaster area or the first year of establishment, then signature, title and date.
Enter the name and mailing address where correspondence should go, plus a contact familiar with the request. The legal name and TIN should be exactly the same as on the EIN application, with no abbreviations.
Enter the payer's nine-digit EIN, QI-EIN, WP-EIN or WT-EIN, or a social security number if no EIN is required. The form says not to enter hyphens.
Check one filing method. For a request covering more than one payer, enter the total and attach the typed list. A list cannot be attached to the fill-in Form 8809 on FIRE.
Check line 5 only after the automatic 30-day extension was already received. On line 6, check only the boxes that apply and do not enter the number of returns.
For Forms W-2 or 1099-NEC, or when line 5 is checked, check the criteria that describe the need for more time.
No signature is required for the automatic 30-day extension. Additional and W-2 or 1099-NEC requests are signed by the filer or transmitter or a person duly authorized to sign a return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Automatic 30-day extensions can be e-filed free through IRIS at https://irs.gov/iris, through FIRE in a Pub. 1220 file, or on a fill-in Form 8809 at https://fire.irs.gov. The fill-in form is not available for Form W-2, 1099-NEC or additional extensions.
Paper requests go to Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0209.
As soon as an extension is known to be needed, but not before January 1 of the year the return is due, and by the due date of the returns. A combined request is due by the earliest due date.
The chart lists January 31 for W-2 and 1099-NEC, February 28 on paper or March 31 by e-file for 1097, 1098 and 1099, March 15 for 1042-S, and May 31 for 5498.
The form says not to send a copy of Form 8809 with the returns, except that a paper Form 8027 includes a copy of the timely filed Form 8809.
An approved extension does not extend the due date for furnishing statements to recipients. The form points to Extensions under part M in Pub. 1099.
W-2
568 fields, 11 pages
1099-NEC
140 fields, 6 pages
1042-S
300 fields, 7 pages
8027
48 fields, 1 page
4868
17 fields, 4 pages
7004
26 fields, 1 page
The form says payers and filers who need more time to file information returns with the IRS file it before the filing due date.
No tool matches that search.
The form says all initial extensions are automatic except for Form W-2 and Form 1099-NEC, and automatic extensions do not require a justification.
30 days from the original due date. For forms other than W-2 or 1099-NEC, an additional 30-day extension may be requested on paper before the first one expires.
No. The form says extension requests for Forms 1099-NEC and W-2 are submitted on paper, with line 7 completed and signed.
No. It only extends the due date for filing the information returns with the IRS. The form points to part M in Pub. 1099 for statement extensions.
Yes, but the form says it is then filed by the earliest due date. For example, a request for both Forms 1098 and 5498 is due February 28, or March 31 if e-filed.
The form says an extension cannot be granted if a request is filed after the filing due date of the information returns.