Top of the form
The unique form identifier, the Amended box and the amendment number.
1042-S
Foreign Person's U.S. Source Income Subject to Withholding
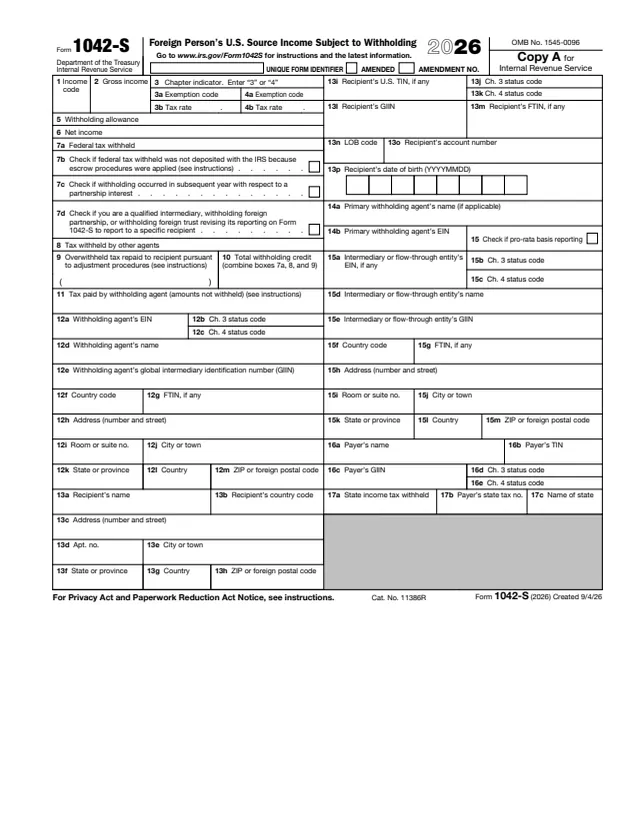
Form 1042-S is an information return. The IRS page says it is used to report income and amounts withheld as described in the Instructions for Form 1042-S, specified federal procurement payments paid to foreign persons that are subject to withholding under section 5000C, and distributions of effectively connected income by a publicly traded partnership or nominee.
The instructions say every withholding agent files it to report amounts paid during the preceding calendar year, including amounts withheld under chapter 3 or chapter 4 (FATCA). The withholding agent files Copy A with the IRS and gives Copies B, C and D to the recipient of the income. The form says the recipient keeps Copy B, attaches Copy C to any federal tax return they file and Copy D to any state tax return.
This page covers the 2026 form, for amounts paid in 2026. The instructions say 2026 Forms 1042-S are due March 15, 2027, and that the address fields are now separate entry boxes. You can fill out the PDF free in your browser on this page and download it without an account.
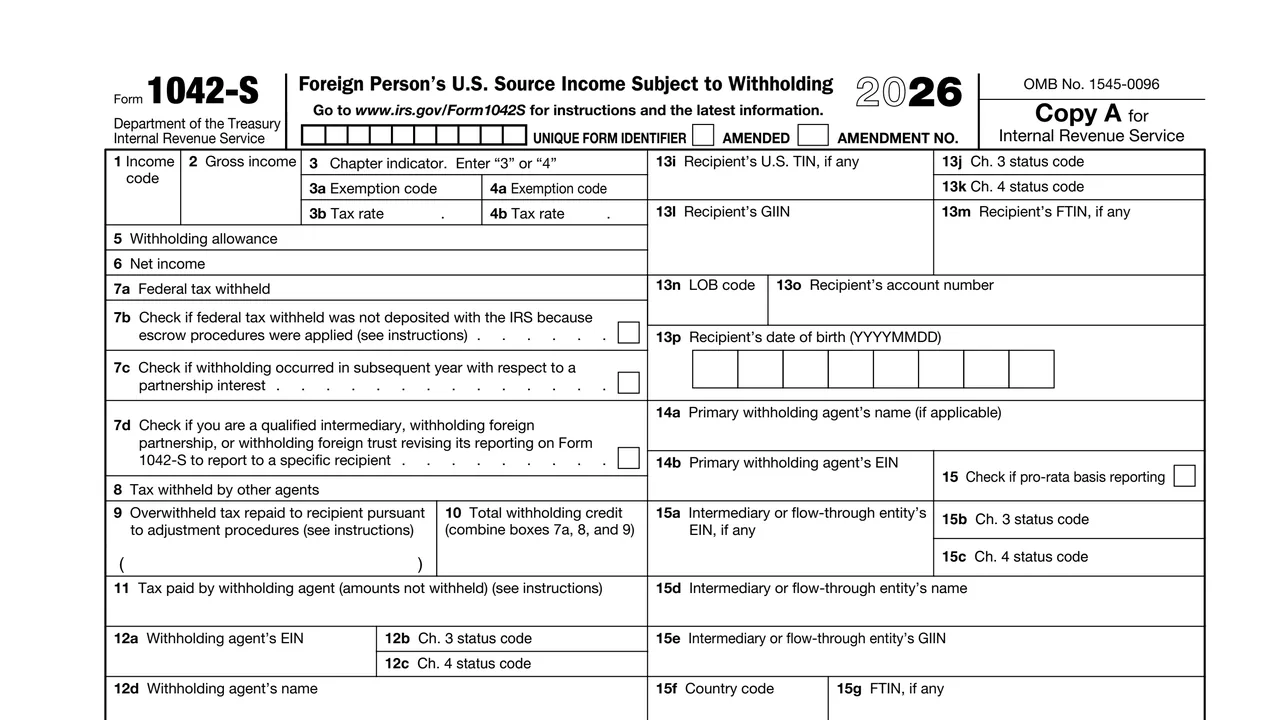
The unique form identifier, the Amended box and the amendment number.
Income code, gross income, the chapter indicator (3 or 4), the chapter 3 and chapter 4 exemption codes and tax rates, the withholding allowance and net income.
Federal tax withheld, three checkboxes (escrow procedures, withholding in a later year on a partnership interest, and revised QI reporting), tax withheld by other agents, overwithheld tax repaid, total withholding credit and tax paid by the withholding agent.
The withholding agent's EIN, chapter 3 and chapter 4 status codes, name, GIIN, country code, foreign TIN and address.
The recipient's name, country code, address in separate boxes, U.S. TIN, status codes, GIIN, foreign TIN, LOB code, account number and date of birth.
The primary withholding agent, the pro-rata basis reporting box, the intermediary or flow-through entity, the payer, and state income tax withheld.
The 2026 form has four copies with the same boxes: Copy A for the IRS and Copies B, C and D for the recipient.
Enter a numeric identifier of exactly 10 digits that is not the recipient's U.S. TIN or foreign TIN. An amended form uses the same identifier plus a one-digit amendment number.
Enter the two-digit income code from Appendix A of the instructions and the gross income. The instructions say gross income can't be zero unless an amended form is zeroing out an earlier amount.
Enter 3 or 4 as the chapter indicator, then exemption codes and tax rates in the format 30.00. The instructions say a separate Form 1042-S is filed for each rate when one type of income to one recipient was withheld at more than one rate.
Enter the tax actually withheld in box 7a, or -0- if none. Box 10 combines boxes 7a, 8 and 9. The instructions say both are completed in all cases, even if no tax has been deposited.
Enter the withholding agent's EIN, which can't be truncated, and the recipient's details. Use "Unknown Recipient" in box 13a when the recipient is not known. The instructions say a foreign address is entered in most cases.
The instructions say all amounts are reported in U.S. dollars, rounded to whole dollars: amounts under 50 cents are dropped and 50 to 99 cents go up to the next dollar.
These steps follow the Specific Instructions for Withholding Agents.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Forms 1042-S are filed with the IRS and furnished to the recipient by March 15 of the following calendar year, so 2026 forms are due March 15, 2027. A weekend or legal holiday moves it to the next business day.
Copy A goes to the IRS with Form 1042-T, a separate Form 1042-T for each type of Form 1042-S, at the address in the Form 1042-T instructions. Copies B, C and D go to the recipient.
The instructions require e-filing for a person filing 10 or more information returns in the year, a partnership with more than 100 partners, or any financial institution. They say IRIS is used to e-file 2026 Forms 1042-S, and Form 8508 requests a waiver.
Form 8809 gives an automatic 30-day extension to file. Form 15397 requests a one-time 30-day extension to furnish recipient copies, sent by fax to 877-477-0572 (international fax: 304-579-4105).
The instructions list $60 per form filed correctly within 30 days after the due date, $130 per form after that but by August 1, and $340 per form after August 1 or not filed correctly, with yearly maximums.
The instructions say a filer of Form 1042-S also files Form 1042, Annual Withholding Tax Return for U.S. Source Income of Foreign Persons.
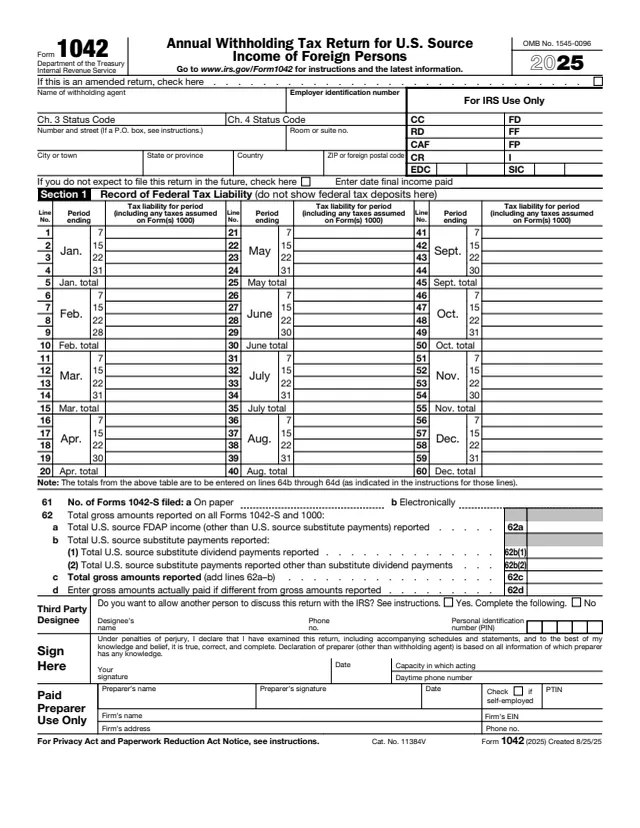
1042
134 fields, 2 pages
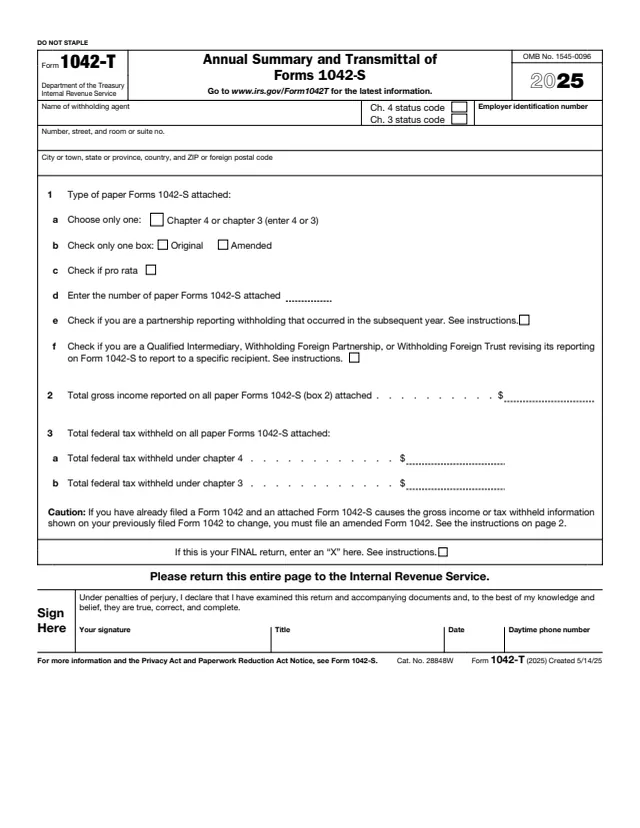
1042-T
19 fields, 2 pages
8809
32 fields, 2 pages
W-8BEN-E
179 fields, 8 pages
8508
165 fields, 2 pages
1040-NR
171 fields, 2 pages
A withholding agent completes the form. The foreign person or entity that received the income gets the recipient copies.
No tool matches that search.
The withholding agent that paid the income. The instructions say it files Copy A with the IRS and furnishes Copies B, C and D to the recipient.
The form labels Copy B for the recipient's records, Copy C to attach to any federal tax return the recipient files, and Copy D to attach to any state tax return.
The instructions say 2026 Forms 1042-S are due March 15, 2027, for both filing with the IRS and furnishing to recipients, or the next business day if that date falls on a weekend or legal holiday.
The recipient copies say generally yes for nonresident alien individuals and fiduciaries and foreign corporations with U.S. income, except when there was no U.S. trade or business during the year and the tax was fully satisfied by withholding at source.
The instructions allow showing only the last four digits on Copies B, C and D. The recipient's TIN is not truncated on Copy A, and the withholding agent's EIN is not truncated on any copy.
The instructions say the address fields were separated into individual entry boxes, and a chapter 3 exemption code is now required whenever the tax withheld is less than 30%.
The instructions say not to use it for items reported on Form W-2, other than compensation for dependent personal services for which the beneficial owner is claiming treaty benefits.