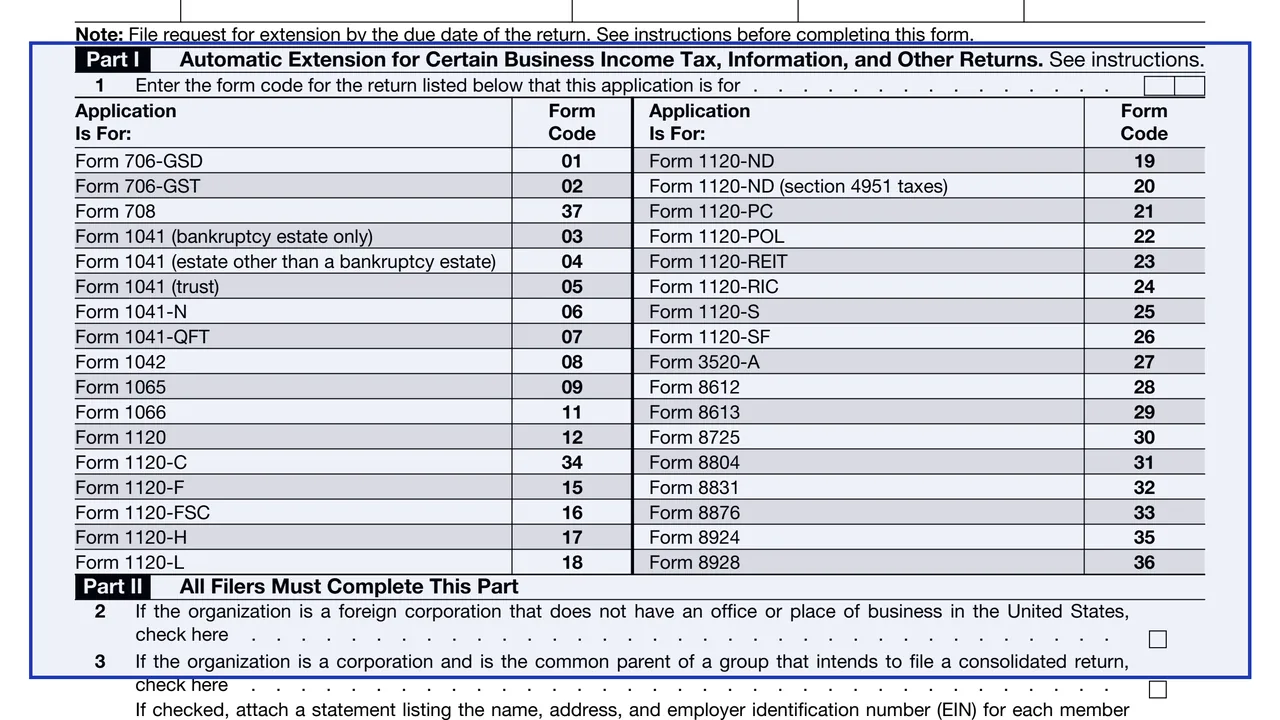
Name, identifying number and address
The entity's name, identifying number, street address, room or suite number, city, state or province, country and ZIP or foreign postal code.
7004
Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns
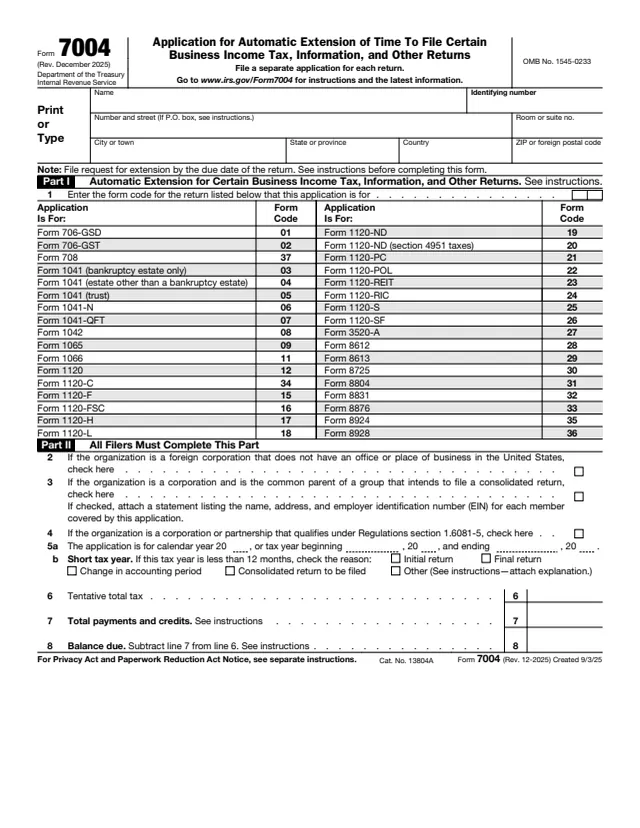
Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns, is an IRS form. The IRS About page says to use it to request an automatic 6-month extension of time to file certain business income tax, information, and other returns. Part I lists a two-digit form code for each return it covers, from Form 706-GS(D) and Form 1041 to Form 1065, Form 1120, Form 1120-S and Form 8928.
The instructions say the extension will be granted if Form 7004 is completed properly, the tax is properly estimated (if applicable), the form is filed by the due date of the return, and any tax due is paid. Form 7004 does not extend the time to pay any tax due. No signature is required, and a separate Form 7004 is filed for each return. It cannot be used for Form 1041-A; the instructions point to Form 8868 instead.
You can fill out Form 7004 free in your browser on this page and download it without an account.
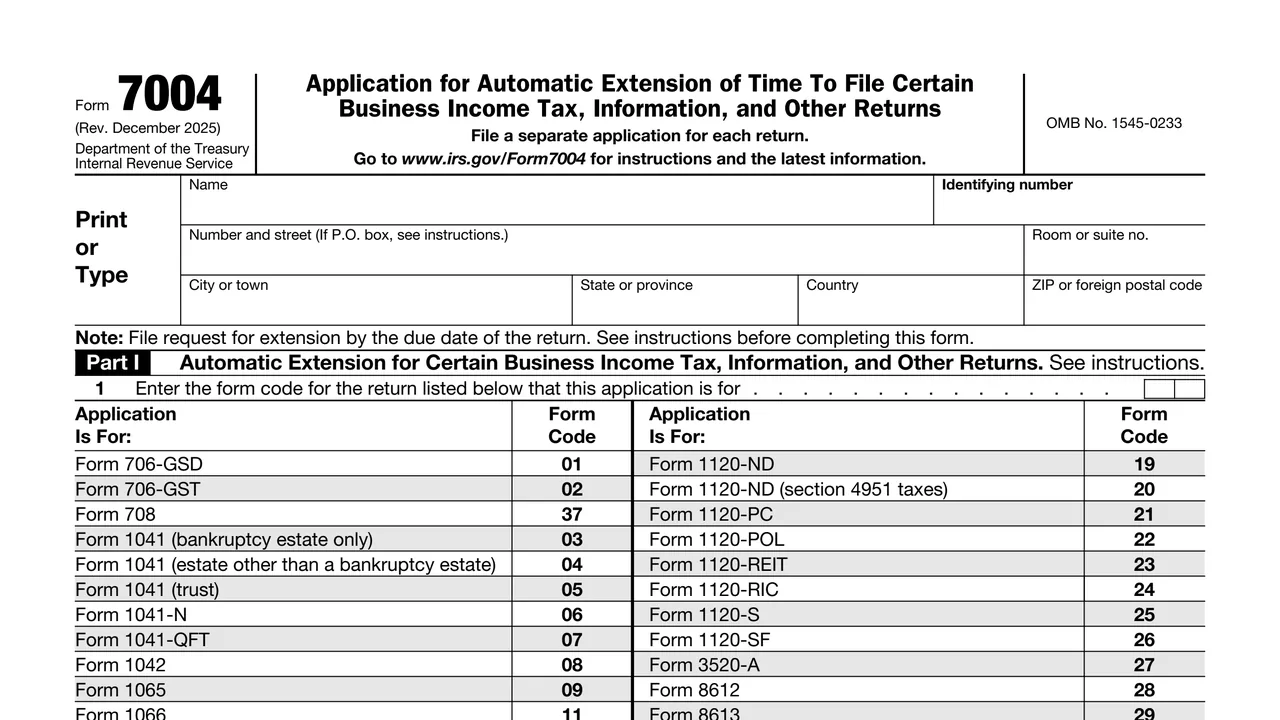
The entity's name, identifying number, street address, room or suite number, city, state or province, country and ZIP or foreign postal code.
A two-digit code for the return the application is for, chosen from the table of returns printed on the form.
Boxes for a foreign corporation with no office or place of business in the United States, and for the common parent of a group that intends to file a consolidated return.
A box for a corporation or partnership that qualifies under Regulations section 1.6081-5.
The calendar year or tax year dates, and boxes for the reason for a short tax year: initial return, final return, change in accounting period, consolidated return to be filed, or other.
Tentative total tax, total payments and credits, and the balance due.
Enter the EIN or SSN. The instructions say that if the name changed, enter the name as on the previous year's return, and that a name or number that does not match IRS records means no valid extension.
Include the suite or room number. For a foreign address, enter city, province or state, and country without abbreviating the country. A new address here does not update IRS records; the instructions point to Form 8822 or Form 8822-B.
Enter the form code for the return, for example 09 for Form 1065, 12 for Form 1120 or 25 for Form 1120-S.
Check any box on lines 2, 3 and 4 that applies. On line 5a, enter the tax year dates if not a calendar year, and on line 5b check the reason for a short tax year.
Line 6 is the total tax, including nonrefundable credits, the entity expects to owe; the instructions say to enter -0- if zero. Line 7 is total payments and refundable credits. Line 8 subtracts line 7 from line 6.
File by the due date of the return, electronically or on paper at the address in the Where To File table, and pay any balance due by that date.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 7004 is generally filed on or before the due date of the applicable return, which is given in that return's instructions.
Form 7004 can be filed electronically for most returns, but not for Forms 8612, 8613, 8725, 8831, 8876 or 706-GS(D). Paper filers use the Where To File table, for example Kansas City, MO 64999-0019 or Ogden, UT 84201-0045 depending on the return and location.
Generally 6 months, with exceptions for certain Form 1041 filers and C corporations with tax years ending June 30. The IRS no longer sends approval notices and writes only if the request is disallowed.
Form 7004 does not extend the time to pay. The instructions describe a late payment penalty of ½ of 1% per month, up to 25% of the amount due, and interest on tax not paid by the regular due date.
The instructions say no signature is required on this form.
The instructions caution that if Form 7004 is filed on paper and the return electronically, the return may be processed before the extension is granted, which may result in a penalty notice.
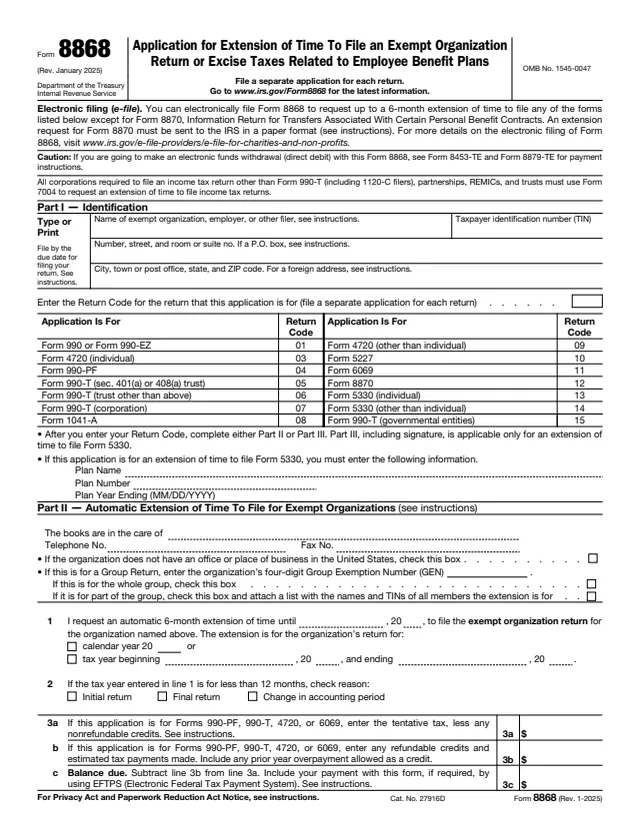
8868
47 fields, 2 pages
8878-A
17 fields, 2 pages
1138
26 fields, 2 pages
1128
166 fields, 5 pages
8822-B
22 fields, 2 pages
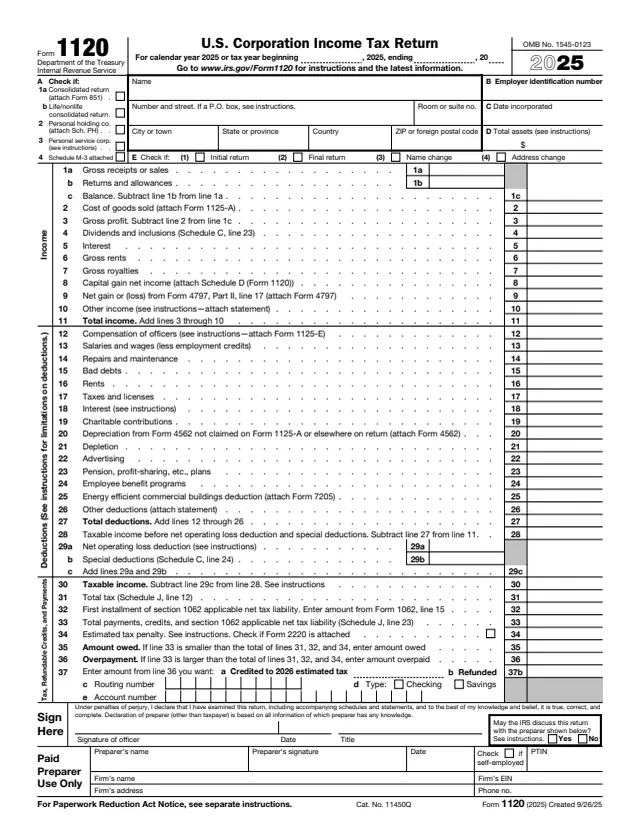
1120
481 fields, 6 pages
The entity that files one of the returns listed in Part I files Form 7004 with the IRS. The form says to file a separate application for each return.
No tool matches that search.
No. The instructions say Form 7004 does not extend the time to pay any tax due. Payment of any balance due on line 8 is generally required by the due date of the return.
The About page describes an automatic 6-month extension. The instructions list exceptions, such as 5½ months for an estate (other than a bankruptcy estate) or trust filing Form 1041.
No. The instructions say no signature is required on this form.
For most returns, yes. The instructions say it cannot be filed electronically for Forms 8612, 8613, 8725, 8831, 8876 or 706-GS(D).
The instructions say the IRS no longer sends a notification that an extension was approved, and notifies the filer only if the request is disallowed.
No. The instructions say to file a separate Form 7004 for each return, and the extension applies only to the return identified on line 1.
No. The instructions say a new address on Form 7004 will not update the record and point to Form 8822 or Form 8822-B.