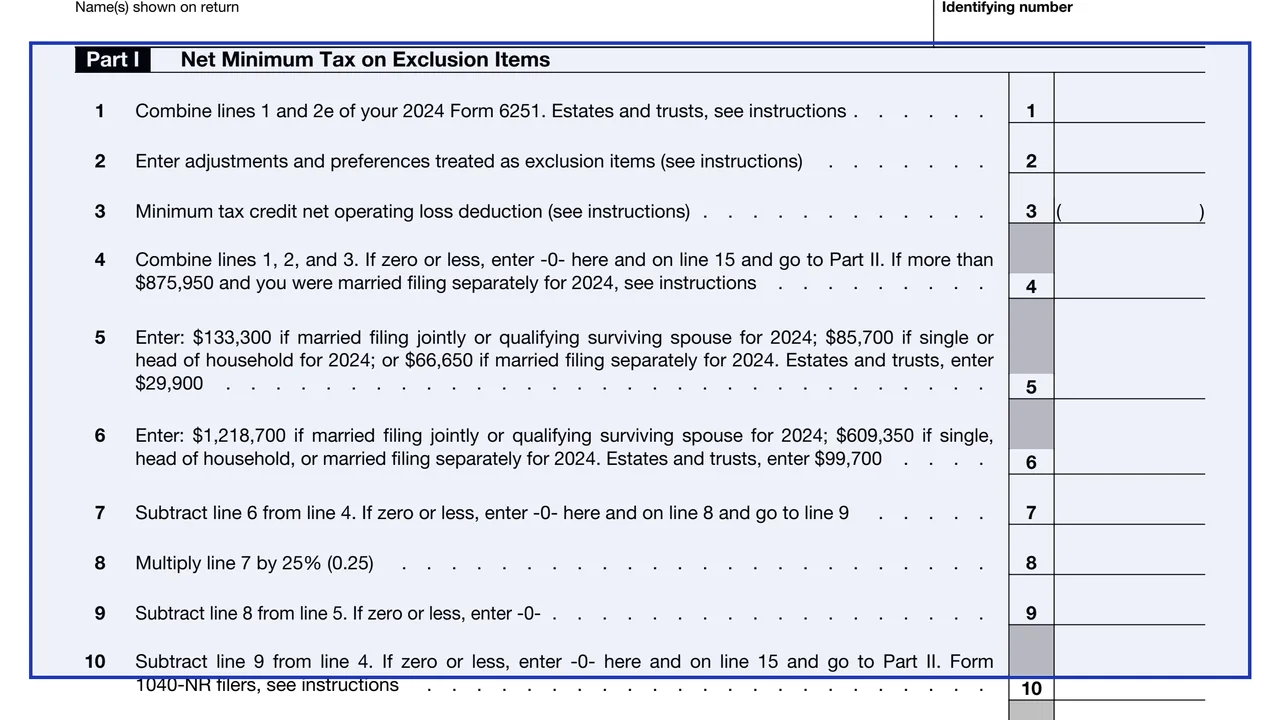
Part I: Net Minimum Tax on Exclusion Items
Lines 1 to 15 figure the net minimum tax on exclusion items, starting from lines 1 and 2e of the 2024 Form 6251 and the exclusion items on line 2.
8801
Credit for Prior Year Minimum Tax—Individuals, Estates, and Trusts
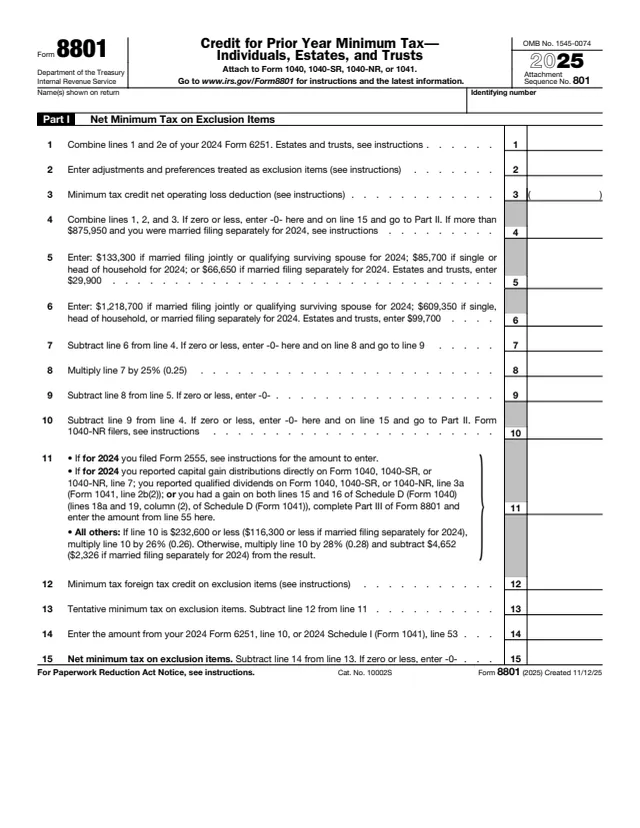
Form 8801 is used by individuals, estates and trusts to figure the minimum tax credit, if any, for alternative minimum tax (AMT) incurred in prior tax years, and to figure any credit carryforward to the next year. This page covers the 2025 form, which looks back at 2024 AMT figures and carries any unused credit to 2026. The form says to attach it to Form 1040, 1040-SR, 1040-NR, or 1041.
The instructions explain that the AMT comes from two types of adjustments and preferences: deferral items, such as depreciation, and exclusion items, such as the standard deduction. The credit is allowed only for the AMT caused by deferral items, so Part I first takes out the minimum tax on exclusion items.
The instructions say to file Form 8801 only if line 21 is more than zero. You can fill out Form 8801 free in your browser on this page and download the result without an account.
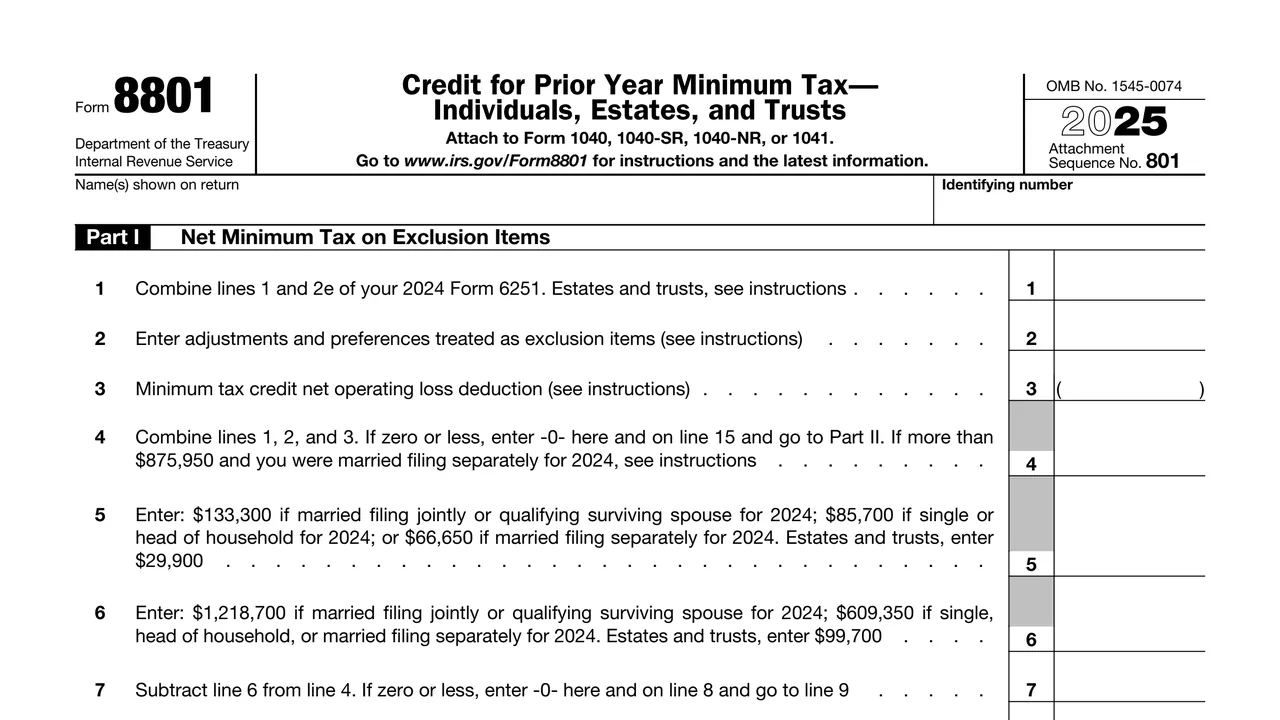
Lines 1 to 15 figure the net minimum tax on exclusion items, starting from lines 1 and 2e of the 2024 Form 6251 and the exclusion items on line 2.
The form prints the amounts by 2024 filing status. Line 5 is $133,300 for married filing jointly or qualifying surviving spouse, $85,700 for single or head of household, $66,650 for married filing separately and $29,900 for estates and trusts.
Most filers multiply line 10 by 26% or 28%, using the $232,600 cutoff ($116,300 if married filing separately). Filers with capital gains or qualified dividends use Part III, and Form 2555 filers use a worksheet in the instructions.
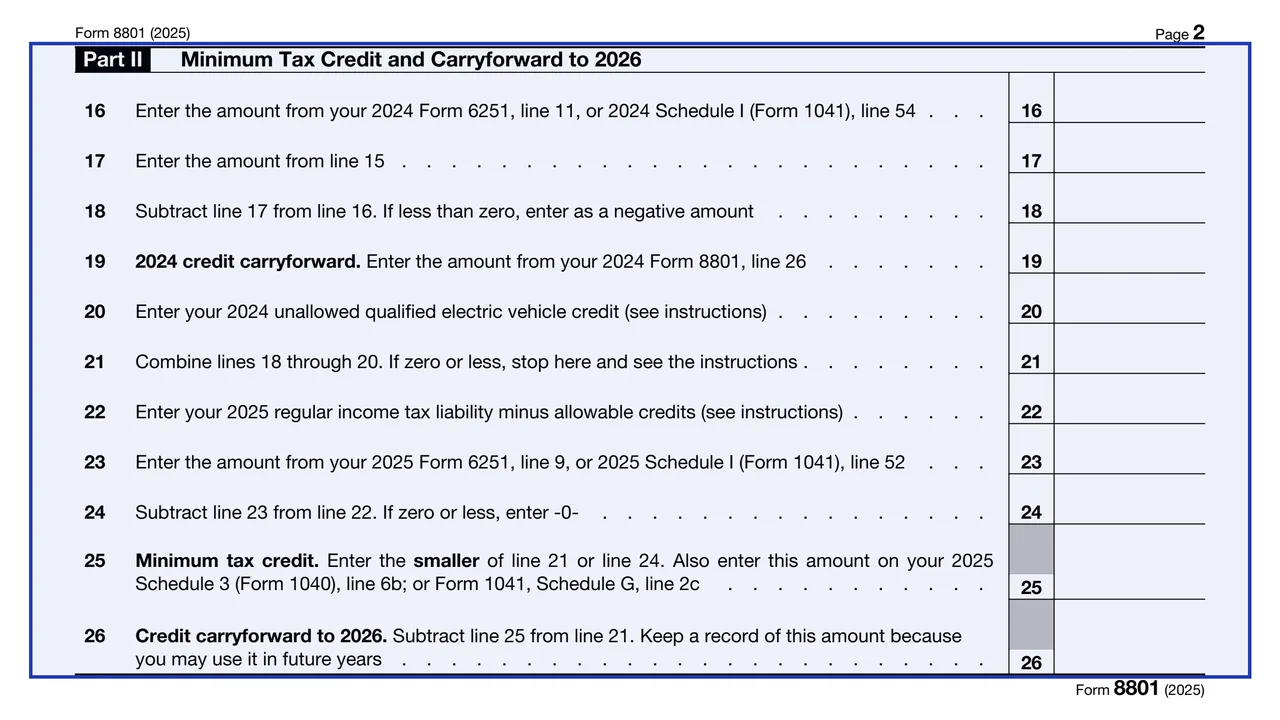
Lines 16 to 26 combine the 2024 AMT, the 2024 carryforward and any unallowed electric vehicle credit, then limit the credit to the 2025 regular tax minus the 2025 Form 6251, line 9 amount.
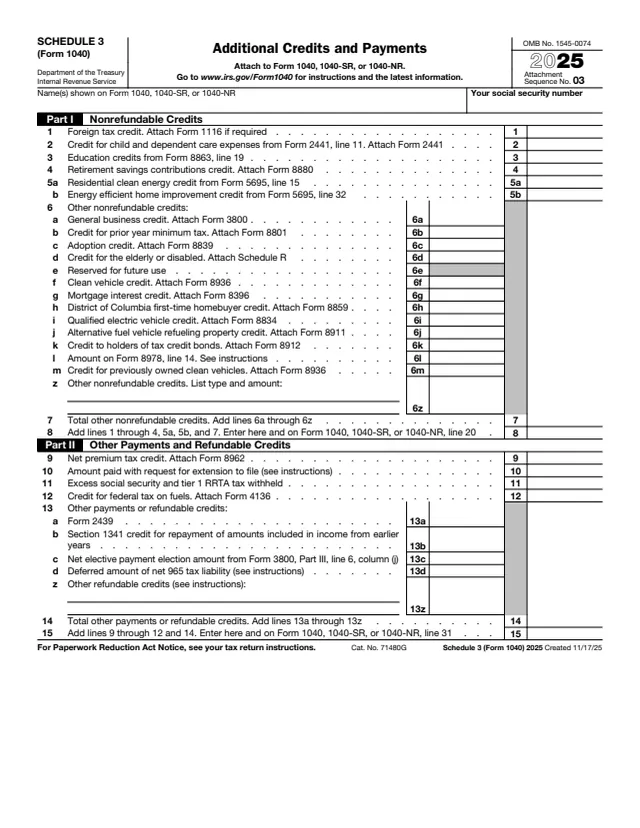
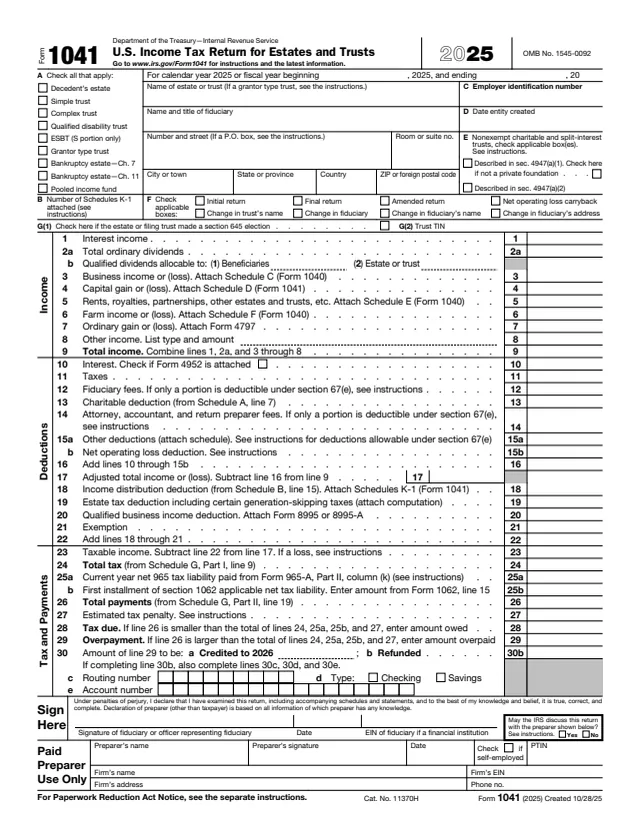
Line 25 is the minimum tax credit, which the form says also goes on 2025 Schedule 3 (Form 1040), line 6b, or Form 1041, Schedule G, line 2c. Line 26 is the carryforward to 2026.
Lines 27 to 55 figure the line 11 amount with the 15%, 20% and 25% rates printed on lines 46, 49 and 52. The form says to complete it only if line 11 or the Foreign Earned Income Tax Worksheet requires it.
The lines pull from the 2024 return: Form 6251 or Schedule I (Form 1041), the 2024 Form 8801, and the 2024 capital gain worksheets or Schedule D, as each line names.
Individuals combine lines 1 and 2e of the 2024 Form 6251, add the exclusion items on line 2 and subtract the minimum tax credit net operating loss deduction on line 3. Estates and trusts follow the line 1 instructions instead.
Enter the exemption and phaseout amounts printed for the 2024 filing status, figure the tax on exclusion items on line 11, subtract any minimum tax foreign tax credit on line 12, then enter the 2024 Form 6251, line 10 amount on line 14 and subtract it on line 15.
Enter the 2024 Form 6251, line 11 amount, subtract line 15, then add the 2024 carryforward and any unallowed electric vehicle credit. The form says if line 21 is zero or less, stop and see the instructions.
Line 22 is the 2025 regular tax minus allowable credits, figured as the line 22 instructions describe for Form 1040 or Form 1041. The credit on line 25 is the smaller of line 21 or line 24, and line 26 keeps the rest for 2026.
Complete lines 27 to 55 only when line 11 sends you there, then enter line 55 on line 11. Form 2555 filers enter it on line 4 of the Foreign Earned Income Tax Worksheet instead.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR, 1040-NR, or 1041. Its attachment sequence number is 801.
The instructions say to file Form 8801 only if line 21 is more than zero.
Line 25 also goes on 2025 Schedule 3 (Form 1040), line 6b, or Form 1041, Schedule G, line 2c.
The form says to keep a record of the line 26 amount because it may be used in future years.
The instructions say not to attach a worksheet Schedule I (Form 1041) or the MTFTCE Forms 1116 used for line 12. Keep them for your records.
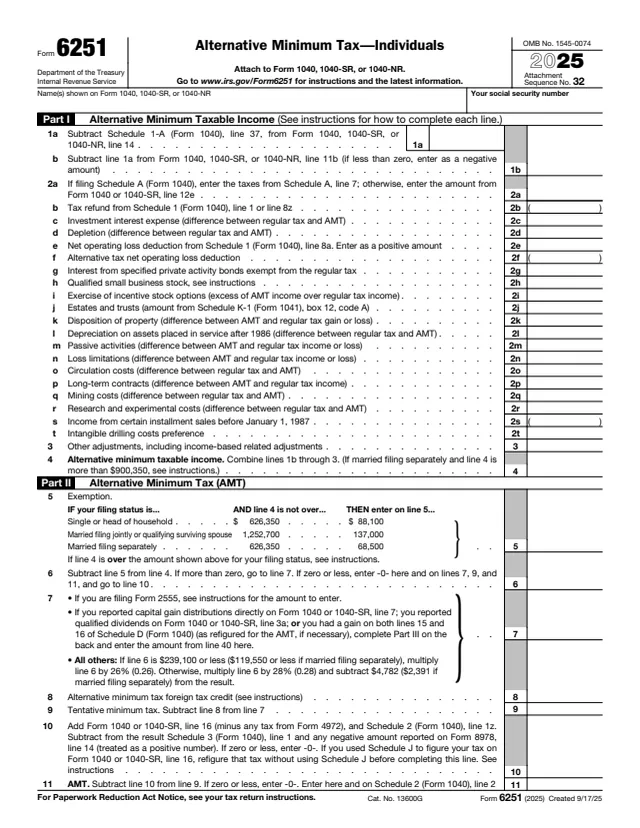
6251
62 fields, 2 pages
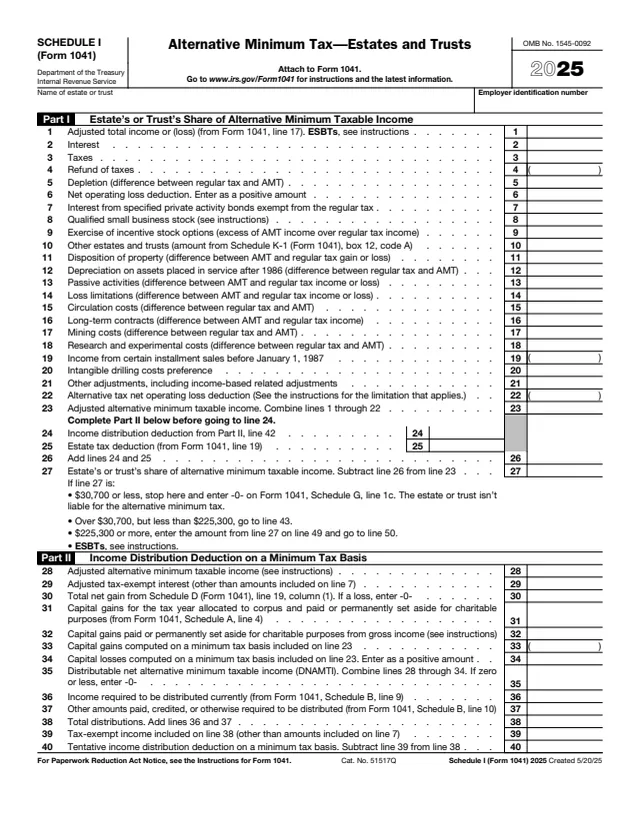
1041
85 fields, 3 pages
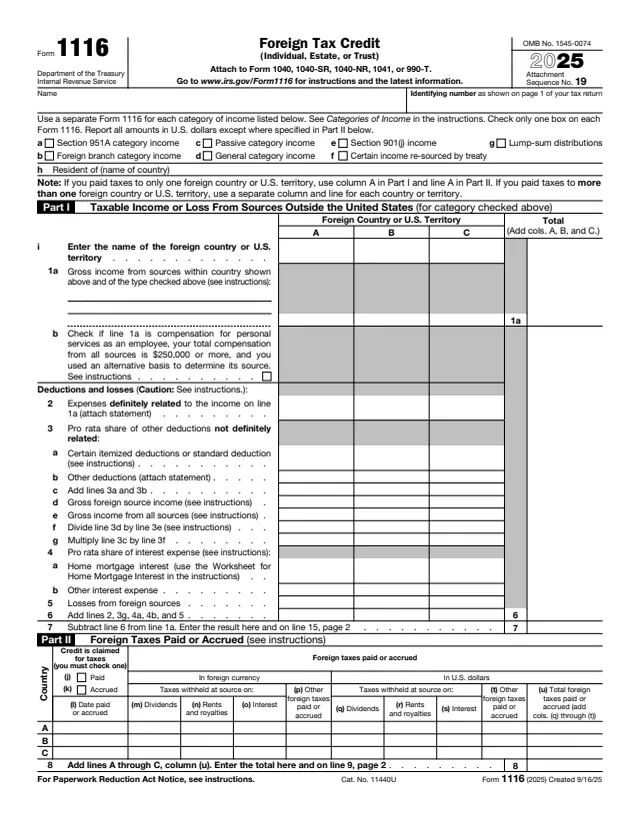
1116
118 fields, 2 pages
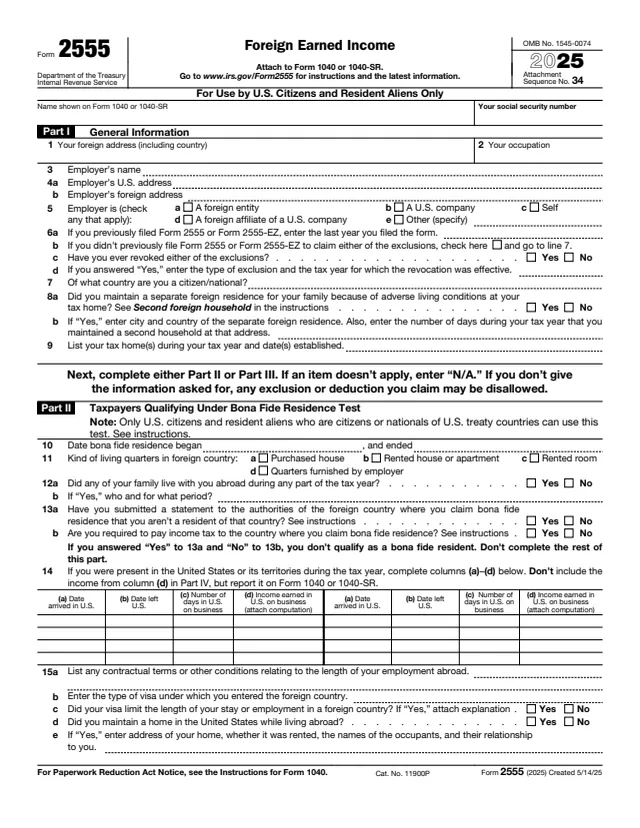
2555
160 fields, 3 pages
1040
37 fields, 1 page
1041
173 fields, 3 pages
The instructions list three situations, all based on the 2024 tax year, for an individual, estate or trust.
No tool matches that search.
The instructions say it figures the minimum tax credit, if any, for AMT incurred in prior tax years, and any credit carryforward to 2026.
Individuals, estates and trusts that for 2024 had AMT with adjustments or preferences other than exclusion items, a credit carryforward from the 2024 Form 8801, or an unallowed qualified electric vehicle credit.
The instructions say the minimum tax credit is allowed only for AMT caused by deferral items, such as depreciation. Exclusion items, such as the standard deduction, do not earn a credit.
When line 21 is zero or less. The instructions say there is then no credit or carryforward, so the rest of the form is not completed or filed.
The form says to enter line 25 on 2025 Schedule 3 (Form 1040), line 6b, or on Form 1041, Schedule G, line 2c.
It is the line 26 carryforward to 2026. The form says to keep a record of it because it may be used in future years.