Filer, student and service provider details
The filer's name, address, information contact telephone number and EIN, the student's TIN, name and permanent address, and a box for a service provider or account number.
1098-T
Tuition Statement
Form 1098-T is the tuition statement. The IRS page says eligible educational institutions file it for each student they enroll and for whom a reportable transaction is made, and insurers file it for each person to whom they made reimbursements or refunds of qualified tuition and related expenses. The filer sends Copy A to the IRS and gives Copy B to the student.
Copy B says the form is used to complete Form 8863 to claim education credits, and tells the student to give it to a tax preparer or use it to prepare the return. Box 1 shows payments received for qualified tuition and related expenses, and box 5 shows scholarships or grants the school administered and processed.
The current PDF is the 2026 form, for amounts in calendar year 2026. The PDF notes that the IRS releases information returns up to a year before they are filed. You can fill out Copy B free on this page.
The filer's name, address, information contact telephone number and EIN, the student's TIN, name and permanent address, and a box for a service provider or account number.
Total payments received from all sources for qualified tuition and related expenses, less refunds made in the same year. The instructions say it is not reduced by scholarships in box 5.
Boxes 2 and 3 are reserved for future use. Box 4 shows adjustments made for a prior year to tuition amounts reported on an earlier Form 1098-T.
Box 5 is the total scholarships or grants the school administered and processed during the year. Box 6 shows reductions to scholarships or grants reported for a prior year.
Box 7 marks payments for an academic period beginning January to March 2027. Box 8 marks an at least half-time student, and box 9 a graduate student.
For insurers: the total reimbursements or refunds of qualified tuition and related expenses made to the student during 2026.
Form W-9S can be used to ask for it, but the instructions say it is optional: admission or enrollment forms and financial aid applications also work. A checkbox shows whether the TIN was asked for in writing.
Give the telephone number of an administrative office that can answer questions, not the general number, and the student's permanent address.
Report all payments received during the year for qualified tuition and related expenses, less refunds of those payments made in the same year.
Enter prior-year tuition adjustments in box 4, scholarships or grants in box 5, and prior-year scholarship reductions in box 6.
Check each box that applies: payments for a term starting January to March 2027, at least half-time enrollment, and graduate student status.
Copy A goes to the IRS and Copy B to the student, on paper or electronically. The student's TIN may be truncated on Copy B but not on the IRS copy. You can fill this form free on this page.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions point to Pub. 1099, General Instructions for Certain Information Returns, for when and where to file and for statements to recipients.
The instructions say the e-file threshold is 10 information returns in total, for returns filed on or after January 1, 2024. The IRS IRIS portal is one way to e-file.
The PDF says Copy A printed from it can't be scanned and a penalty may apply for filing it. Official scannable forms can be ordered at IRS.gov/EmployerForms.
The instructions say a school may offer consent to receive Form 1098-T electronically as part of a global consent to do business electronically that meets the regulations.
The instructions say room, board, insurance, medical expenses including student health fees, and transportation are not qualified tuition and related expenses.
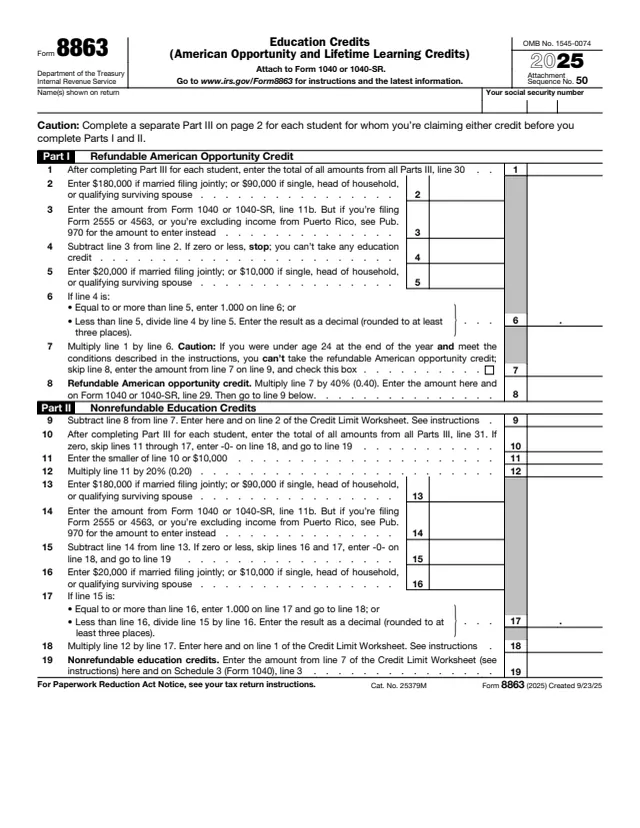
8863
77 fields, 2 pages
1098-E
43 fields, 4 pages
1040
37 fields, 1 page

1040
199 fields, 2 pages
W-9S
13 fields, 2 pages
1096
55 fields, 3 pages
No tool matches that search.
The school files Copy A with the IRS. Copy B says to keep it for your records, use it to complete Form 8863 for education credits, and give it to a tax preparer or use it to prepare the return.
The instructions list cases where a school doesn't file one, such as courses with no academic credit, nonresident alien students unless they ask, and expenses entirely waived or paid with scholarships.
Both are reserved for future use on the 2026 form.
No. The instructions say charges for room, board, insurance, medical expenses, transportation and similar personal costs are not qualified tuition and related expenses.
It means box 1 includes payments for an academic period that begins January to March 2027. Copy B points to Pub. 970 for how to report these amounts.
Copy B says not to contact the school or its service provider for explanations of the credit rules. It points to Pub. 970, Form 8863 and the Instructions for Form 1040.