Filer information
Filer's name, street address with room or suite number, city, state or province, country and ZIP or foreign postal code, plus a contact name, telephone, email and fax number.
1096
Annual Summary and Transmittal of U.S. Information Returns
Form 1096 is the cover sheet a filer sends to the IRS with paper information returns. The IRS says to use it to transmit paper Forms 1097, 1098, 1099, 3921, 3922, 5498 and W-2G. It carries the filer's name, address and taxpayer identification number, the number of forms in the package, the total federal income tax withheld and the total amount reported on them.
The form is for paper filing only. The About page says not to use it to transmit electronically, and points to Publication 1220 for electronic submissions. Each Form 1096 covers one type of return, marked with an X in box 6.
The PDF on irs.gov is the 2026 form. Its cover page says the downloaded copy is for information only and is not scannable, and that official forms for filing can be ordered at www.IRS.gov/orderforms. You can fill out the PDF free in your browser on this page and download it without an account.
Filer's name, street address with room or suite number, city, state or province, country and ZIP or foreign postal code, plus a contact name, telephone, email and fax number.
Box 1 holds the employer identification number and box 2 the Social Security number. The form says to enter the TIN in one box, not both.
Box 3 is the total number of forms sent, box 4 the federal income tax withheld on them, and box 5 the total amount reported with this Form 1096.
A grid of form types from W-2G and 1097-BTC through 1099-SB, 3921, 3922 and the 5498 series, each with a two-character code. Only one box is marked.
A declaration under penalties of perjury that the return and accompanying documents are true, correct and complete, with signature, title and date.
The form says these must be the same as those entered in the upper left area of the Forms 1097, 1098, 1099, 3921, 3922, 5498 or W-2G being sent, including room, suite or other unit number.
Enter the TIN in one box only. The form says to use the same EIN or SSN on Form 1096 that is used on the form marked in box 6.
Enter the number of correctly completed forms, not pages. Leave out blank or voided forms and the Form 1096. The form's example: two completed Forms 1098-E on one three-to-a-page sheet means entering 2.
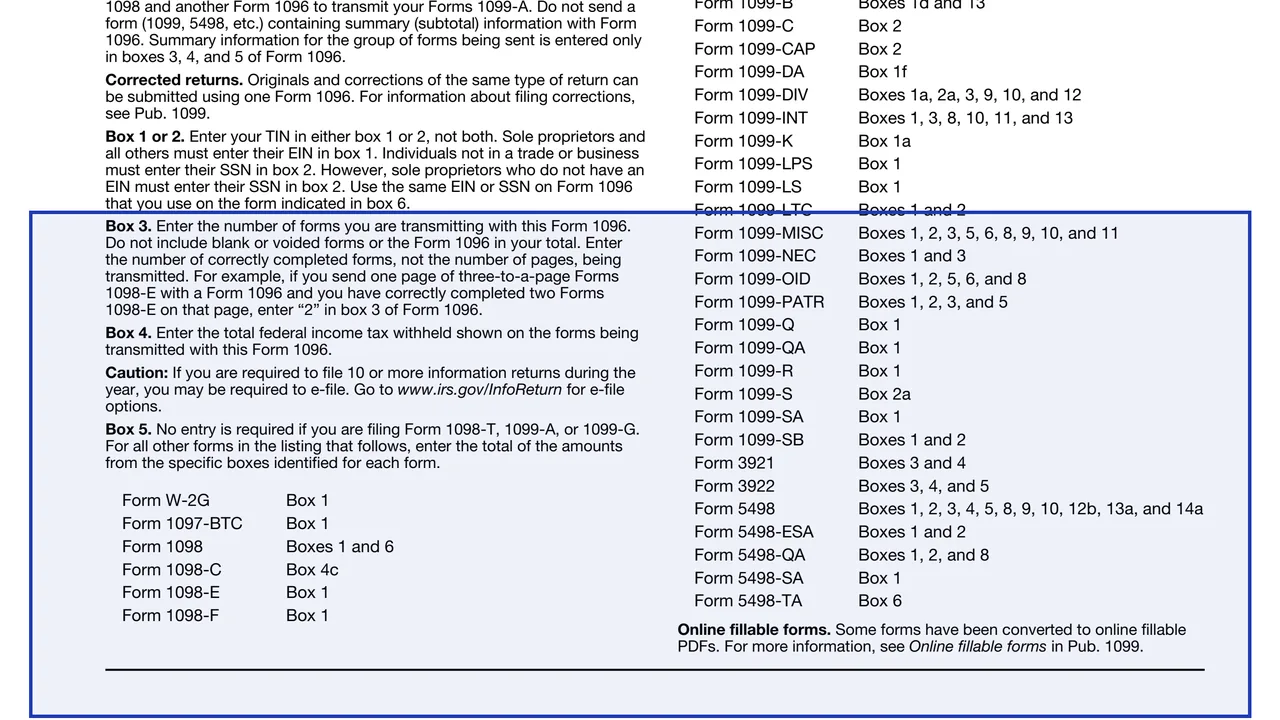
Box 4 is the total federal income tax withheld on the forms sent. Box 5 adds the boxes listed on page 2 for each form type, for example boxes 1 and 3 of Form 1099-NEC. No box 5 entry for Forms 1098-T, 1099-A or 1099-G.
Enter an X in only one box to show the type of form being filed. A batch of a different form type needs its own Form 1096.
Sign under penalties of perjury and add a title and date before sending the whole page to the IRS.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The address depends on the state of the principal business, office or agency, or legal residence for an individual: Internal Revenue Service, P.O. Box 149213, Austin, TX 78714-9213; Internal Revenue Service Center, P.O. Box 219256, Kansas City, MO 64121-9256; or Internal Revenue Service Center, 1973 North Rulon White Blvd., Ogden, UT 84201. Filers outside the United States use the Austin address.
With Forms 1097, 1098, 1099, 3921, 3922 or W-2G, file by February 28. With Forms 1099-NEC, by January 31. With Form 1099-LPS, by February 1. With Forms 5498, by May 31. A due date on a weekend or legal holiday moves to the next business day.
The form says to group the forms by form number and send each group with a separate Form 1096. Originals and corrections of the same type of return can go with one Form 1096.
Return the entire page; photocopies are not acceptable. Send it with the copies of the form checked in box 6 in a flat mailer, not folded, and do not staple.
The cover page says the copy printed from irs.gov is not scannable and a penalty may be imposed for filing forms that cannot be scanned. Official forms can be ordered at www.IRS.gov/orderforms.
Do not send a form containing summary or subtotal information with Form 1096. Summary information goes only in boxes 3, 4 and 5.
The form says any person or entity who files any form checked in box 6 must file Form 1096 to transmit those forms to the IRS. It goes to the IRS, not to the people who received the information returns.
No tool matches that search.
No. The About page says to use it to transmit paper forms and not to use it to transmit electronically. Publication 1220 covers electronic submissions.
The cover page says not to print and file a Form 1096 downloaded from the website, because that copy is not scannable. Official scannable forms can be ordered at www.IRS.gov/orderforms.
No. The form says to group the forms by form number and send each group with a separate Form 1096, and to mark only one box in box 6.
The number of correctly completed forms being sent, not the number of pages. Blank or voided forms and the Form 1096 itself are not counted.
It depends on the forms it covers: January 31 with Forms 1099-NEC, February 1 with Form 1099-LPS, February 28 with Forms 1097, 1098, 1099, 3921, 3922 or W-2G, and May 31 with Forms 5498.
Yes. The form says originals and corrections of the same type of return can be submitted using one Form 1096, and points to Pub. 1099 for more on corrections.