Page 1: firm and worker
The firm's name, mailing address, trade name, fax, website, phone and EIN, and the worker's name, address, phones, fax, SSN and EIN if any, plus a note for a separate payer.
SS-8
Determination of Worker Status for Purposes of Federal Employment Taxes and Income Tax Withholding (Spanish Version)
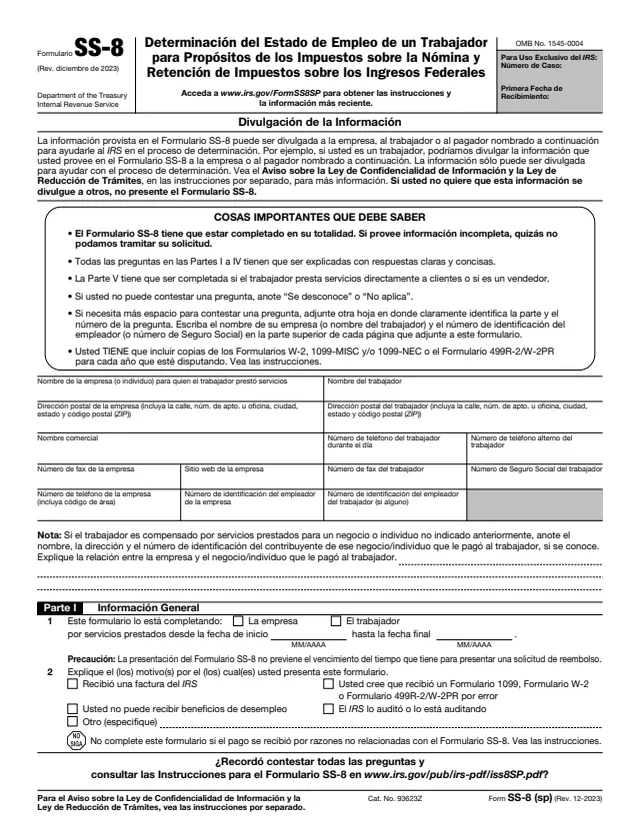
Form SS-8 (sp) is the Spanish version of Form SS-8, Determination of Worker Status for Purposes of Federal Employment Taxes and Income Tax Withholding. The five-page PDF is titled "Determinación del Estado de Empleo de un Trabajador para Propósitos de los Impuestos sobre la Nómina y Retención de Impuestos sobre los Ingresos Federales" and is written in Spanish, for firms and workers who read Spanish. It is dated diciembre de 2023 (Rev. 12-2023).
The IRS About page says firms and workers file Form SS-8 to request a determination of the status of a worker, that is, whether the services provided to the firm are those of an employee or an independent contractor. The Spanish form points to www.irs.gov/FormSS8SP and to Spanish instructions at www.irs.gov/pub/irs-pdf/iss8SP.pdf.
A disclosure note on page 1 says information on the form may be shared with the firm, the worker or the payer named on it, and that if you do not want it shared, do not file Form SS-8. The English edition, Form SS-8, has its own page. You can fill out this Spanish PDF free in your browser on this page and download it without an account.
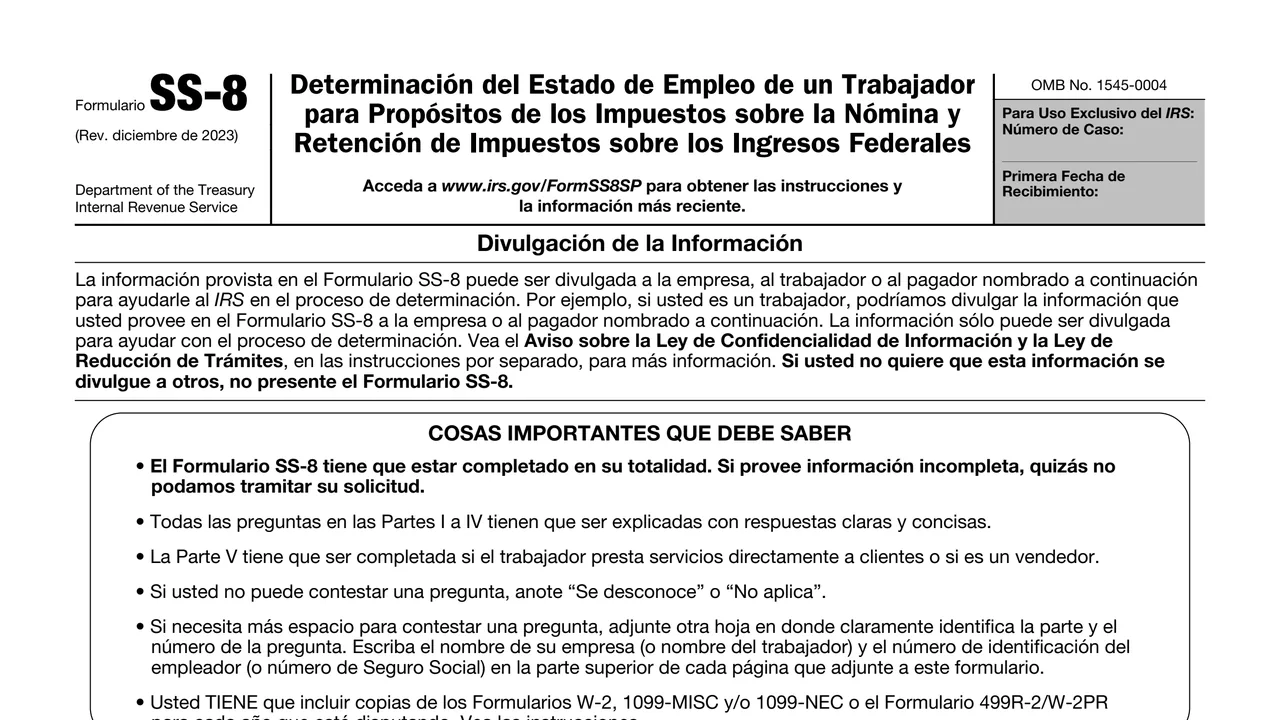
The firm's name, mailing address, trade name, fax, website, phone and EIN, and the worker's name, address, phones, fax, SSN and EIN if any, plus a note for a separate payer.
Who completes the form and the service dates, the reason for filing, number of similar workers, how the job was obtained, documents, litigation, the firm's business, the worker's title and duties, and any written or oral agreement.
Training and instructions, who assigns the work and sets the methods, reports, schedule, where the work is done, meetings, and whether the worker can hire substitutes or helpers.
Supplies and equipment, leases, expenses and reimbursements, type of pay, advances, who the customer pays, workers' compensation insurance, risk of loss, and who sets the rate and the price.
Benefits, ending the relationship without penalty, similar work for others, noncompete agreements, advertising, home assembly, how the worker is introduced to customers, and how the work ended.
Leads, reporting, terms of sale, order approval, sales routes, paying for a route or territory, where products are sold, insurance sales and merchandise for resale, then the signature.
The form says it has to be completed in full and that the IRS may not be able to process incomplete information. Parts I to IV need clear and concise answers.
If you cannot answer a question, the form says to enter "Se desconoce" (unknown) or "No aplica" (does not apply).
Attach another sheet that names the part and question number, with the firm's name (or worker's name) and EIN (or SSN) at the top of each page.
Include copies of Forms W-2, 1099-MISC and/or 1099-NEC or Form 499R-2/W-2PR for each year in dispute, plus supporting documents such as contracts, invoices and memos.
Complete Part V when the worker provides services directly to customers or is a salesperson.
Print your name, sign and date under penalties of perjury. The last page asks whether you signed and attached copies of your W-2, 499R-2/W-2PR or 1099 for each year in dispute.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions give Internal Revenue Service, Form SS-8 Determinations, P.O. Box 630, Stop 631, Holtsville, NY 11742-0630.
The instructions say the completed and signed form and attachments can be faxed to 855-242-4481.
The instructions say not to submit Form SS-8 with a tax return, as that delays processing, and not to delay filing a return while waiting for a determination.
The instructions say there is no fee for requesting a Form SS-8 determination letter.
The form says filing it does not prevent the expiration of the time to file a claim for refund. The instructions describe a protective claim on Form 1040-X.
The instructions say the taxpayer signs and dates it, and that a stamped signature or a power of attorney representative's signature is not accepted.
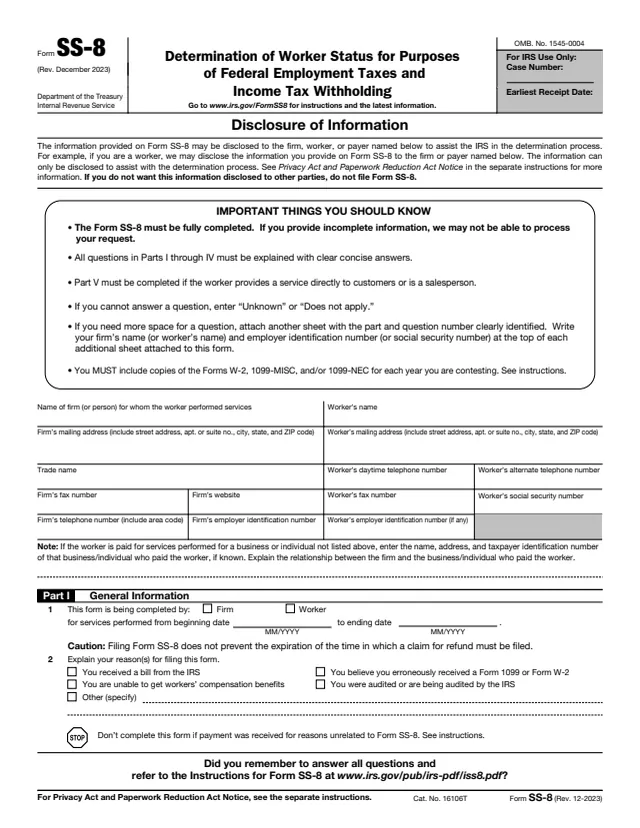
SS-8
299 fields, 5 pages
W-2
568 fields, 11 pages
1099-MISC
179 fields, 6 pages
1099-NEC
140 fields, 6 pages
1040-X
166 fields, 2 pages
Line 1 asks whether the firm or the worker is completing the form. The completed form goes to the IRS.
No tool matches that search.
Spanish. Every question on the five pages is in Spanish, and the form points to Spanish instructions at www.irs.gov/pub/irs-pdf/iss8SP.pdf. This page about it is in English.
Yes. The English edition is Form SS-8, which has its own page.
The disclosure note says the information may be shared with the firm, the worker or the payer named on the form to help the determination, and that if you do not want it shared, do not file Form SS-8.
The form says to enter "Se desconoce" (unknown) or "No aplica" (does not apply).
The instructions say there is no fee for requesting a Form SS-8 determination letter.
Copies of Forms W-2, 1099-MISC and/or 1099-NEC, or Form 499R-2/W-2PR, for each year in dispute.