Part I: All Filers
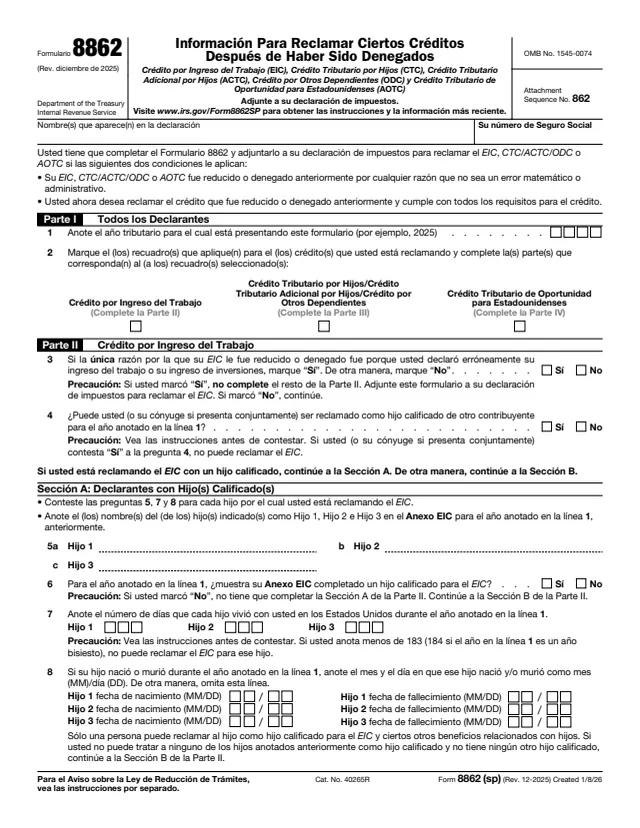
Line 1 is the tax year the form is filed for, with 2022 as the printed example. Line 2 has three boxes: EIC, CTC (nonrefundable or refundable)/ACTC/ODC, and AOTC.
8862
Information To Claim Certain Credits After Disallowance (Chinese Traditional Version)
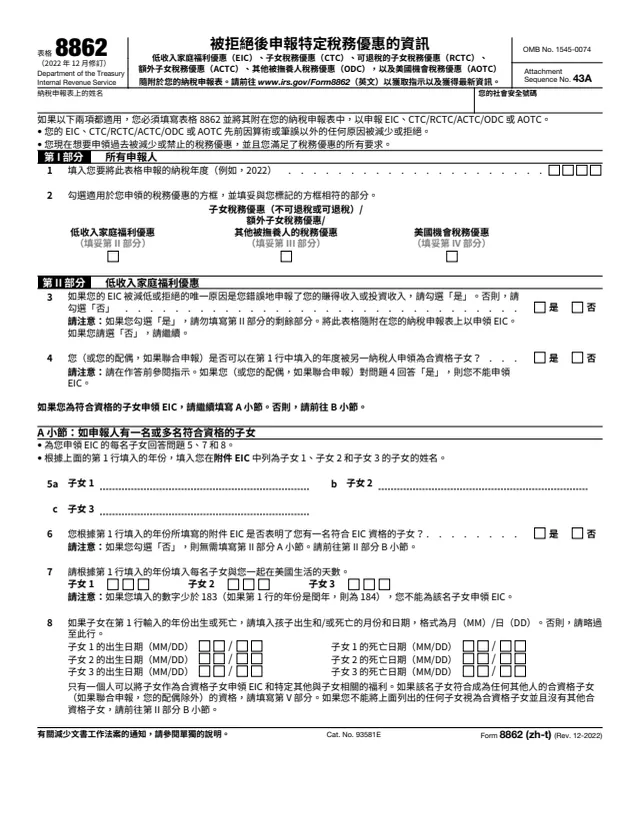
Form 8862 (zh-t) is the Chinese (Traditional) version of Form 8862, Information To Claim Certain Credits After Disallowance, in its December 2022 revision. The questions, notes and part headings are in Traditional Chinese. The English edition is Form 8862, which the IRS now lists in a December 2025 revision.
This edition names six credits: the earned income credit (EIC), child tax credit (CTC), refundable child tax credit (RCTC), additional child tax credit (ACTC), credit for other dependents (ODC) and American opportunity tax credit (AOTC). It says to complete it and attach it to the tax return when two things apply: one of these credits was earlier reduced or disallowed for any reason other than a math or clerical error, and the filer now wants to claim it and meets all of its requirements.
The form has five parts on four pages. It points to www.irs.gov/Form8862, marked as English, for instructions and the latest information. The PDF can be filled out free in the browser on this page and downloaded without an account.
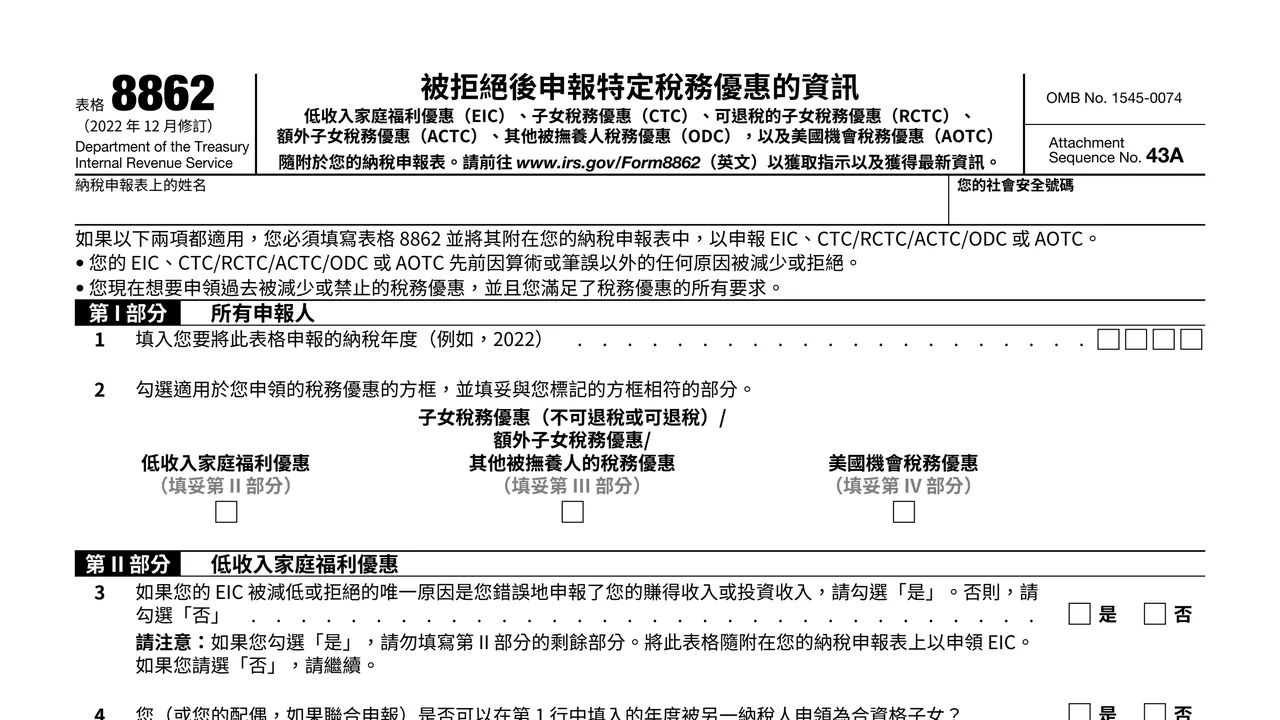
Line 1 is the tax year the form is filed for, with 2022 as the printed example. Line 2 has three boxes: EIC, CTC (nonrefundable or refundable)/ACTC/ODC, and AOTC.
Line 3 asks whether the only reason was misreported earned income or investment income. Line 4 asks whether the filer could be claimed as another taxpayer's qualifying child.
Section A, lines 5 to 8, lists up to three Schedule EIC children with days lived in the United States and any birth or death date. Section B, lines 9 to 11, is for filers without a qualifying child.
Lines 12 and 13 list up to four children and four other dependents. Lines 14 to 17 ask Yes or No about living with the filer, qualifying child status, dependent status and U.S. citizenship, nationality or residence.
Line 18 lists up to three students as named on Form 8863. Line 19 asks whether each was an eligible student and whether the Hope Scholarship Credit or AOTC was claimed in any 4 earlier tax years.
Lines 20 to 22 list each child who could also be another person's qualifying child, the addresses where the filer and child lived, and anyone other than a joint-return spouse or the filer's dependents who lived with the child more than half the year.
Enter the tax year the form is filed for, then check a box for each credit being claimed and complete only the matching parts: Part II for the EIC, Part III for the child credits and ODC, Part IV for the AOTC.
The form says that after a Yes on line 3 the rest of Part II is left blank. It also says a Yes on line 4 means the EIC cannot be claimed.
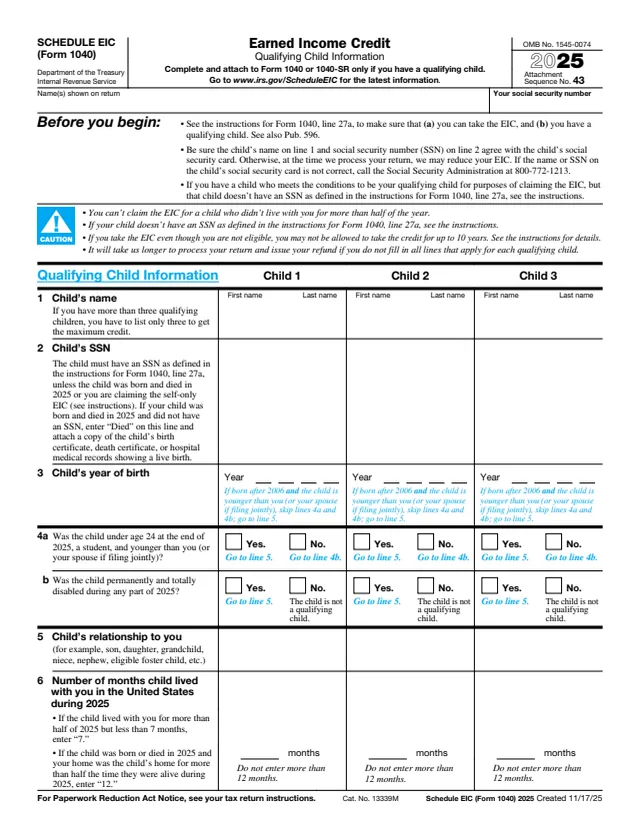
With a qualifying child, enter the Schedule EIC children and the days each lived with the filer in the United States. The form says fewer than 183 days (184 in a leap year) rules out the EIC for that child. Without one, complete lines 9 to 11.
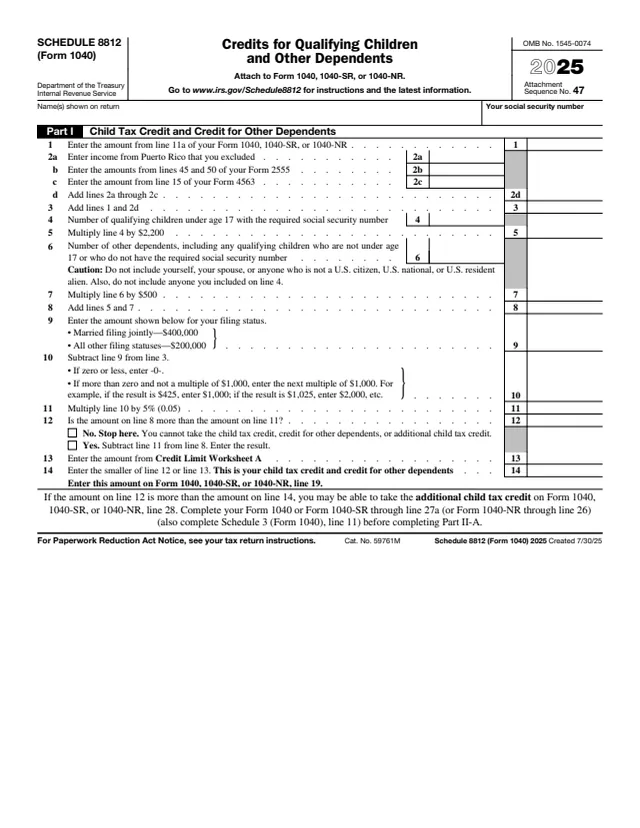
Enter each child and other dependent, then answer lines 14 to 17 for each one. The form says a No to any of those questions means the credit cannot be claimed for that person, and to attach a statement for more than four.
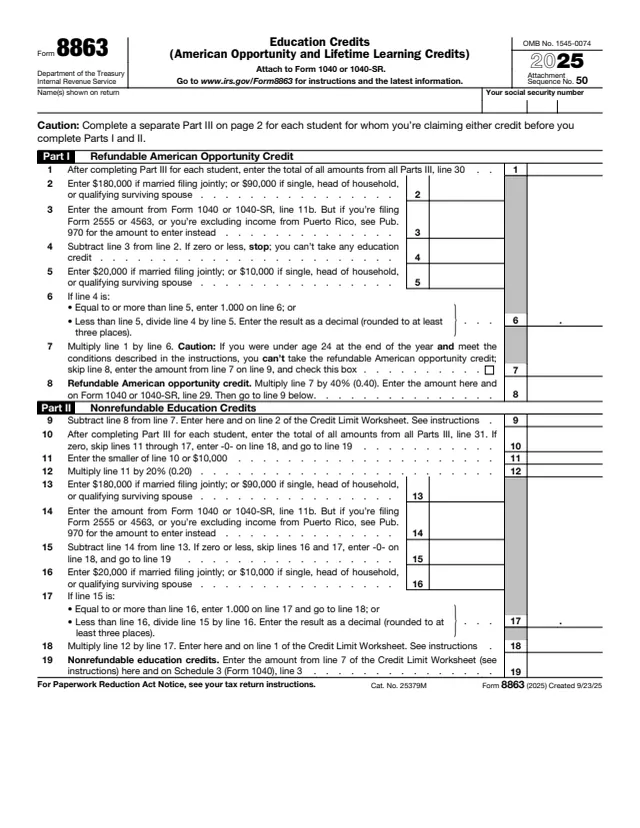
Name each student as listed on Form 8863 and answer lines 19a and 19b. The form says a No on 19a or a Yes on 19b means no credit for that student.
Complete it when a child could also be another person's qualifying child: enter the address shared with each child and anyone else who lived with the child more than half the year. The form says a noncustodial parent entitled to claim the child does not complete Part V.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the tax return. It carries Attachment Sequence No. 43A.
The form points to www.irs.gov/Form8862 and marks the link as English. The instructions posted there are revised 12/2025 and describe Parts I to IV only, so Part V of this edition has no matching section there.
The instructions say to attach a statement to the end of the return with the filer's name and SSN (or ITIN), numbering each entry to match the line number on Form 8862.
The last note on the form says the IRS may ask for additional information to verify eligibility for each credit.
The form says only one person can treat a child as a qualifying child for the EIC and certain other child-related benefits, and points to Publication 501 to decide who.
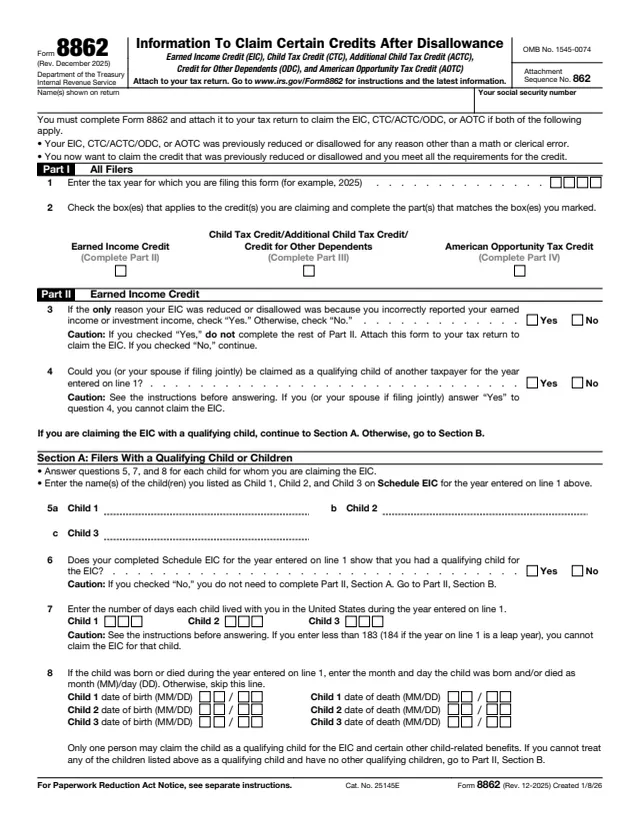
8862
109 fields, 3 pages
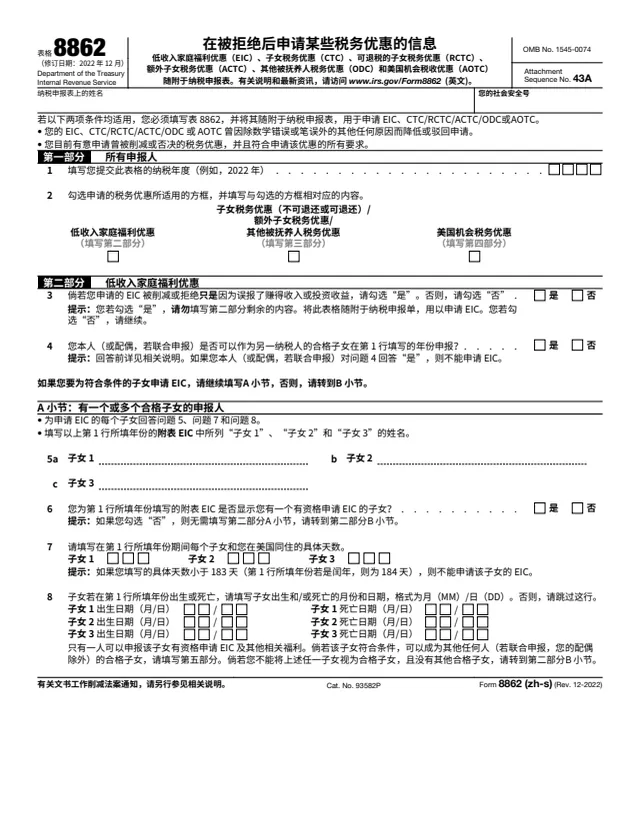
8862
137 fields, 4 pages
8862
109 fields, 3 pages
1040
38 fields, 2 pages
8863
77 fields, 2 pages
1040
41 fields, 2 pages
An individual taxpayer completes it and attaches it to their own tax return, which goes to the IRS.
No tool matches that search.
Traditional Chinese. It is the IRS Chinese (Traditional) version of Form 8862. The English edition is Form 8862, and Form 8862 (zh-s) is the Simplified Chinese version.
Rev. 12-2022, printed on every page. The English Form 8862 is listed in a December 2025 revision, so this edition is older and still has a Part V.
The refundable child tax credit, named on this edition next to the CTC. The current instructions say the RCTC was only available for 2021.
No. The form says to attach it to the tax return on which the credit is claimed.
Line 3 covers that case. The form says to check Yes, leave the rest of Part II blank and attach the form to the return to claim the EIC.