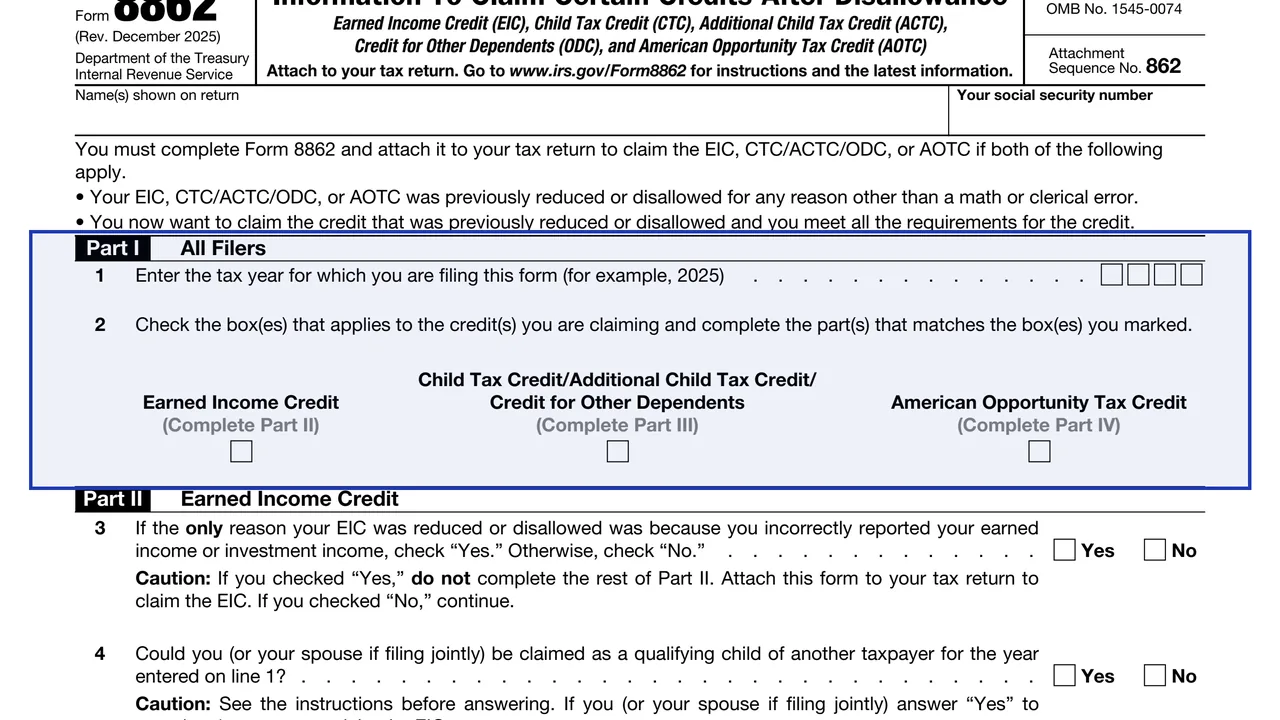
Part I: All Filers
Line 1 holds the tax year for which the form is filed. Line 2 has three boxes: Earned Income Credit, Child Tax Credit/Additional Child Tax Credit/Credit for Other Dependents, and American Opportunity Tax Credit.
8862
Information To Claim Certain Credits After Disallowance
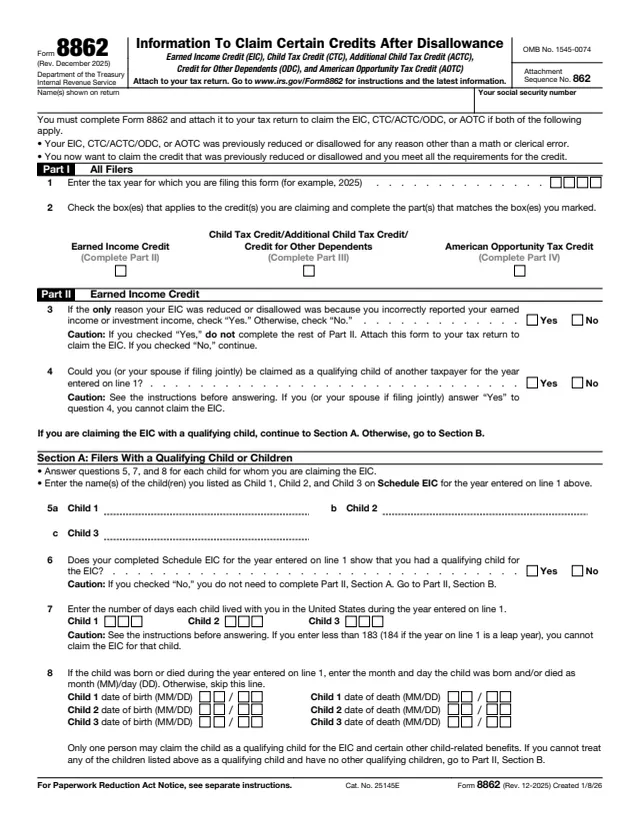
Form 8862, Information To Claim Certain Credits After Disallowance, is attached to an individual's tax return. The IRS About page says taxpayers complete it and attach it to their return if their earned income credit (EIC), child tax credit (CTC)/additional child tax credit (ACTC), credit for other dependents (ODC) or American opportunity credit (AOTC) was reduced or disallowed for any reason other than a math or clerical error, and they want to take the credit(s) and meet all the requirements.
The form has four parts. Part I is for all filers. Part II covers the EIC, Part III the CTC/ACTC/ODC and Part IV the AOTC. On line 2 the filer checks a box for each credit being claimed and completes only the matching parts.
The form is not filed on its own: it says "Attach to your tax return." This page has the December 2025 revision. The PDF can be filled out free in the browser on this page and downloaded without an account.
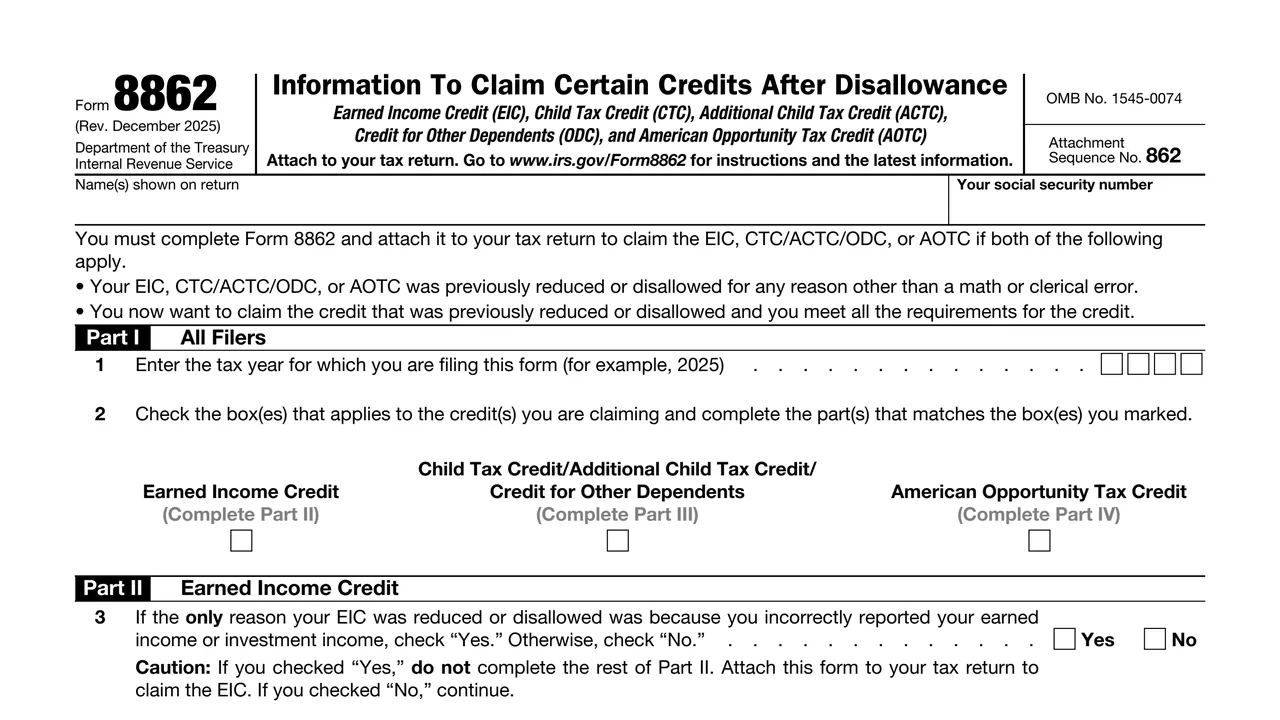
Line 1 holds the tax year for which the form is filed. Line 2 has three boxes: Earned Income Credit, Child Tax Credit/Additional Child Tax Credit/Credit for Other Dependents, and American Opportunity Tax Credit.
Line 3 asks whether the only reason the EIC was reduced or disallowed was incorrectly reported earned income or investment income. Line 4 asks whether the filer could be claimed as another taxpayer's qualifying child.
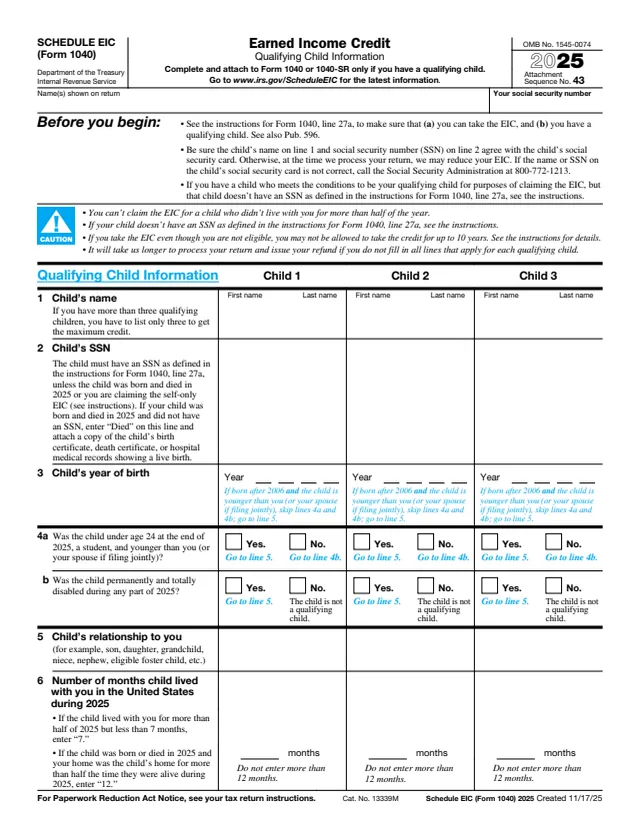
Lines 5 to 8 list up to three children from Schedule EIC, ask whether Schedule EIC shows a qualifying child, the days each child lived with the filer in the United States, and any birth or death date.
Lines 9 to 11 ask the days the main home was in the United States, the filer's and spouse's age at the end of the year, and whether either can be claimed as a dependent on another return.
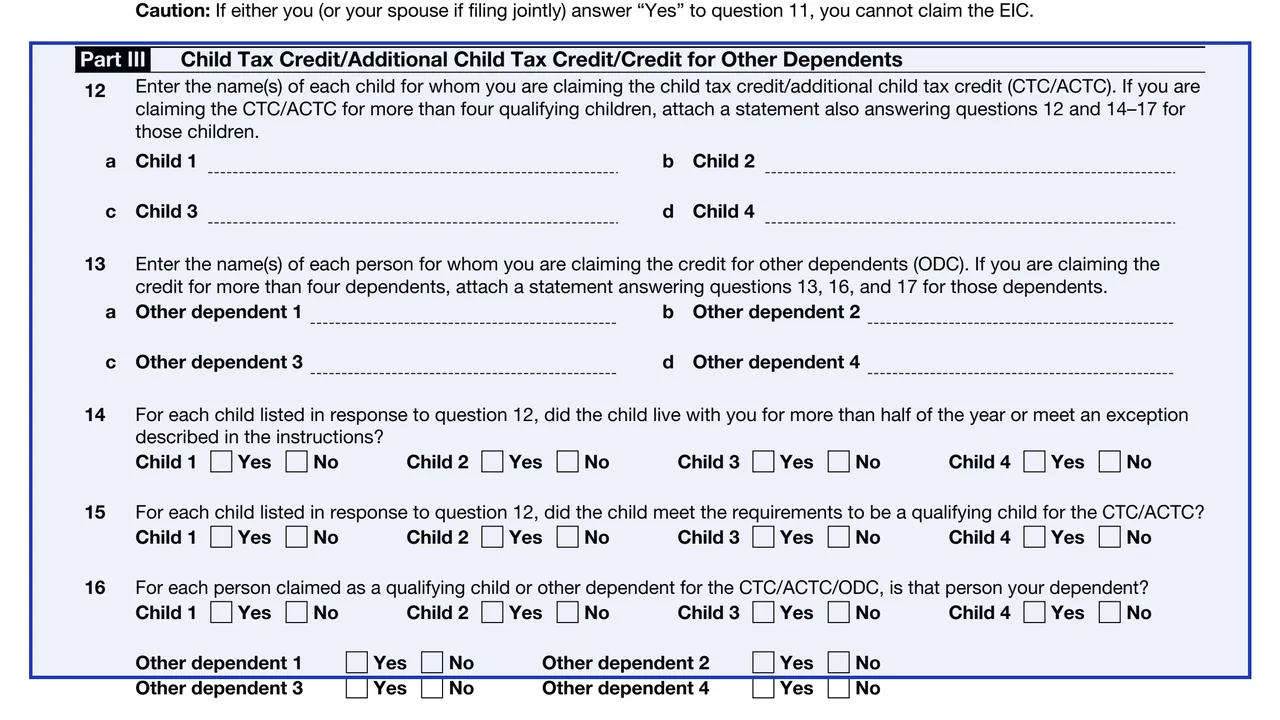
Lines 12 and 13 list up to four children and four other dependents. Lines 14 to 17 ask, for each, about living with the filer, qualifying child status, dependent status and U.S. citizenship, nationality or residence.
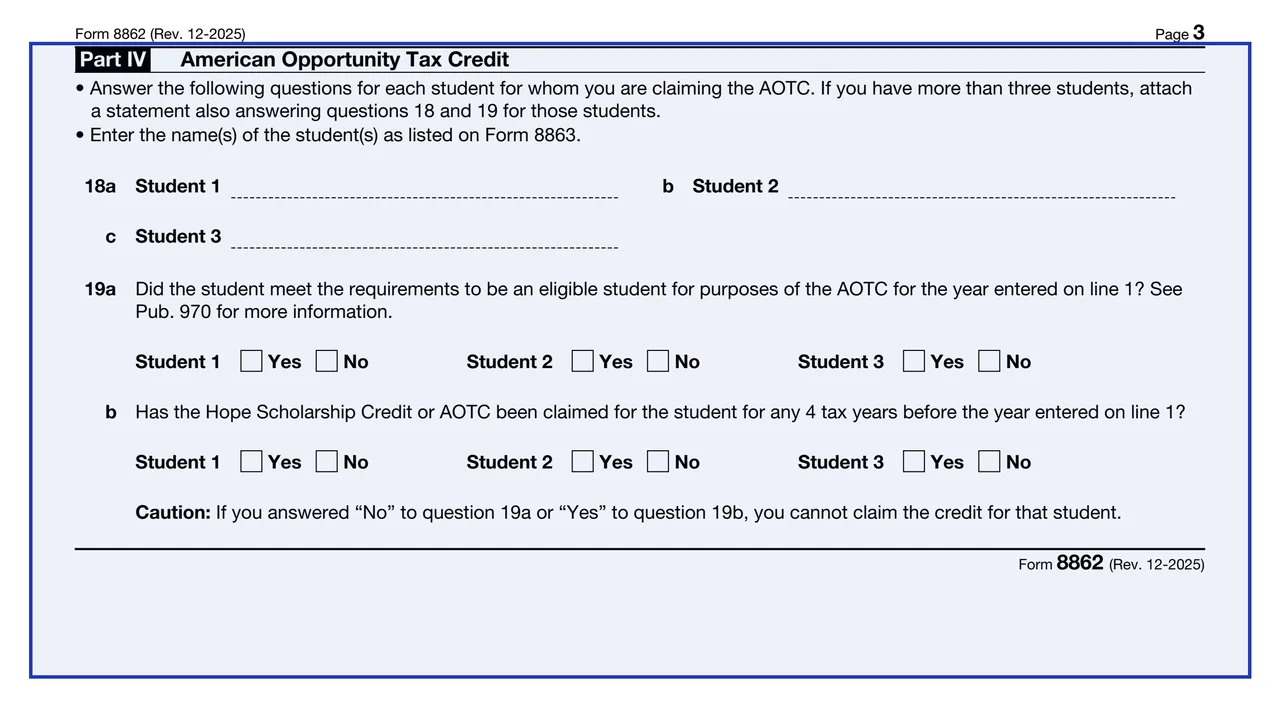
Line 18 lists up to three students as listed on Form 8863. Line 19 asks whether each was an eligible student and whether the Hope Scholarship Credit or AOTC was claimed for any 4 earlier tax years.
The instructions say to enter the year for which the form is filed to claim the credit(s), for example 2025, and not the year the credit(s) was disallowed.
Check the box for each credit being claimed. The instructions say a box can be checked for each credit that was previously reduced or disallowed. Then complete only the part that matches each box.
Answer line 3. The form says that after a "Yes" on line 3, the rest of Part II is not completed. Otherwise answer line 4, then Section A for a qualifying child or Section B without one. Child names match Child 1, 2 and 3 on Schedule EIC.
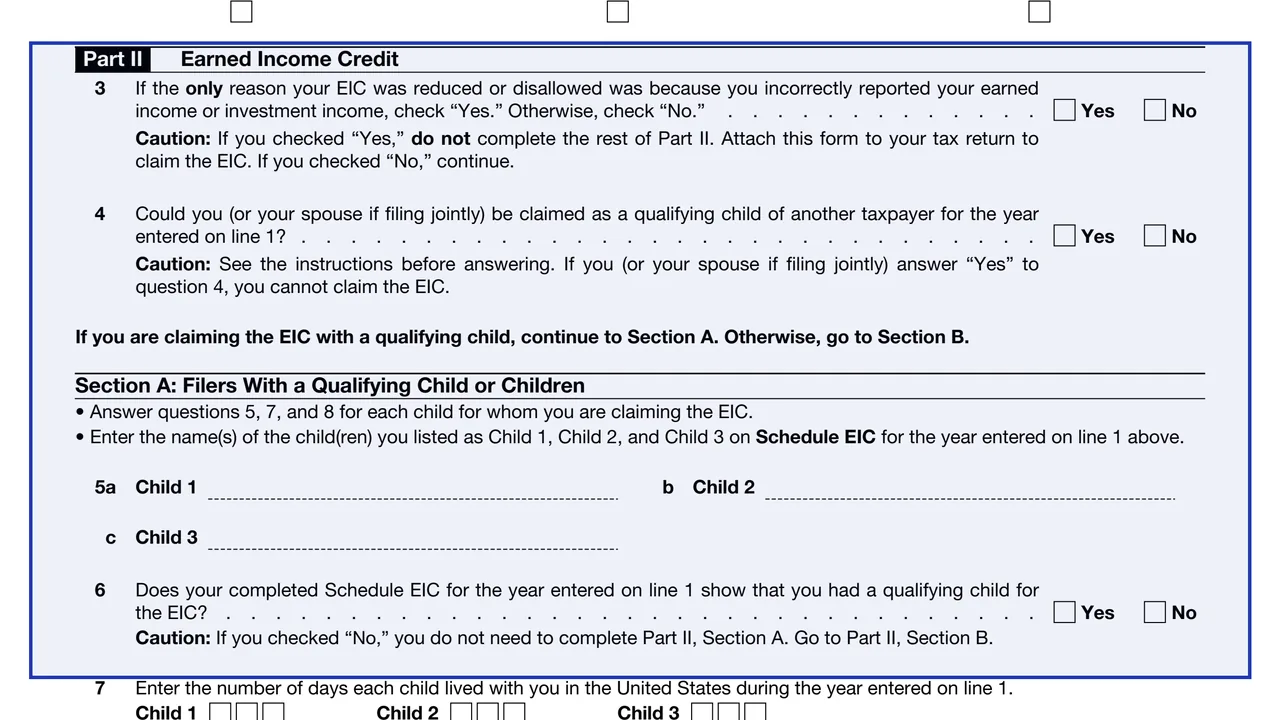
Enter the days each child lived with the filer in the United States. The instructions say temporary absences for school, vacation, business, medical care, military service or juvenile detention count, and a child born or died that year can be entered as 365 (366 in a leap year).
Enter each child for the CTC/ACTC on line 12 and each other dependent for the ODC on line 13, then answer Yes or No for each on lines 14 to 17. The form says to attach a statement for more than four children or dependents.
Enter each student's name as listed on Form 8863 on line 18, then answer lines 19a and 19b for each. The form says to attach a statement for more than three students.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." The instructions say to attach the applicable schedules and forms for each credit claimed, and that other information may be requested before any refund claimed is issued.
The instructions say a return claiming a credit during a ban period, with Form 8862 attached, is mailed to the IRS, because the IRS will reject an e-filed return that attempts to claim a credit during a ban period.
The instructions say the IRS cannot issue refunds before mid-February for returns that claim the EIC or the ACTC, and that this applies to the entire refund.
The instructions say to attach a statement to the end of the return with the filer's name and SSN (or ITIN), numbering each entry to match the line number on Form 8862.
The instructions say the IRS may ask for documents showing the filer lived with each qualifying child, and name school and child care records and other records that show the child's address.
Individual taxpayers complete the form and attach it to their own tax return. It goes to the IRS with that return.
No tool matches that search.
No. The form says "Attach to your tax return." It goes with the return on which the credit is claimed.
The instructions say to enter the year for which the form is filed to claim the credit(s), for example 2025. They say not to enter the year the credit(s) was disallowed.
The instructions list two exceptions: the credit was allowed after an earlier Form 8862 (or other documents) and has not been reduced or disallowed again, or the EIC is claimed without a qualifying child and the only earlier reason was that a child on Schedule EIC was not a qualifying child.
The instructions say Form 8862 is not filed for 2 years after a final determination that a claim was due to reckless or intentional disregard of the rules, or 10 years after a final determination of fraud. They also describe how to appeal the ban.
The instructions say an ITIN can be used for the ODC or AOTC, or for the CTC or ACTC on a 2024 or earlier return, and that the EIC needs a valid SSN. An ITIN is entered in the "social security number" space.
Line 3 covers that case. The form says to check "Yes" if that was the only reason, and then not to complete the rest of Part II.