Name, address and identifying number
The filer's name, street address or P.O. box, city, state or province, country and ZIP or foreign postal code, and identifying number.
8831
Excise Taxes on Excess Inclusions of REMIC Residual Interests
Form 8831, Excise Taxes on Excess Inclusions of REMIC Residual Interests, reports and pays three amounts tied to residual interests in a real estate mortgage investment conduit (REMIC). The instructions say it covers the excise tax under section 860E(e)(1) on a transfer of a residual interest to a disqualified organization, the amount due under Regulations section 1.860E-2(a)(7)(ii) if that tax is to be waived, and the excise tax under section 860E(e)(6) on pass-through entities with interests held by disqualified organizations.
The instructions define a disqualified organization as the United States, any state or political subdivision, any foreign government or international organization, or their agencies (with stated exceptions), most tax-exempt organizations not subject to the unrelated business income tax, and certain cooperatives.
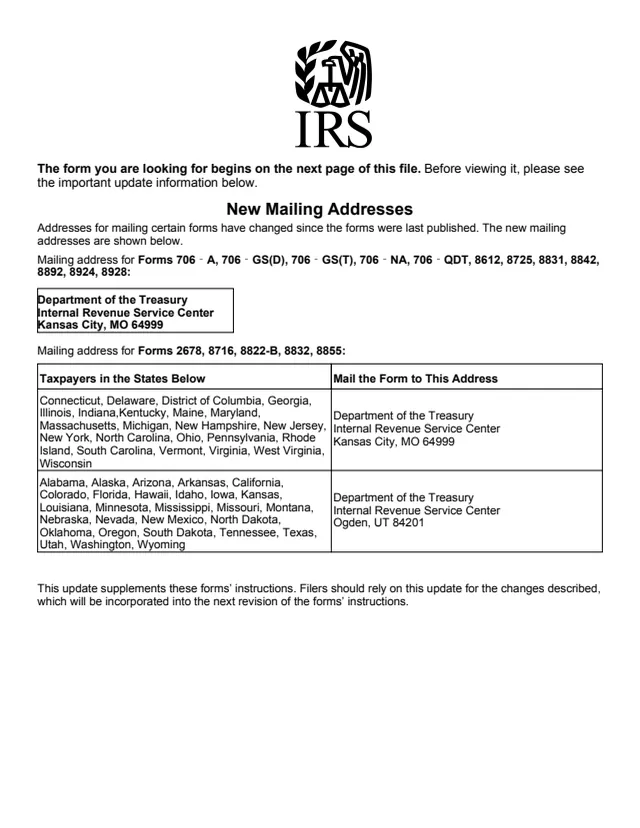
The PDF opens with an IRS notice of a new mailing address for Form 8831, which replaces the address in the instructions. Its general and line instructions follow the form on pages 3 and 4. You can fill out Form 8831 free in your browser on this page and download it without an account.
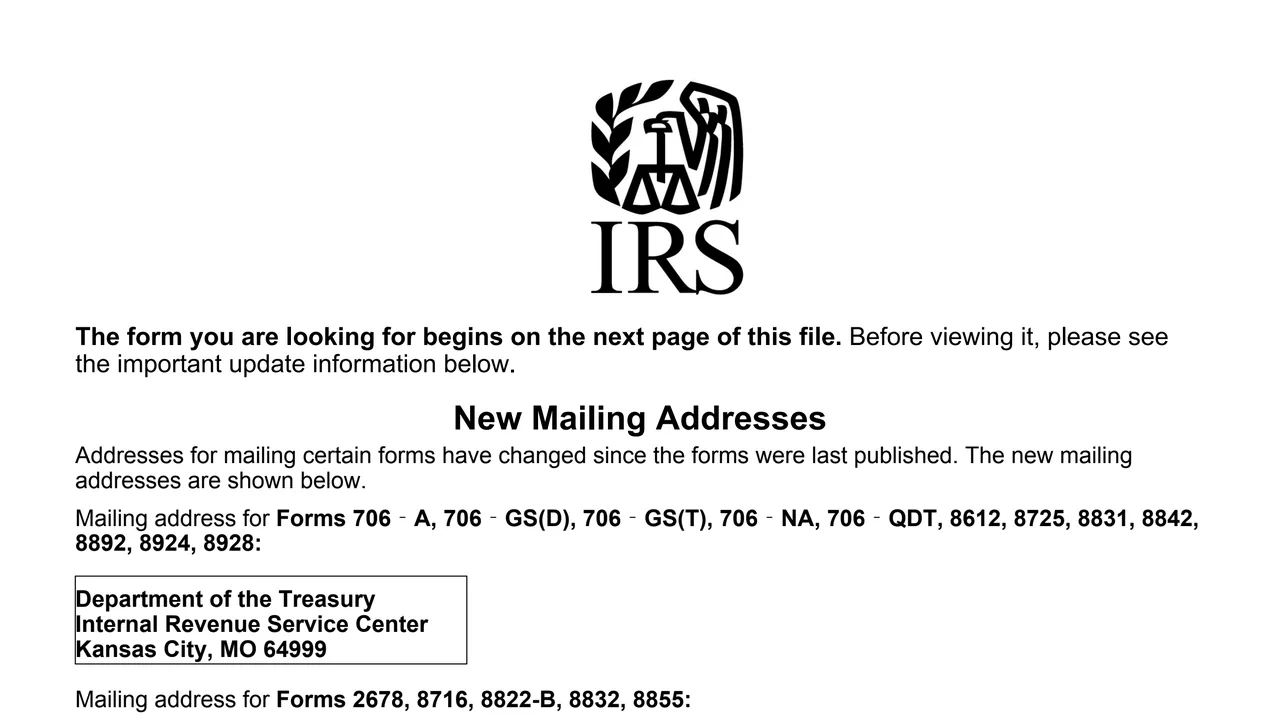
The filer's name, street address or P.O. box, city, state or province, country and ZIP or foreign postal code, and identifying number.
Lines 1 to 3: the transfer date, whether steps were taken so a disqualified organization no longer holds the interest, and the date it disposed of the interest.
Section B figures the section 860E(e)(1) tax on lines 4 and 5 when the answer to question 2 is No. Section C figures the waiver amount on lines 6 and 7 when it is Yes.
Lines 8 to 10: the entity's tax year end, the excess inclusions allocable to interests held by disqualified organizations, and the tax due.
Lines 11 to 14 total the tax, subtract any payment made with Form 7004, and show the amount due or overpayment, followed by the signature and paid preparer sections.
Enter the name on the most recently filed federal income tax return. The instructions say individuals enter a Social Security number and other filers an employer identification number.
Enter the transfer date and answer question 2. A Yes answer adds the disposal date on line 3 and leads to Section C. A No answer leads to Section B.
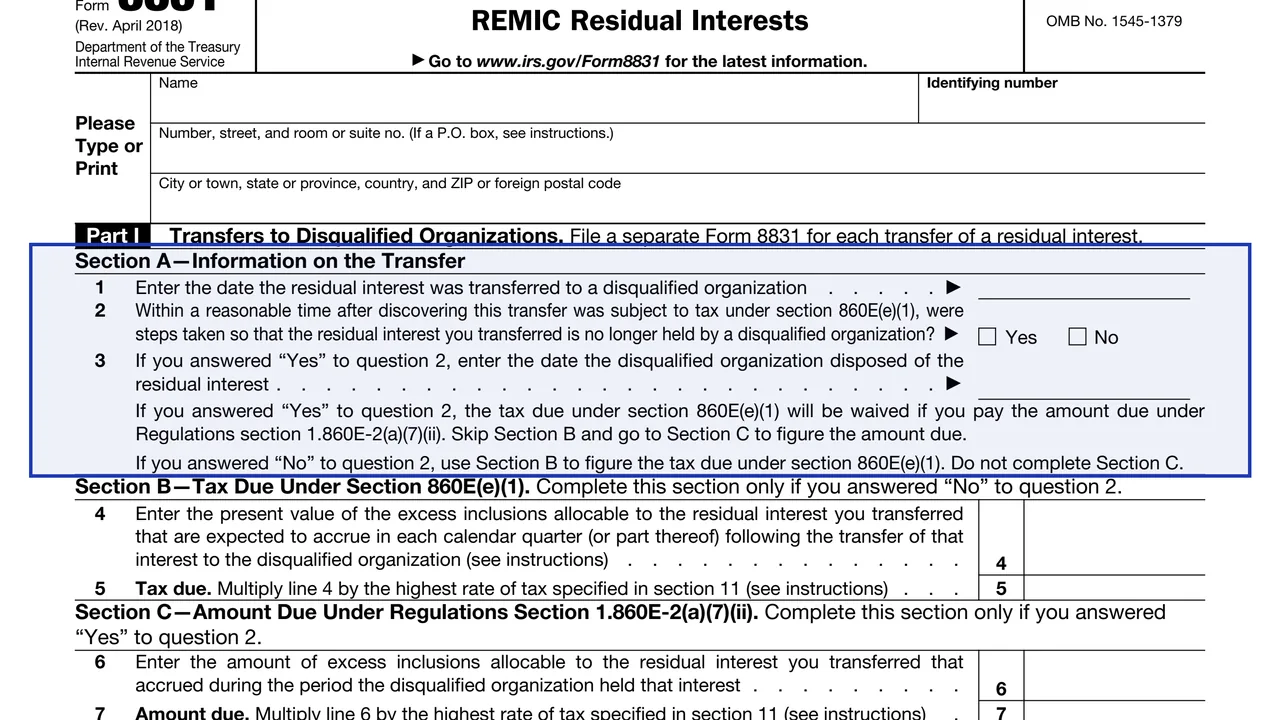
Enter the present value of the expected excess inclusions and multiply by the highest rate in section 11. The instructions say the REMIC furnishes the line 4 information on request within 60 days.
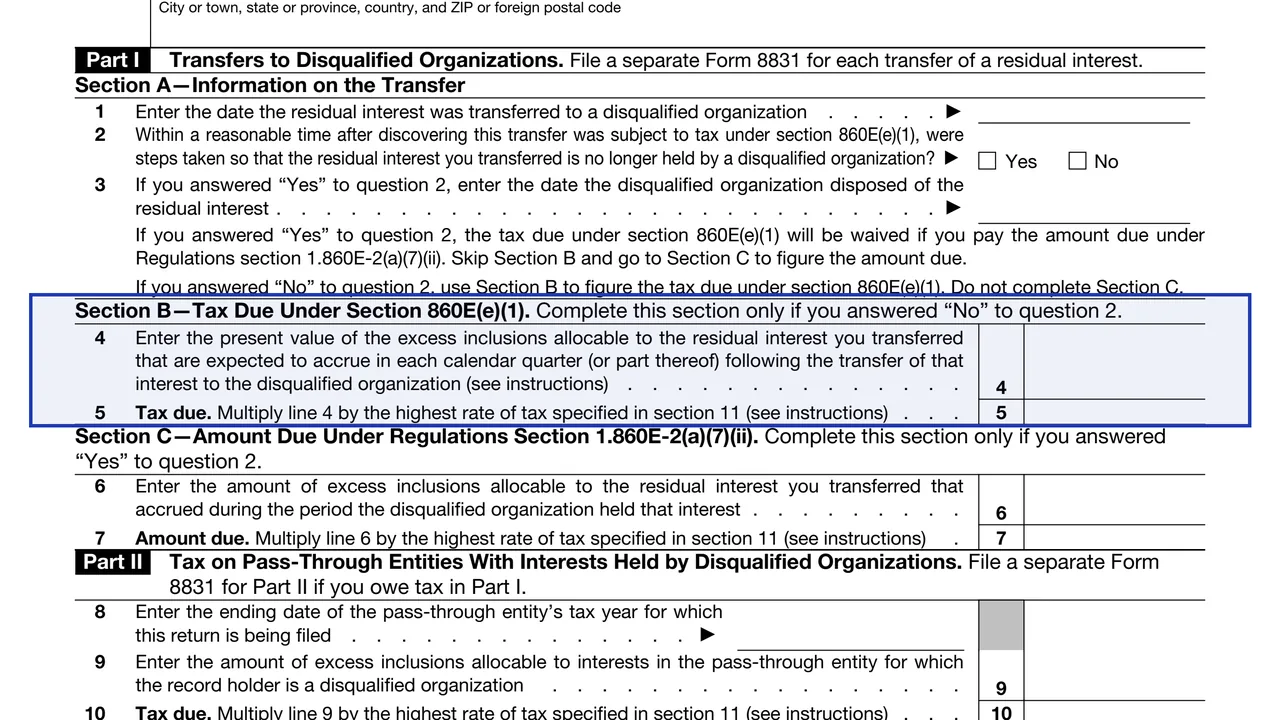
Enter the excess inclusions reported on Schedule Q (Form 1066), line 2c, for the period the disqualified organization held the interest, then multiply by the section 11 rate.
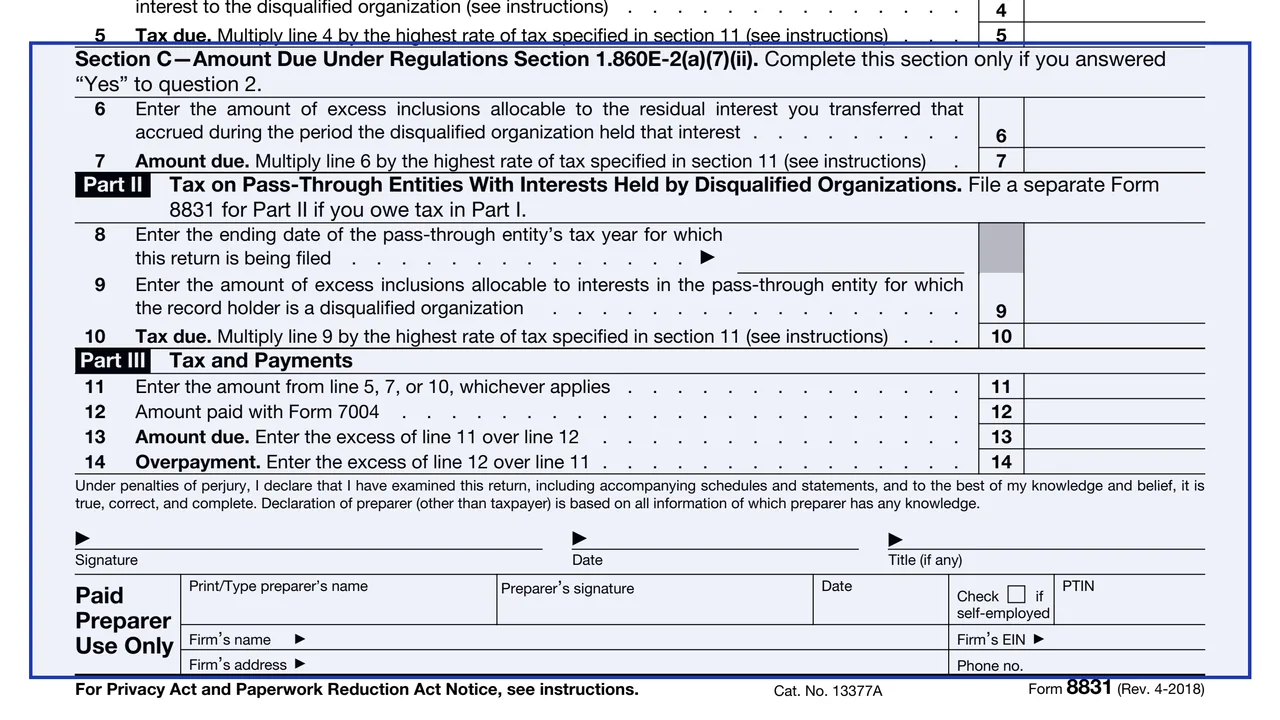
A pass-through entity enters its tax year end and the Schedule Q (Form 1066), line 2c amounts allocable to disqualified organizations, then figures the tax.
Carry the amount from line 5, 7 or 10 to line 11, subtract any Form 7004 payment on line 12, and sign. The instructions say the IRS refunds line 14 if no other taxes are owed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The IRS notice at the front of the PDF gives the new address Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999. It says filers should rely on this update. The instructions on page 3 still print Cincinnati, OH 45999.
The instructions say the section 860E(e)(1) tax is filed and paid by April 15 of the year after the calendar year of the transfer to a disqualified organization.
The instructions say a pass-through entity files and pays by the 15th day of the 4th month after the close of its tax year, moved to the next business day if it falls on a weekend or legal holiday.
Form 7004 requests more time to file. The instructions say it does not extend the time for payment of tax.
The instructions say payment can be made through EFTPS, or by check or money order payable to "United States Treasury" with the name, address, identifying number and "Form 8831" written on it.
The instructions list a late filing penalty of generally 5% a month up to 25%, and a late payment penalty of 1/2 of 1% a month up to 25%. An amended return is a corrected Form 8831 marked "Amended" at the top.
1066
123 fields, 4 pages
1066 Sch. Q
35 fields, 2 pages
7004
26 fields, 1 page
W-12
85 fields, 3 pages
The person or entity liable for one of the taxes completes the form and files it with the IRS. A paid preparer, if any, also signs.
No tool matches that search.
The instructions list the United States, states and their subdivisions, foreign governments, international organizations and their agencies (with exceptions), most tax-exempt organizations not subject to unrelated business income tax, and certain cooperatives.
The IRS update at the front of the PDF gives Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999, replacing the Cincinnati address in the instructions.
No. The form says to file a separate Form 8831 for each transfer of a residual interest, and a separate form for Part II if tax is owed in Part I.
The form says that if steps were taken within a reasonable time so a disqualified organization no longer holds the interest, the tax is waived if the amount figured in Section C is paid.
No. The instructions say Form 7004 extends the time to file Form 8831 but not the time for payment of tax.
The instructions say to file a corrected Form 8831 marked "Amended" at the top of the form.