Tax year
Spaces for the calendar year, or the beginning and ending dates of the partnership's tax year.
8813
Partnership Withholding Tax Payment Voucher (Section 1446)
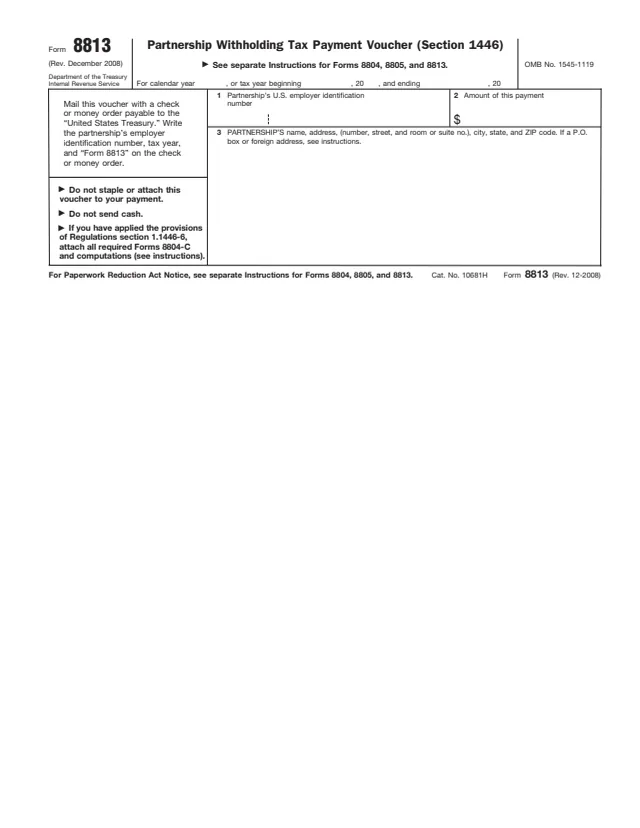
Form 8813 is the payment voucher a partnership uses to pay the withholding tax under section 1446 to the United States Treasury. The instructions say this tax is based on effectively connected taxable income (ECTI) allocable to foreign partners, and that Form 8813 must accompany each payment of section 1446 tax made during the partnership's tax year.
The voucher is short: the tax year, the partnership's employer identification number (EIN), the amount of the payment, and the partnership's name and address. The form says to mail it with a check or money order payable to the "United States Treasury." Form 8813 works alongside Form 8804, the annual return for partnership withholding tax, and Form 8805, the statement for each foreign partner. All three share one set of instructions.
Foreign partners do not file Form 8813. You can fill it out free in your browser on this page and download the result without an account.
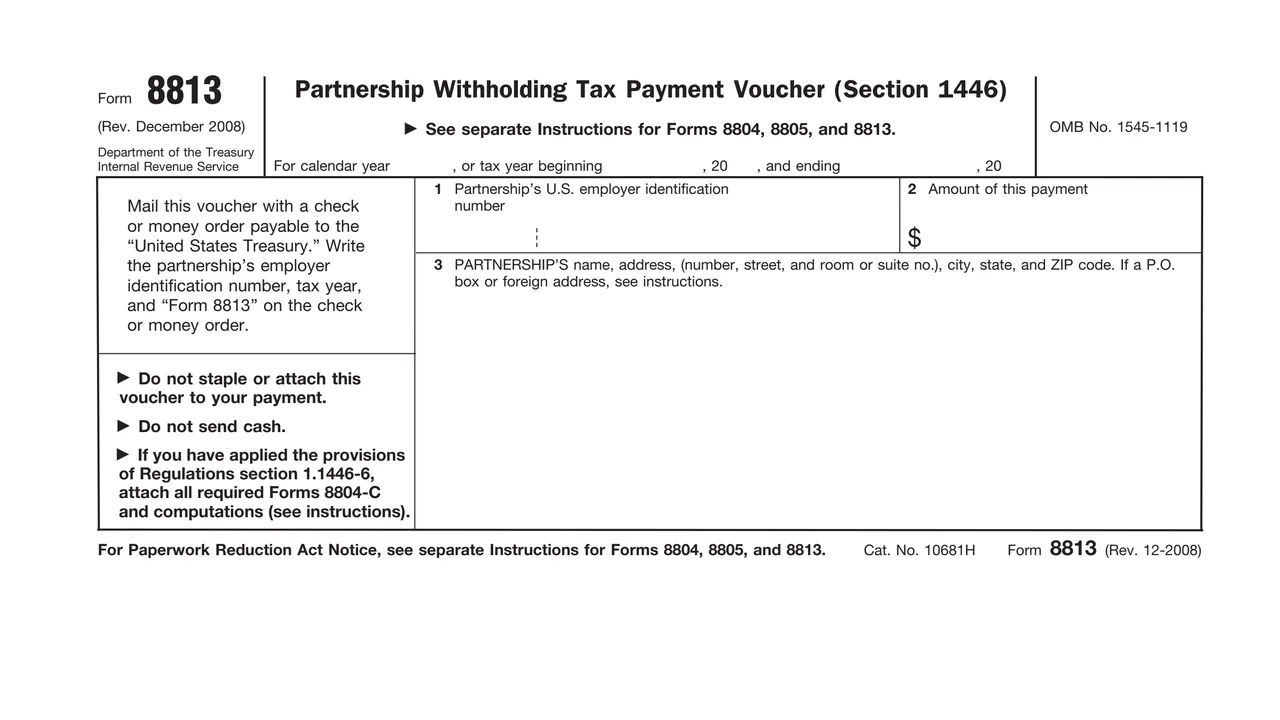
Spaces for the calendar year, or the beginning and ending dates of the partnership's tax year.
The partnership's U.S. employer identification number.
The dollar amount of section 1446 withholding tax sent with this voucher.
The partnership's name, street address with room or suite number, city, state and ZIP code. The form points to the instructions for a P.O. box or foreign address.
The left margin says to mail the voucher with a check or money order, not to staple or attach it to the payment, and not to send cash.
If the partnership applied Regulations section 1.1446-6, the form says to attach all required Forms 8804-C and computations.
Fill in the calendar year, or the beginning and ending dates of the partnership's tax year.
Enter the partnership's EIN. If the EIN has not arrived yet, the instructions say to enter the date the partnership applied for it, then send the number to the IRS at the Where To File address once received.
Enter the installment amount. The instructions point to Form 8804-W for figuring each installment, and list an applicable percentage of 21% (0.21) for corporate partners and generally 37% (0.37) for non-corporate foreign partners.
Enter the name and address. The instructions say to put a suite, room or unit number after the street, use a P.O. box only if mail is not delivered to the street address, and write "c/o" with a third party's name for mail received through an accountant or attorney.
Make the check or money order payable to the "United States Treasury" and write the partnership's EIN, the tax year and "Form 8813" on it, as the form says.
If the installment was reduced because of Forms 8804-C or state and local income tax deductions, the instructions say to attach the Forms 8804-C and a statement showing the calculation of the tax due.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Forms 8804, 8805 and 8813 with the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
The instructions say to file on or before the 15th day of the 4th, 6th, 9th and 12th months of the partnership's tax year for U.S. income tax purposes.
Payments related to Forms 8804 and 8813 may be sent through the Electronic Federal Tax Payment System (EFTPS) instead of a check or money order. The instructions say Forms 8804 and 8805 are still filed (and 8813, as applicable).
The instructions say the partnership notifies all foreign partners of their allocable shares within 10 days of the installment due date or, if paid, the date the installment payment is made.
The instructions say the penalty for not paying tax when due is usually half of 1% (0.005) of the unpaid tax for each month or part of a month, and can't exceed 25% (0.25) of the unpaid tax, unless the partnership shows reasonable cause.
The instructions say any additional amount due is generally paid when filing Form 8804, or with Form 7004 if the partnership requests an extension of time to file Form 8804.
8804
81 fields, 2 pages
8805
100 fields, 4 pages
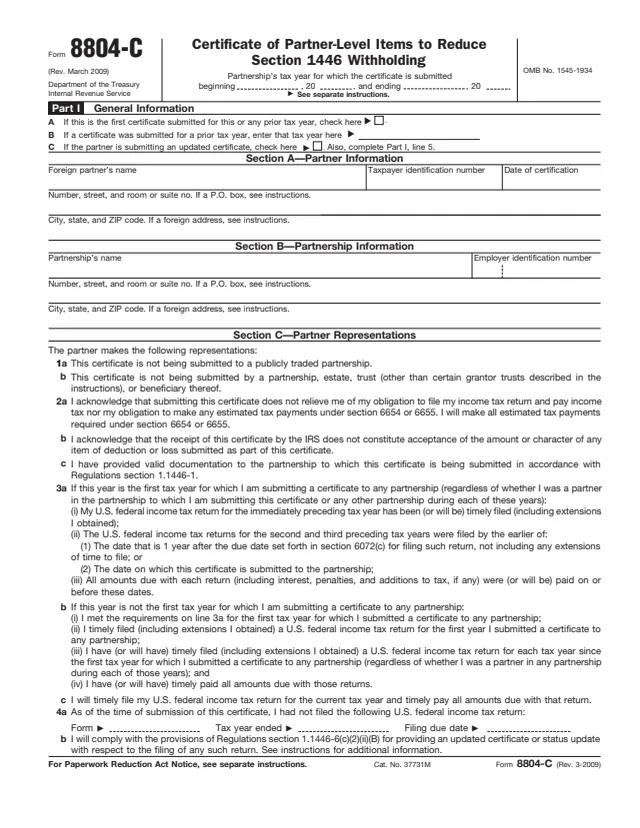
8804-C
46 fields, 3 pages
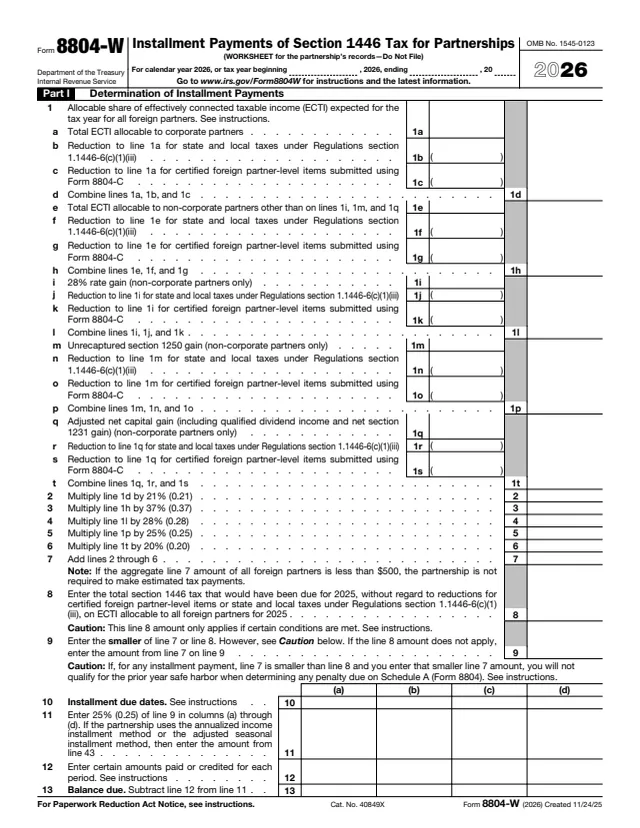
8804-W
319 fields, 4 pages
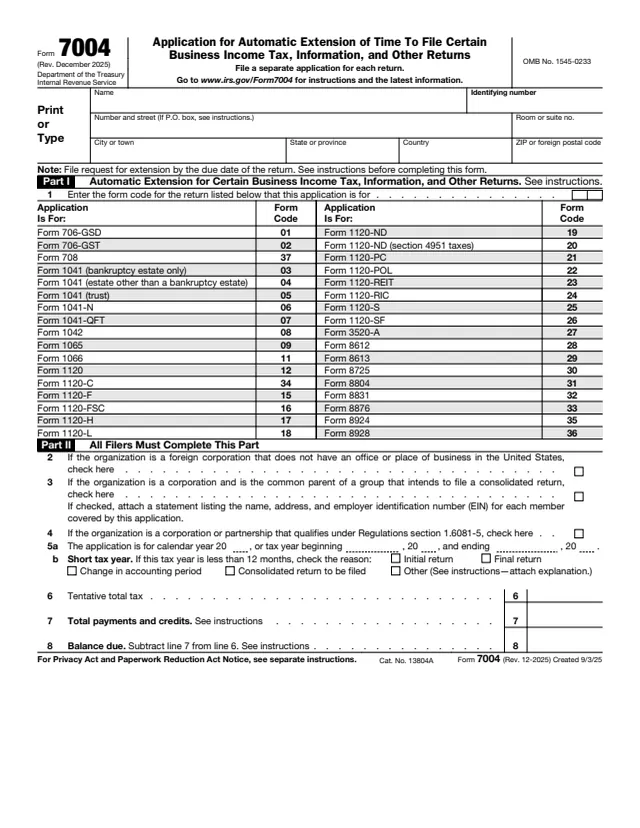
7004
26 fields, 1 page
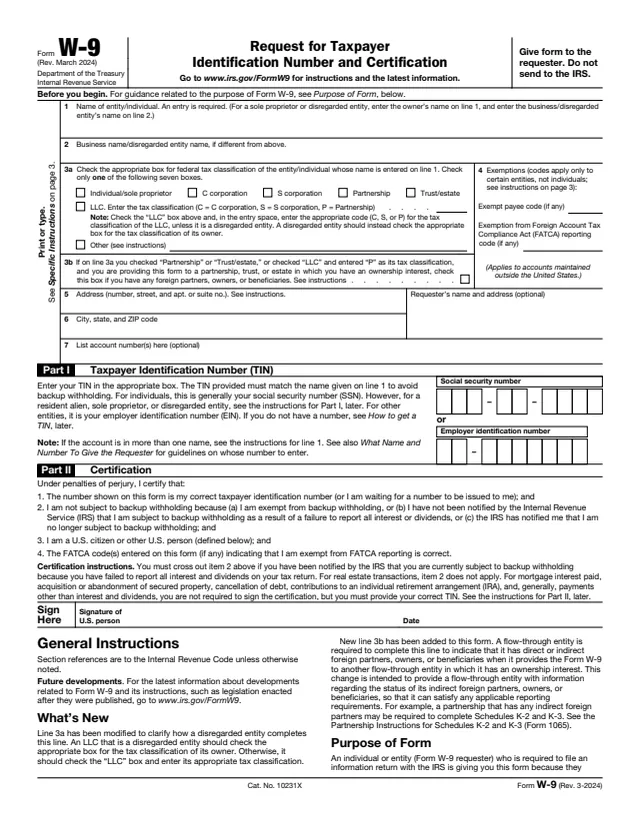
W-9
23 fields, 6 pages
The partnership, or a withholding agent acting for it, completes Form 8813 and sends it to the IRS with each installment of section 1446 withholding tax.
No tool matches that search.
The partnership, or a withholding agent, sends it with each payment of section 1446 withholding tax during the partnership's tax year. Foreign partners do not file it.
The instructions describe four installment payments during the tax year, due on or before the 15th day of the 4th, 6th, 9th and 12th months of the partnership's tax year, each made with Form 8813.
Yes. The instructions say payments may be sent through EFTPS instead of a check or money order. Forms 8804 and 8805 are still filed (and 8813, as applicable).
The instructions say to enter on line 1 the date the partnership applied for its EIN and to send the number to the IRS once it arrives. They note that a missing EIN can delay processing of payments for the partners.
The instructions say yes when an installment was reduced because of a partner's Form 8804-C or state and local income tax deductions. Form 8813 is then filed for that period, with the required documentation, even if no section 1446 tax is due.
The instructions say Form 8813 pays the tax during the year, Form 8804 reports the total section 1446 liability for the year, and Form 8805 shows each foreign partner's share of ECTI and the tax credit.