Header and election box
Name of fund, EIN, address, the calendar year, and the box for the election under section 4982(e)(4).
8613
Return of Excise Tax on Undistributed Income of Regulated Investment Companies
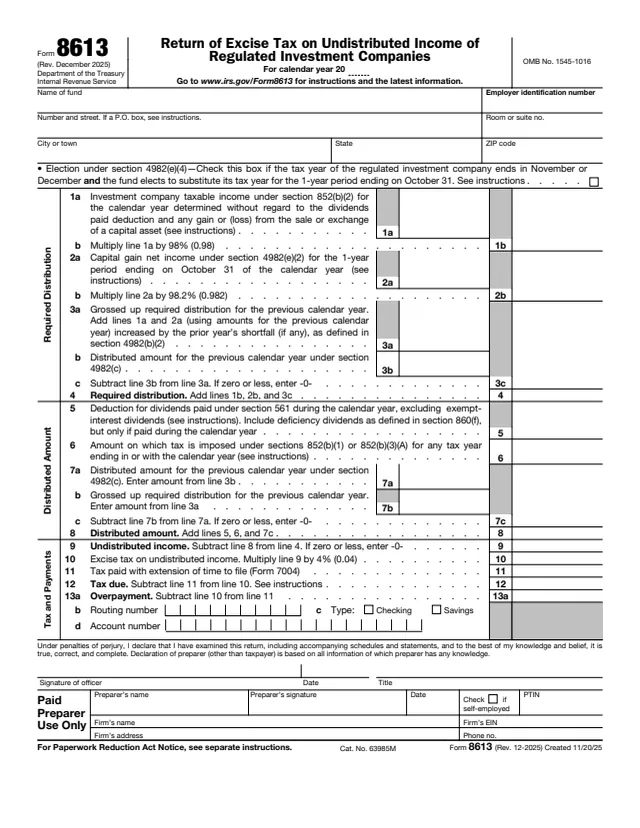
Form 8613, Return of Excise Tax on Undistributed Income of Regulated Investment Companies, is a fund-level return. The IRS About page says regulated investment companies use it to figure and pay the excise tax on undistributed income under section 4982, and to make the section 4982(e)(4) election.
The form compares a required distribution for the calendar year with the amount the fund distributed. The required distribution adds 98% of investment company taxable income, 98.2% of capital gain net income for the 1-year period ending on October 31, and any amount by which the previous calendar year's grossed up required distribution was more than its distributed amount. Undistributed income is then multiplied by 4% to get the excise tax.
An officer of the fund signs the return, and a paid preparer completes the preparer section when one is used. You can fill out the PDF free in your browser on this page and download it without an account.
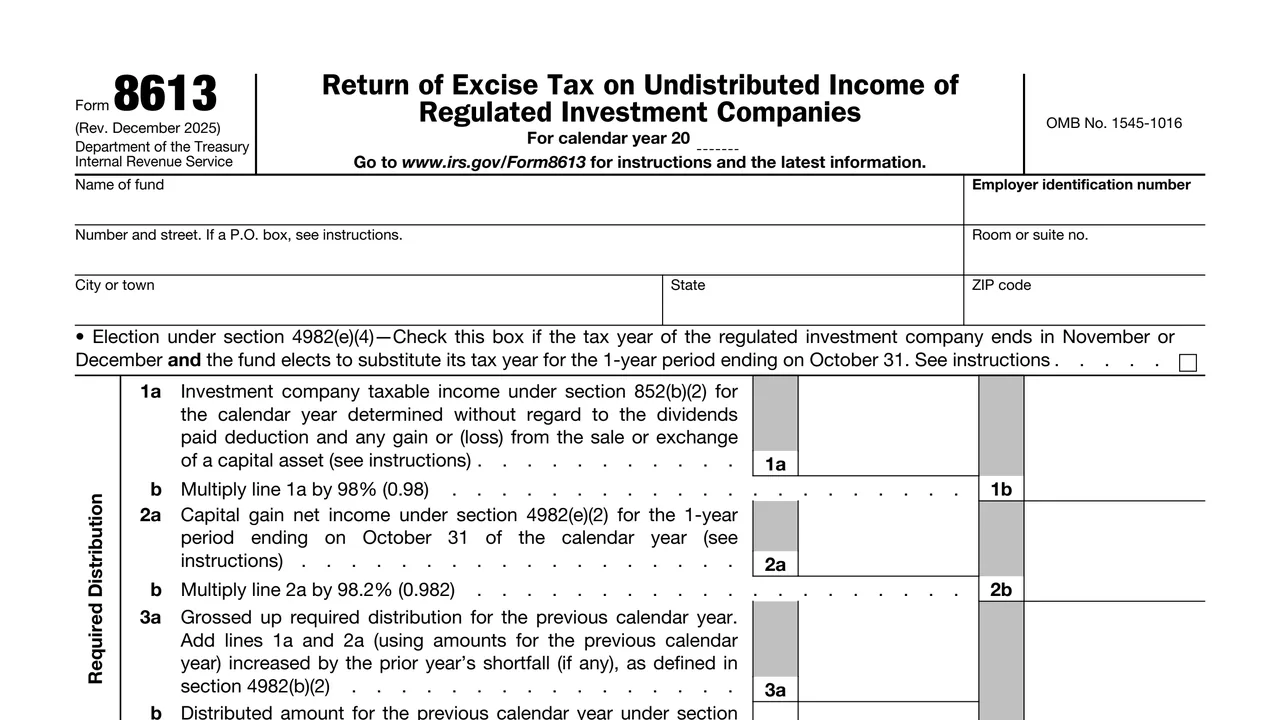
Name of fund, EIN, address, the calendar year, and the box for the election under section 4982(e)(4).
Investment company taxable income times 98%, capital gain net income times 98.2%, and the previous year's shortfall, added together on line 4.
The dividends paid deduction, amounts taxed under section 852(b)(1) or 852(b)(3)(A), any excess from the previous year, and undistributed income on line 9.
The 4% excise tax, tax paid with an extension on Form 7004, tax due, and an overpayment with routing number, account type and account number.
The officer's signature, date and title, followed by the Paid Preparer Use Only section.
Enter the calendar year, the name of the fund, its EIN and its address. For a P.O. box, the form says to see the instructions.
Check it only if the fund's tax year ends in November or December and the fund elects to substitute its tax year for the 1-year period ending on October 31.
Line 1a is investment company taxable income under section 852(b)(2), figured without the dividends paid deduction or capital gains and losses. Multiply it by 98%, multiply line 2a by 98.2%, and add lines 1b, 2b and 3c.
Line 5 is the section 561 dividends paid deduction for the calendar year, excluding exempt-interest dividends. Add lines 5, 6 and 7c on line 8, then subtract line 8 from line 4. If zero or less, enter -0- on line 9.
Multiply line 9 by 4% (0.04) on line 10. Enter tax paid with Form 7004 on line 11, then figure the tax due on line 12 or the overpayment on line 13a with bank details.
An officer signs, dates and enters a title. A paid preparer completes the preparer section.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to go to www.irs.gov/Form8613 for instructions and the latest information. The Paperwork Reduction Act notice is in the separate instructions.
Line 11 reports tax paid with an extension of time to file on Form 7004. The About page lists Form 7004 as a related item.
The return is for a calendar year, which is entered at the top. Lines 3a, 3b and 7 use amounts from the previous calendar year.
The form itself does not print a due date or a mailing address, so this page does not list one. The form points to the instructions at www.irs.gov/Form8613.
If line 11 is more than line 10, line 13a shows the overpayment, with a routing number, checking or savings type and account number.
7004
26 fields, 1 page
8612
39 fields, 1 page
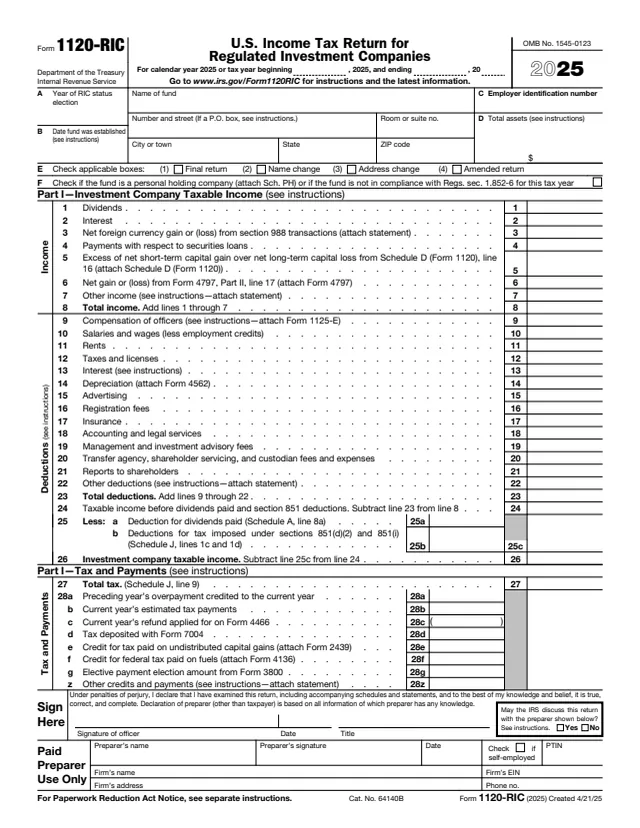
1120-RIC
325 fields, 4 pages
The IRS About page says regulated investment companies use this form. The header asks for the name of the fund and its employer identification number, and an officer signs it.
No tool matches that search.
The IRS About page says regulated investment companies use it to figure and pay the excise tax on undistributed income under section 4982 and to make the section 4982(e)(4) election.
Line 10 says to multiply undistributed income on line 9 by 4% (0.04).
The form says to check the box if the fund's tax year ends in November or December and the fund elects to substitute its tax year for the 1-year period ending on October 31.
Line 4 adds 98% of investment company taxable income, 98.2% of capital gain net income for the 1-year period ending October 31, and line 3c for the previous calendar year.
Yes. Line 11 asks for tax paid with an extension of time to file on Form 7004, which is subtracted from the tax on line 10.
The form says to go to www.irs.gov/Form8613 for instructions and the latest information.