Name, SSN and address
Name and social security number, and an address block that is filled in only when the form is filed by itself and not with the tax return.
8606
Nondeductible IRAs
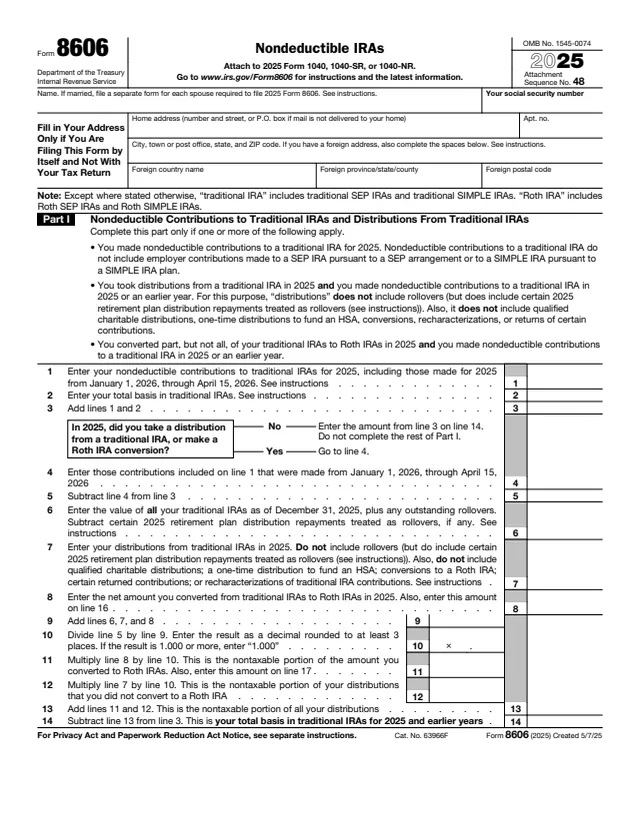
Form 8606 is the IRS form individuals use to track IRA basis. The About page says it reports nondeductible contributions made to traditional IRAs, distributions from traditional, SEP or SIMPLE IRAs if nondeductible contributions were ever made, conversions from traditional, SEP or SIMPLE IRAs to Roth IRAs, and distributions from Roth IRAs.
The form figures how much of a distribution or conversion is nontaxable because it comes from basis, and carries the taxable amount to line 4b of Form 1040, 1040-SR or 1040-NR. The instructions describe basis in traditional IRAs as the total of nondeductible contributions and nontaxable amounts rolled over, minus nontaxable distributions, and say to keep track of it to figure the nontaxable part of future distributions.
The 2025 form is attached to the 2025 Form 1040, 1040-SR or 1040-NR. The instructions say it is not needed solely to report regular contributions to Roth IRAs. You can fill it out free in your browser on this page and download it without an account.
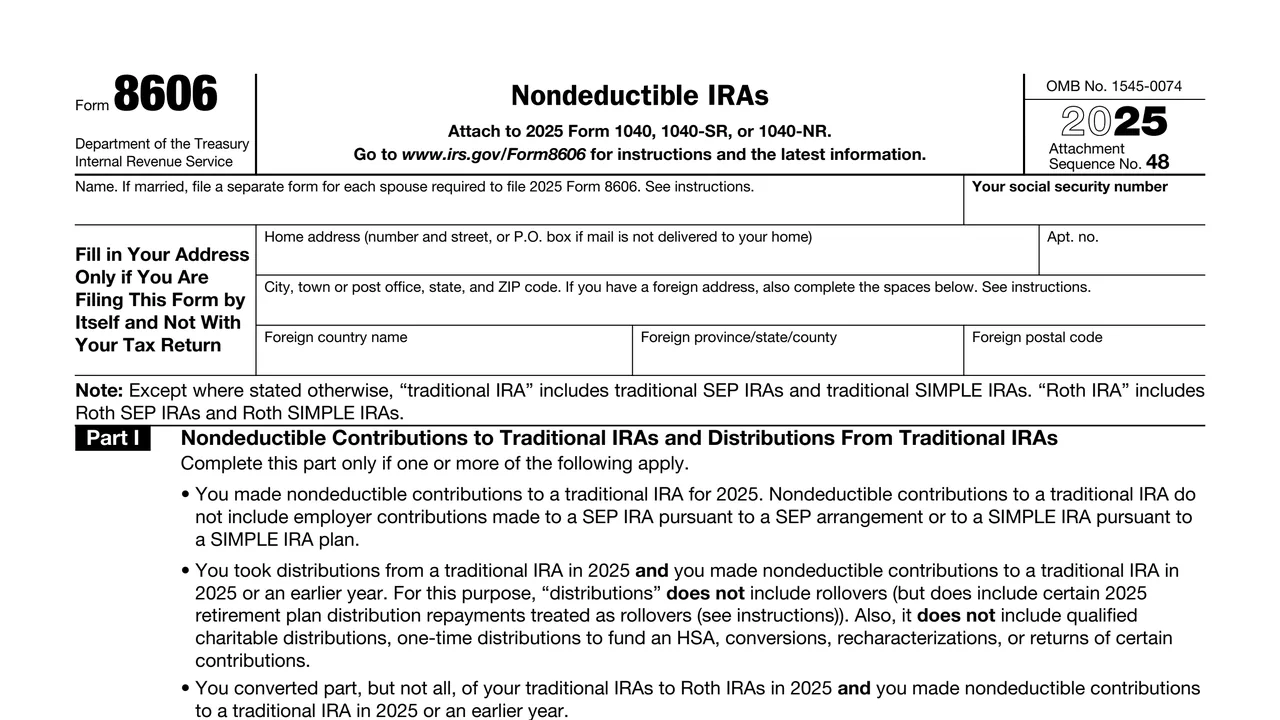
Name and social security number, and an address block that is filled in only when the form is filed by itself and not with the tax return.
Nondeductible contributions, total basis, year-end value of traditional IRAs, distributions and conversions, and the ratio on line 10 that splits them into nontaxable and remaining basis.
The taxable part of traditional IRA distributions, with line 15b for qualified disaster distributions from Form 8915-F and line 15c carried to line 4b of the return.
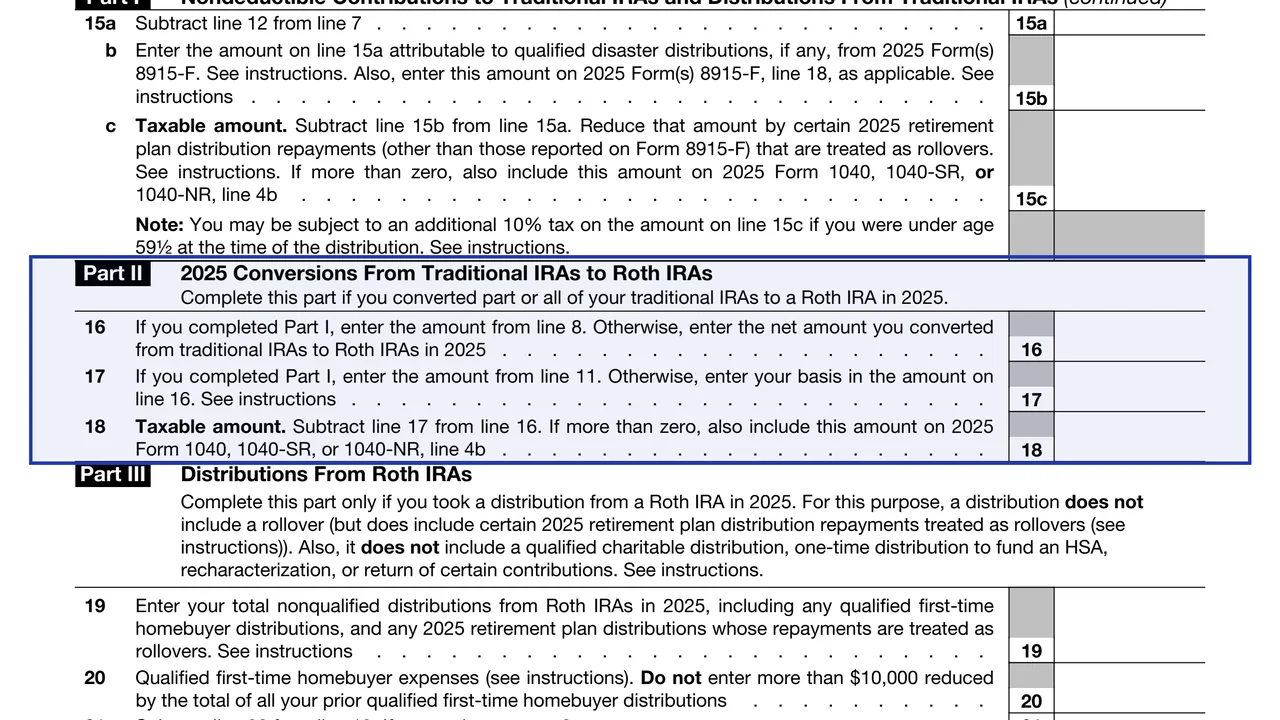
Lines 16 to 18: the net amount converted from traditional IRAs to Roth IRAs, the basis in it, and the taxable amount.
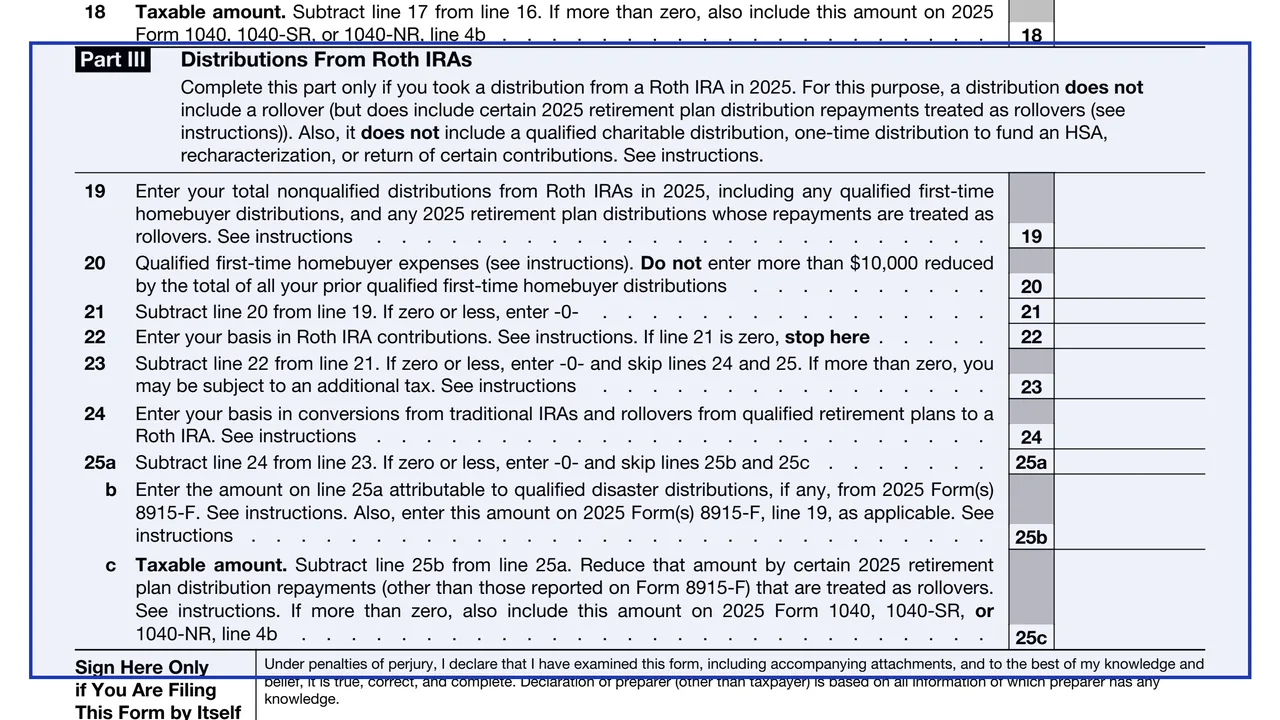
Lines 19 to 25c: nonqualified Roth distributions, first-time homebuyer expenses, basis in contributions and in conversions and rollovers, and the taxable amount.
A signature and date area used only when filing the form by itself, plus a Paid Preparer Use Only section.
On a joint return, enter only the name and SSN of the spouse whose information the form reports. The instructions call for a separate form for each spouse who needs one and for each decedent's inherited IRAs.
Enter 2025 nondeductible contributions, including those made from January 1, 2026, through April 15, 2026. On line 2, the instructions say to generally enter -0- the first year the form is required, otherwise use the Total Basis Chart.
If there was a distribution or Roth conversion, enter the December 31, 2025 value of all traditional IRAs plus outstanding rollovers, the distributions and the net conversion, then figure the ratio and remaining basis.
Figure the taxable part of traditional IRA distributions and include it on line 4b of the return. The form notes a possible additional 10% tax if under age 59½ at the time of the distribution.
Enter the net amount converted to a Roth IRA, the basis in it, and the taxable difference on line 18, which also goes on line 4b of the return when more than zero.
For Roth IRA distributions, enter nonqualified distributions, any qualified first-time homebuyer expenses (no more than $10,000 reduced by prior such distributions), and basis in contributions and conversions to find the taxable amount on line 25c.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file 2025 Form 8606 with the 2025 Form 1040, 1040-SR or 1040-NR by the due date, including extensions, of the return.
If no income tax return is required but Form 8606 is, the instructions say to sign it and send it at the same time and place the Form 1040, 1040-SR or 1040-NR would be filed, with the address on page 1.
The instructions list a $50 penalty for not filing a required Form 8606 to report a nondeductible traditional IRA contribution for 2025, unless reasonable cause is shown.
The instructions list a $100 penalty for overstating nondeductible contributions, unless reasonable cause is shown.
The instructions say to keep Forms 8606, Forms 5498 or similar statements, Forms 1099-R and page 1 of returns for years with nondeductible contributions until all distributions are made.
The instructions say a new Form 8606 with revised information is filed with Form 1040-X when changing a contribution between deductible and nondeductible.

1040
199 fields, 2 pages
5329
75 fields, 3 pages
8915-F
101 fields, 4 pages
5498
83 fields, 4 pages
1099-R
257 fields, 9 pages
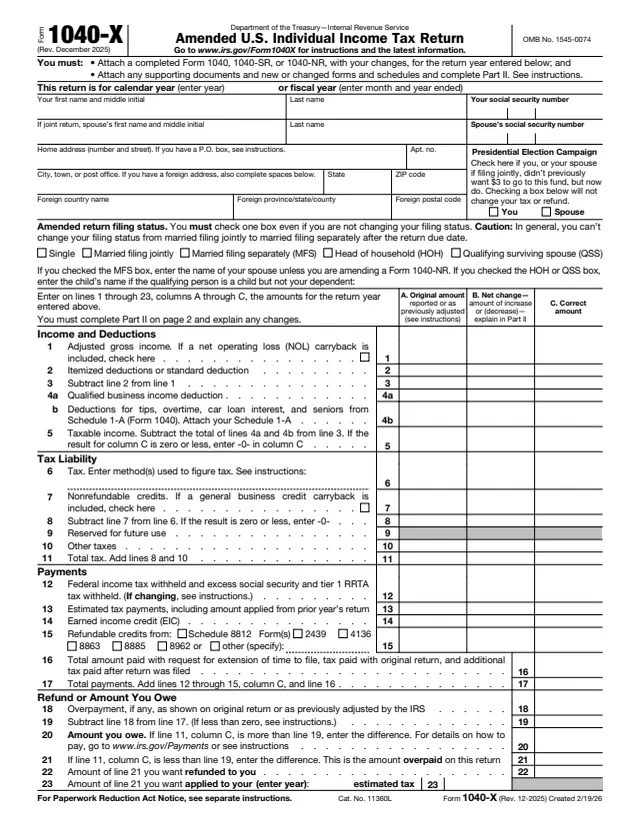
1040-X
166 fields, 2 pages
It is an individual's form. The instructions list the situations in which a 2025 Form 8606 is filed, and say spouses who both need one file a separate form each.
No tool matches that search.
The instructions say Form 8606 does not have to be filed solely to report regular contributions to Roth IRAs, and point to the section What Records Must I Keep.
The instructions describe it as all nondeductible contributions and nontaxable amounts rolled over into these IRAs, minus all nontaxable distributions, adjusted if necessary.
Yes. The instructions say to sign it and send it to the IRS at the same time and place a Form 1040, 1040-SR or 1040-NR would be filed, with the address on page 1.
No. The instructions say if both spouses are required to file 2025 Form 8606, each files a separate form.
The instructions list a $50 penalty for not filing it to report a nondeductible traditional IRA contribution, unless reasonable cause is shown.
The instructions say distributions from traditional IRAs with no nondeductible contributions are not reported on Form 8606 and point to lines 4a and 4b of the Form 1040 or 1040-NR instructions.