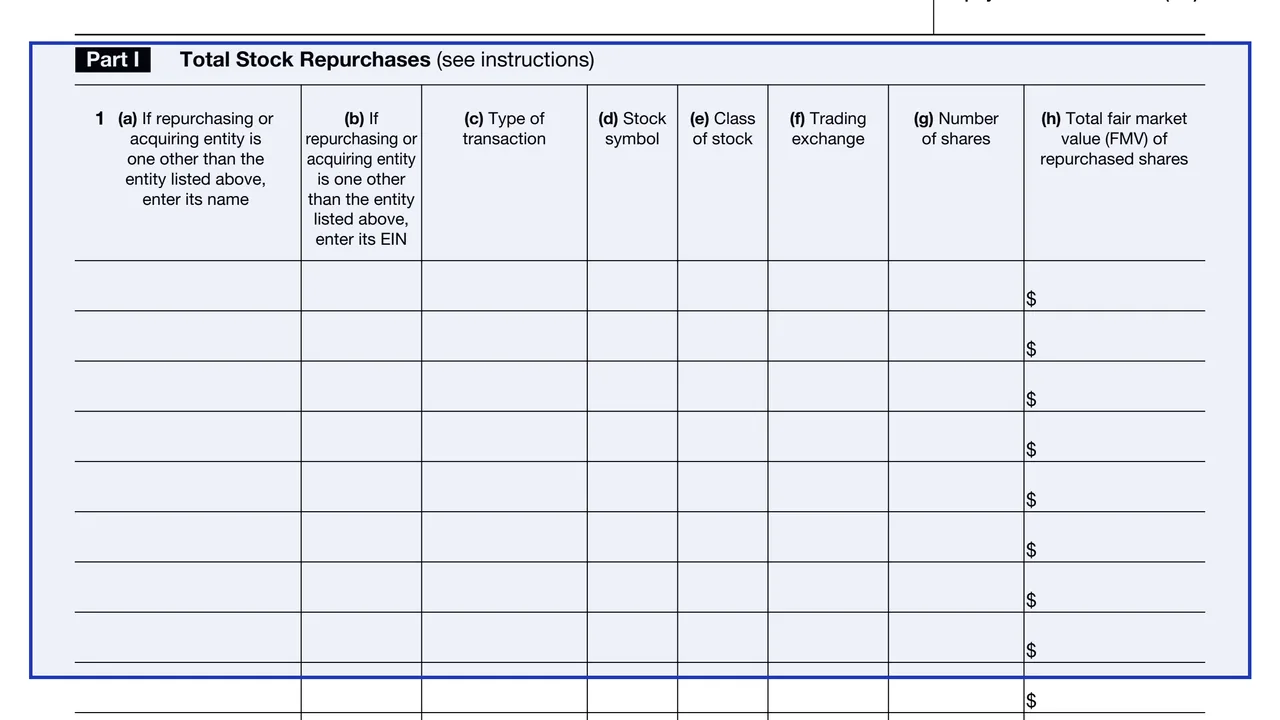
Part I: total stock repurchases
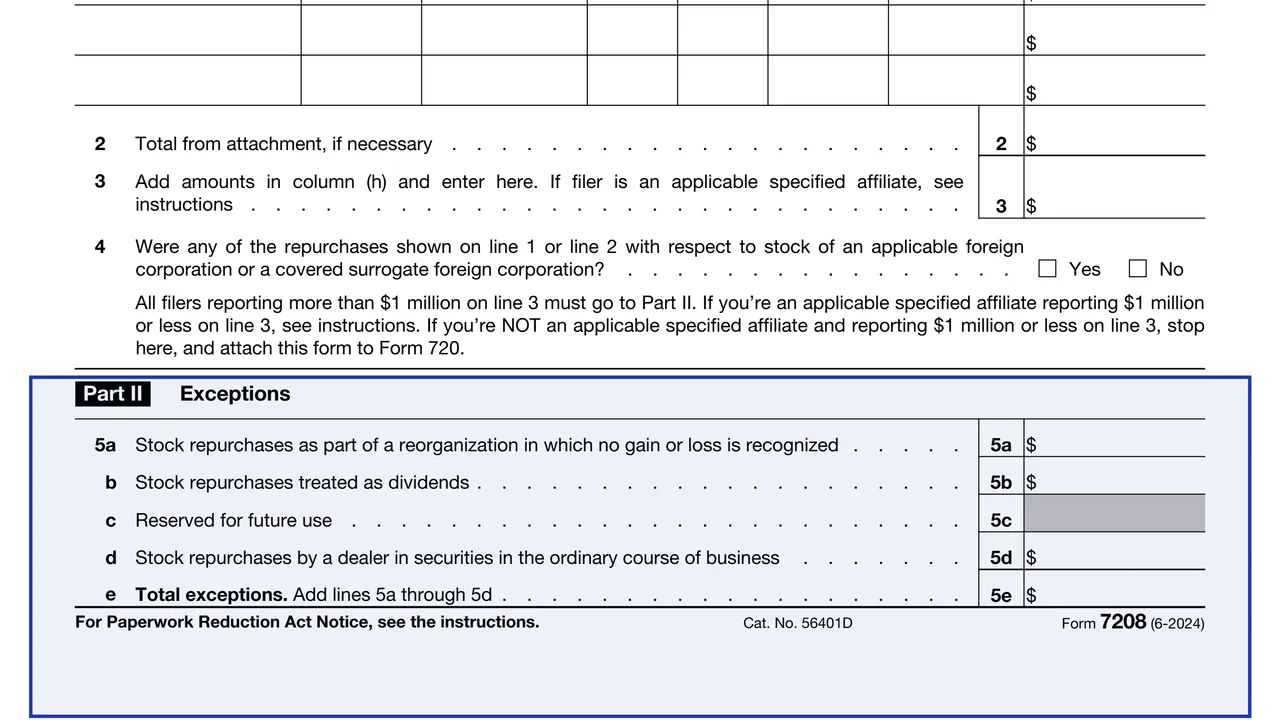
A table of repurchases with the acquiring entity, type of transaction, stock symbol, class, trading exchange, number of shares and total FMV, then totals on lines 2 and 3 and a foreign corporation question on line 4.
7208
Excise Tax on Repurchase of Corporate Stock
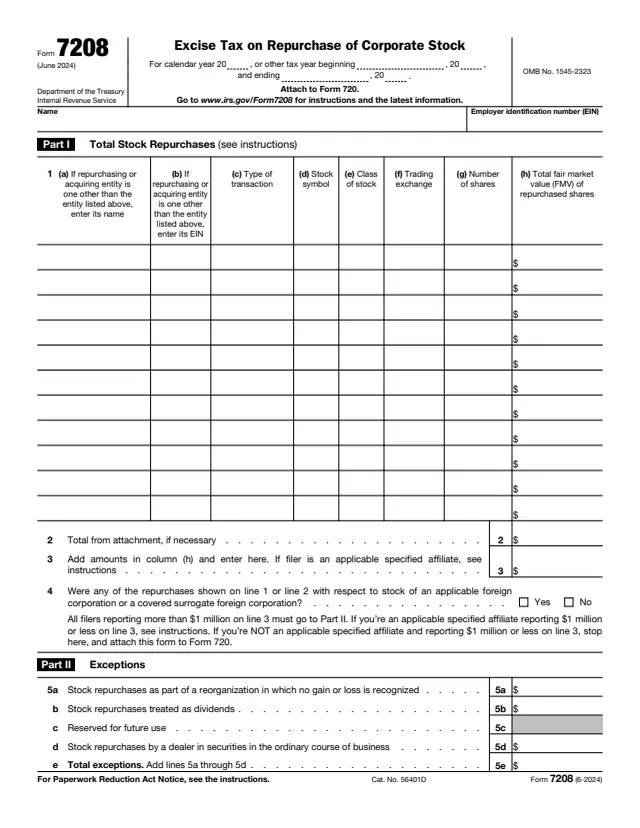
Form 7208, Excise Tax on Repurchase of Corporate Stock, is used to figure the excise tax on repurchases of corporate stock. The About page says it is attached to Form 720, Quarterly Federal Excise Tax Return.
The instructions say the Inflation Reduction Act of 2022 established this tax under section 4501, equal to 1% of the fair market value (FMV) of stock repurchased during the tax year by certain publicly traded corporations or their specified affiliates, for repurchases after 2022. The form nets out exceptions, stock contributed to employer-sponsored retirement plans and stock issued or provided, then applies the 1% rate.
Form 7208 is an annual return. It is attached to the Form 720 due for the first full quarter after the close of the filer's tax year, and the tax is reported there as IRS No. 150. This page covers the June 2024 edition. You can fill out the PDF free in your browser on this page and download it without an account.
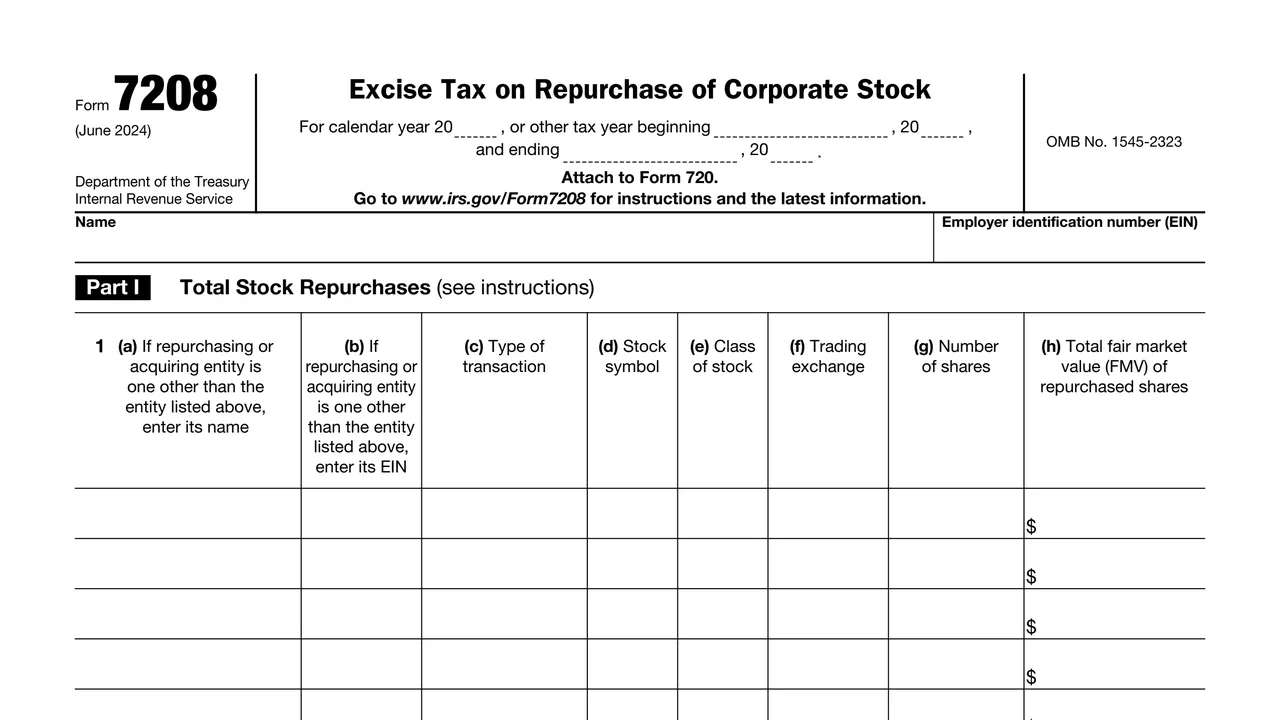
A table of repurchases with the acquiring entity, type of transaction, stock symbol, class, trading exchange, number of shares and total FMV, then totals on lines 2 and 3 and a foreign corporation question on line 4.
Lines 5a to 5e for repurchases in a reorganization with no gain or loss recognized, repurchases treated as dividends, and repurchases by a dealer in securities in the ordinary course of business. Line 5c is reserved.
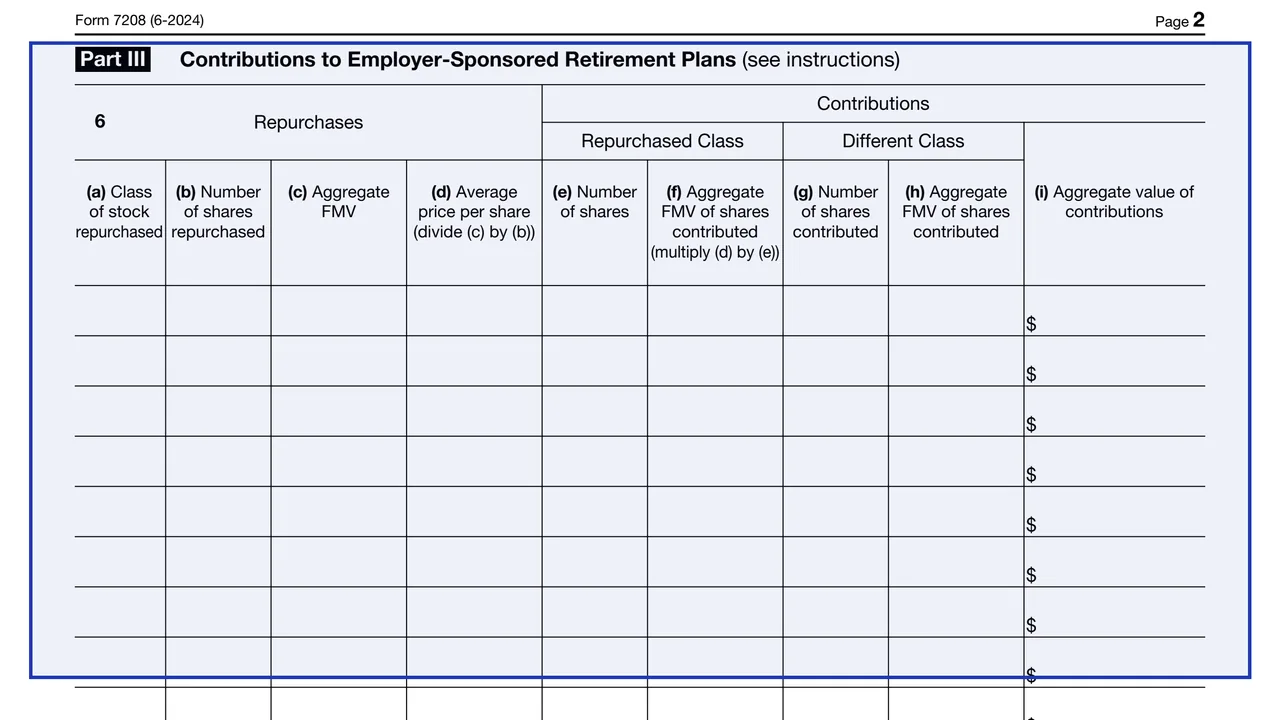
A table on line 6 for stock contributed to employer-sponsored retirement plans, by class repurchased and by different class, with totals on lines 7 and 8.
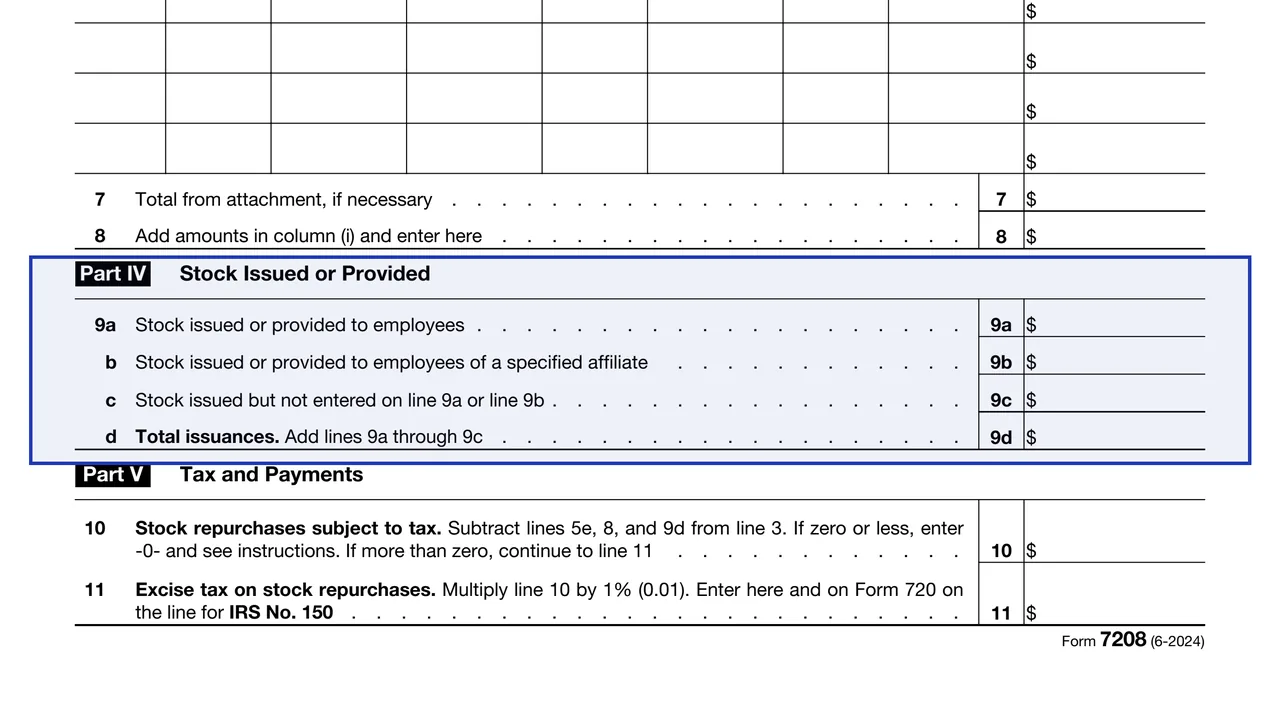
Lines 9a to 9d for stock issued or provided to employees, to employees of a specified affiliate, other stock issued, and the total.
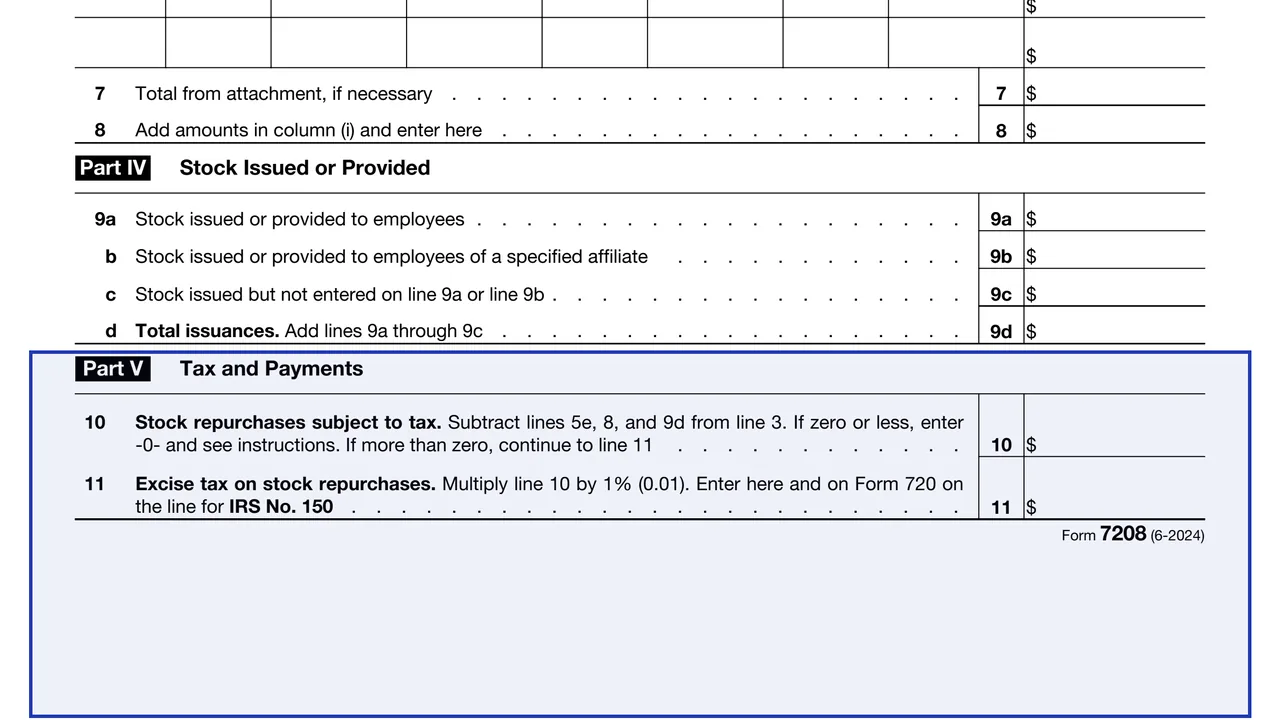
Line 10 subtracts lines 5e, 8 and 9d from line 3. Line 11 multiplies line 10 by 1% (0.01) and carries the result to Form 720 on the line for IRS No. 150.
Enter the tax year for which the form is filed, the name and the EIN. The instructions say an EIN can be applied for online at IRS.gov/EIN or with Form SS-4.
Use a separate line for each transaction, with repurchases under a single plan on one line. Column (c) takes OMR, Tender Offer, ASR, Reorganization, Split-Off, NLF or Other.
Enter the stock symbol (or ISIN/CUSIP), class of stock, established securities market, total shares repurchased and their total FMV. Continuation sheet totals go on line 2, and line 3 adds them up.
Check Yes or No for repurchases of stock of an applicable foreign corporation or covered surrogate foreign corporation. The instructions say if line 3 is $1 million or less, Part I is completed and the form attached to Form 720; above that, continue to Part II. Applicable specified affiliates follow added rules.
Enter the FMV for each exception, complete the line 6 table for retirement plan contributions, and enter the FMV of stock issued or provided on lines 9a to 9c. The instructions say plan contributions count if made by the filing deadline of the Form 720 the form is attached to.
Subtract lines 5e, 8 and 9d from line 3. If zero or less, enter -0- and attach the form to Form 720. Otherwise multiply line 10 by 1% and enter it on line 11 and on Form 720 for IRS No. 150.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Annually, with the Form 720 for the first full quarter after the tax year closes. Tax year ending Jan. to Mar.: 2nd Quarter Form 720, due July 31. Apr. to June: 3rd Quarter, October 31. July to Sept.: 4th Quarter, January 31 (following year). Oct. to Dec.: 1st Quarter, April 30 (following year).
The instructions say to see the Instructions for Form 720 for where to file Form 720 and the attached Form 7208.
If more lines are needed, prepare a continuation sheet in the same format and attach it with Form 7208 to Form 720. The Form 720 is signed under penalties of perjury.
File a corrected Form 7208 with "Amended" entered at the top, attached to Form 720-X for the quarter to which the earlier Form 7208 was attached.
The instructions say late filing may be penalized 5% of the unpaid tax for each month or part of a month, up to 25%, and late payment ½ of 1% per month, up to 25%, unless due to reasonable cause.
The instructions say to keep complete and detailed records sufficient to establish the amounts reported on the form.
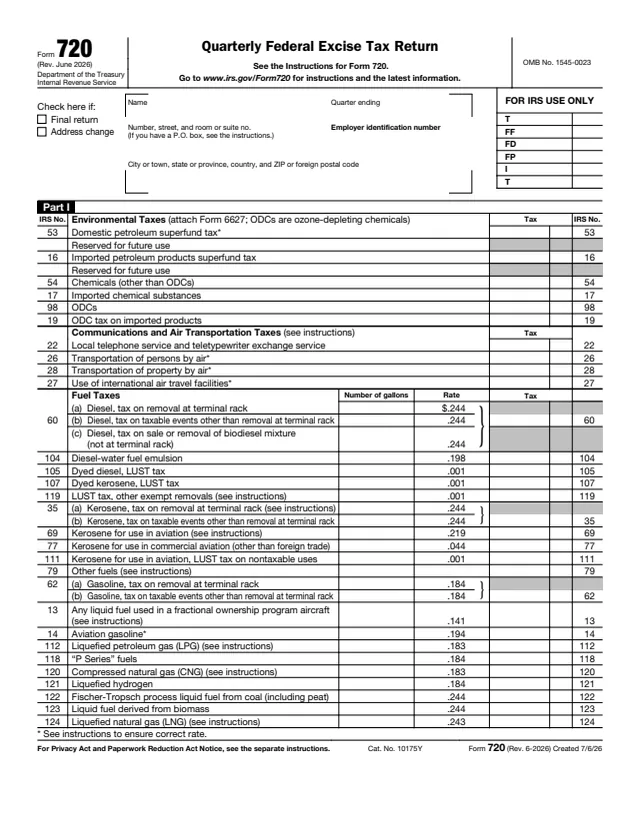
720
715 fields, 8 pages
720-X
120 fields, 2 pages
SS-4
89 fields, 2 pages
7205
113 fields, 1 page
7207
490 fields, 5 pages
Form 7208 is a corporate return, attached to the filer's Form 720. The instructions list three kinds of filers.
No tool matches that search.
The instructions say it is 1% of the fair market value of stock repurchased during the tax year. Line 11 multiplies line 10 by 1% (0.01).
No. It is attached to Form 720, and the tax from line 11 is reported on Form 720 on the line for IRS No. 150.
No. The instructions say Form 7208 is an annual return, attached to the Form 720 due for the first full quarter after the close of the tax year.
The instructions say a covered corporation that is a regulated investment company, a real estate investment trust or a non-RIC '40 Act fund does not need to file it.
The form says filers that are not applicable specified affiliates and report $1 million or less on line 3 stop after Part I and attach the form to Form 720.
The instructions say to file a corrected Form 7208 marked "Amended" and attach it to Form 720-X for the quarter to which the earlier form was attached.