Filer and U.S. shareholder
The name of the person filing the return with identifying number in item A, and the name of the U.S. shareholder with identifying number in item B.
8992
U.S. Shareholder Calculation of Global Intangible Low-Taxed Income (GILTI)
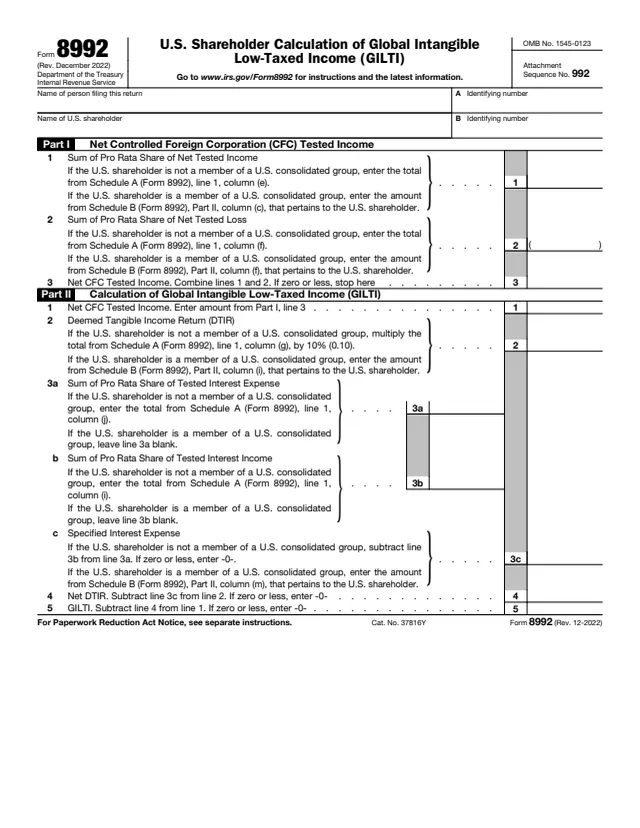
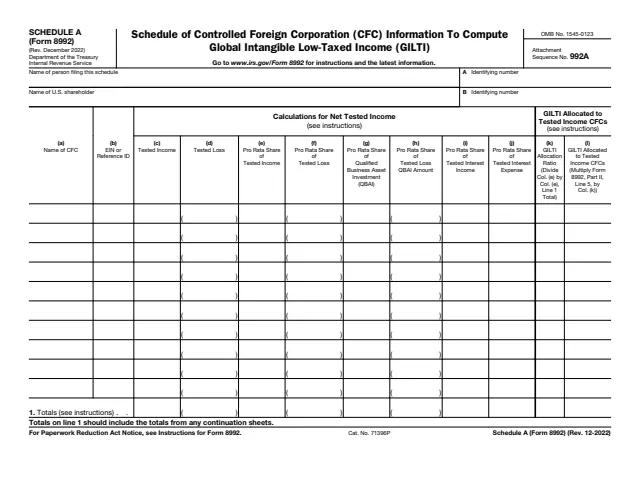
Form 8992, U.S. Shareholder Calculation of Global Intangible Low-Taxed Income (GILTI), is a one-page calculation. The IRS About page says U.S. shareholders of controlled foreign corporations (CFCs) use Form 8992 and Schedule A to figure their global intangible low-taxed income inclusions under section 951A and its related regulations.
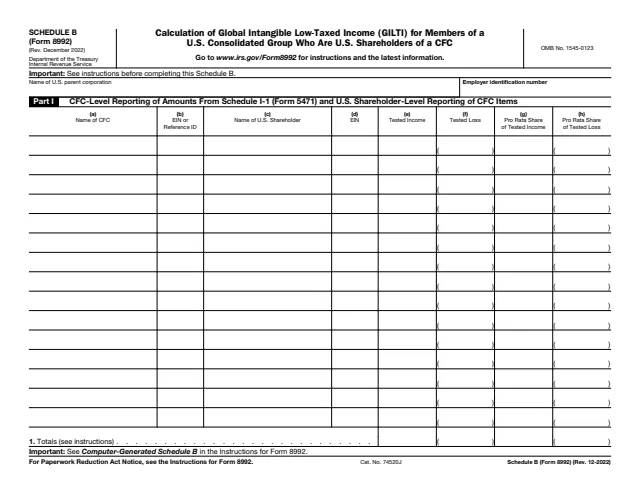
The instructions say Schedule A (Form 8992) is generally completed and attached to Form 8992. If the U.S. shareholder is a member of a U.S. consolidated group, Schedule B (Form 8992) is completed and attached instead. Part I nets the pro rata shares of CFC tested income and tested loss, and Part II reduces that net amount by the net deemed tangible income return (DTIR) to reach the GILTI amount on line 5.
This page hosts the December 2022 revision, which is filed with the separate Instructions for Form 8992. You can fill out Form 8992 free in your browser on this page and download the result without an account.
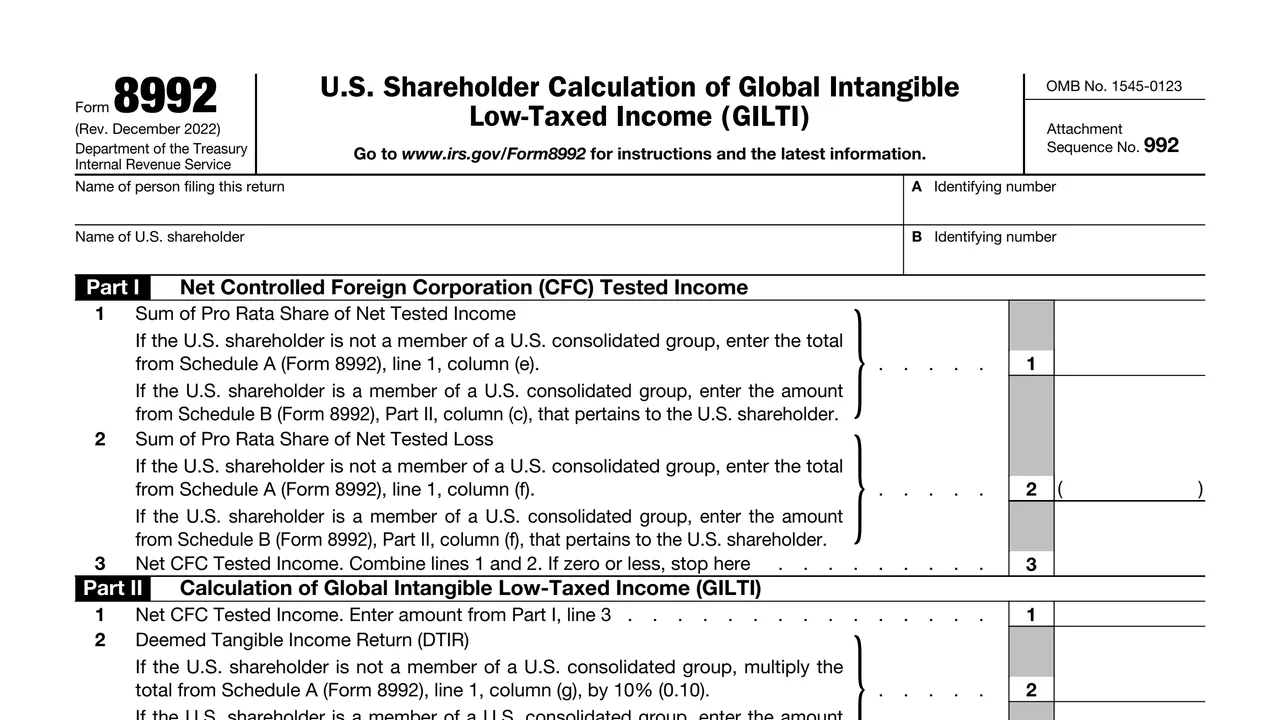
The name of the person filing the return with identifying number in item A, and the name of the U.S. shareholder with identifying number in item B.
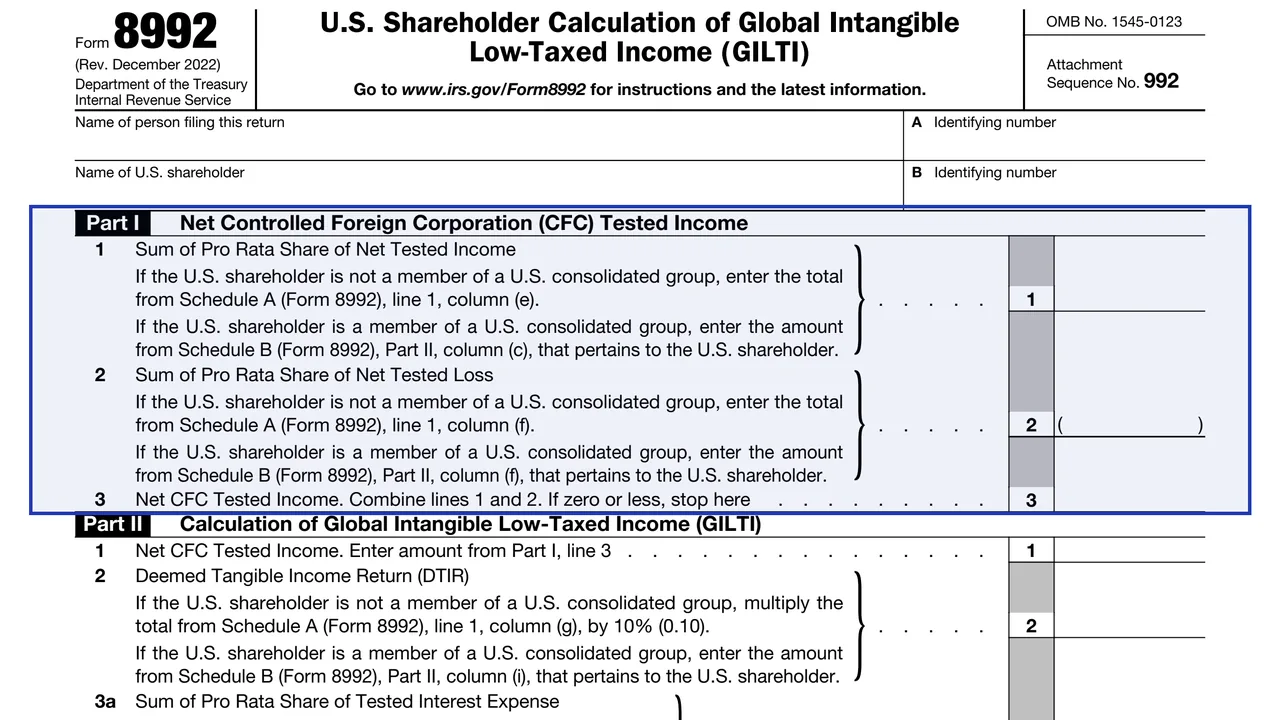
The sum of the pro rata share of net tested income and of net tested loss, taken from Schedule A or, for consolidated group members, Schedule B.
Net CFC tested income, the combination of lines 1 and 2. The form says to stop here if it is zero or less.
Net CFC tested income carried from Part I, and the deemed tangible income return (DTIR).
Pro rata share of tested interest expense and tested interest income, and specified interest expense.
Net DTIR, and GILTI, which is line 1 minus line 4, with -0- entered if zero or less.
The instructions say an individual's identifying number is the SSN and all others use an EIN. For a consolidated group, list the common parent as the filer with its EIN in item A, and leave the U.S. shareholder name and item B blank.
If the U.S. shareholder is not in a consolidated group, the instructions say to first complete Schedule A, columns (a) through (f), then follow the lines on the face of Form 8992, Part I, lines 1 through 3.
Enter tested income and tested loss from Schedule A, line 1, columns (e) and (f), or from Schedule B, Part II, columns (c) and (f). If line 3 is zero or negative, the instructions say not to complete Part II or Schedule A, columns (g) through (l).
Carry over line 3 of Part I. For DTIR on line 2, the form says to multiply Schedule A, line 1, column (g), by 10% (0.10). Lines 3a and 3b come from Schedule A, columns (j) and (i), and are left blank for consolidated group members.
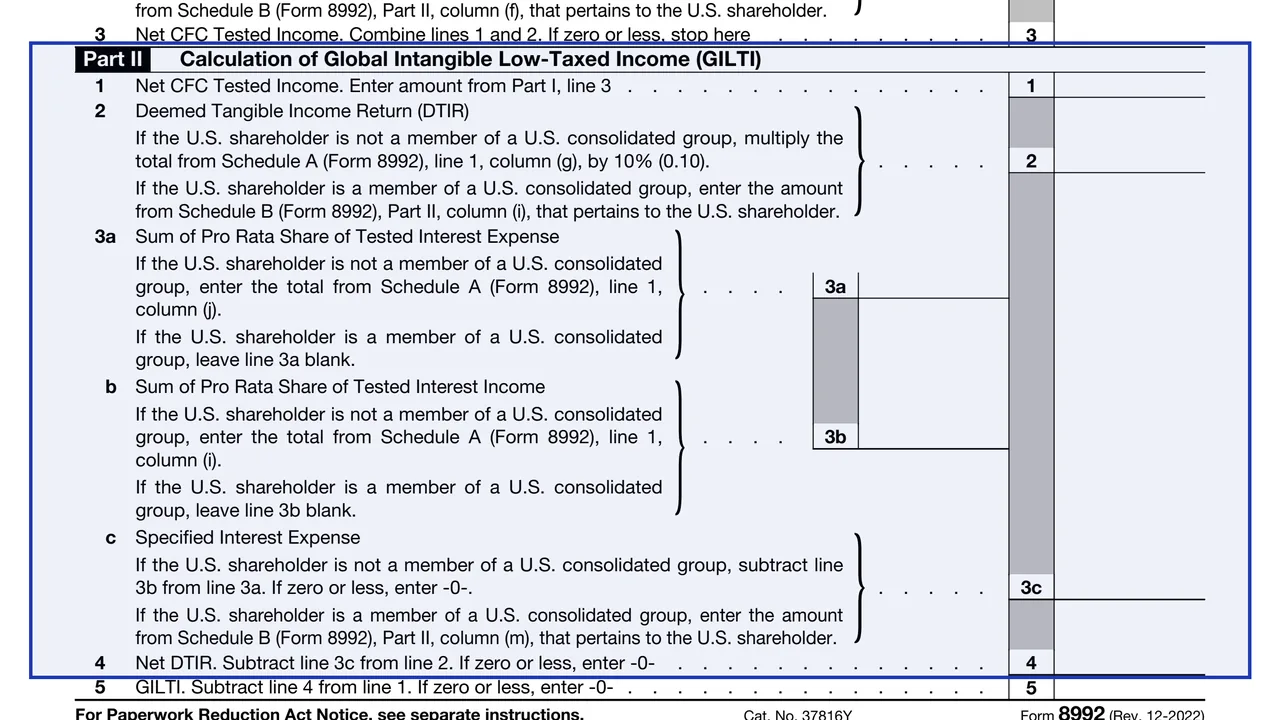
Subtract line 3c from line 2 for net DTIR, then line 4 from line 1 for GILTI. Each line says to enter -0- if the result is zero or less.
The instructions say a corporate shareholder enters line 5 on line 17 of Form 1120, Schedule C, an individual on line 8o of Schedule 1 (Form 1040), and an electing S corporation on Form 1120-S, Schedule K, line 10 (code E).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8992 and Schedule A to the income tax return (or exempt organization return, as applicable) and file both by the due date (including extensions) for that return.
Schedule B and one consolidated Form 8992 are attached to the group's return. The instructions say the Forms 8992 completed for each member are not filed but kept for the records.
The instructions say a corrected Form 8992 is filed with an amended tax return, with "Corrected" written at the top and a statement identifying the changes.
The instructions say penalties under sections 6038(b) and (c) may apply for failure to report the information required on the form.
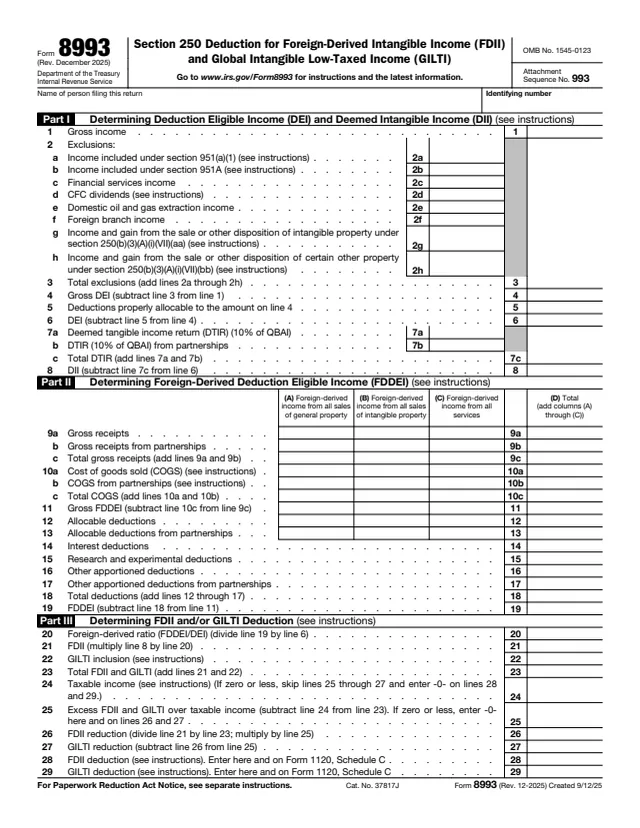
The instructions point to Form 8993 for a deduction under section 250 for a GILTI inclusion.
The instructions say a return position based on a U.S. treaty that overrides or modifies the Code and reduces tax is generally disclosed on Form 8833.
8992 Sch. A
268 fields, 2 pages
8992 Sch. B
499 fields, 4 pages
5471 Sch. I-1
35 fields, 1 page
8993
71 fields, 1 page
5471
437 fields, 6 pages
1120
481 fields, 6 pages
The instructions say Form 8992 is filed by a person who was a U.S. shareholder of at least one foreign corporation during the foreign corporation's tax year ending with or within the shareholder's tax year, and who owned stock in it, within the meaning of section 958(a), on the last day of that year in which it was a CFC.
No tool matches that search.
The About page says U.S. shareholders of controlled foreign corporations use Form 8992 and Schedule A to figure their GILTI inclusions under section 951A.
The instructions say domestic partnerships are no longer required to complete Form 8992 or Schedule A. They complete Part VI of Schedules K-2 and K-3 (Form 1065) instead.
The instructions say Schedule B is completed and attached when the U.S. shareholder is a member of a U.S. consolidated group.
The form says to stop at Part I, line 3. The instructions say Part II and Schedule A, columns (g) through (l), are then not completed, but Form 8992 and Schedule A are still included with the return.
The instructions name line 17 of Form 1120, Schedule C, for corporations and line 8o of Schedule 1 (Form 1040) for individuals, or the comparable line of other returns.
The instructions say to file a corrected Form 8992 with an amended return, write "Corrected" at the top and attach a statement identifying the changes.