Part I: Medicare wages
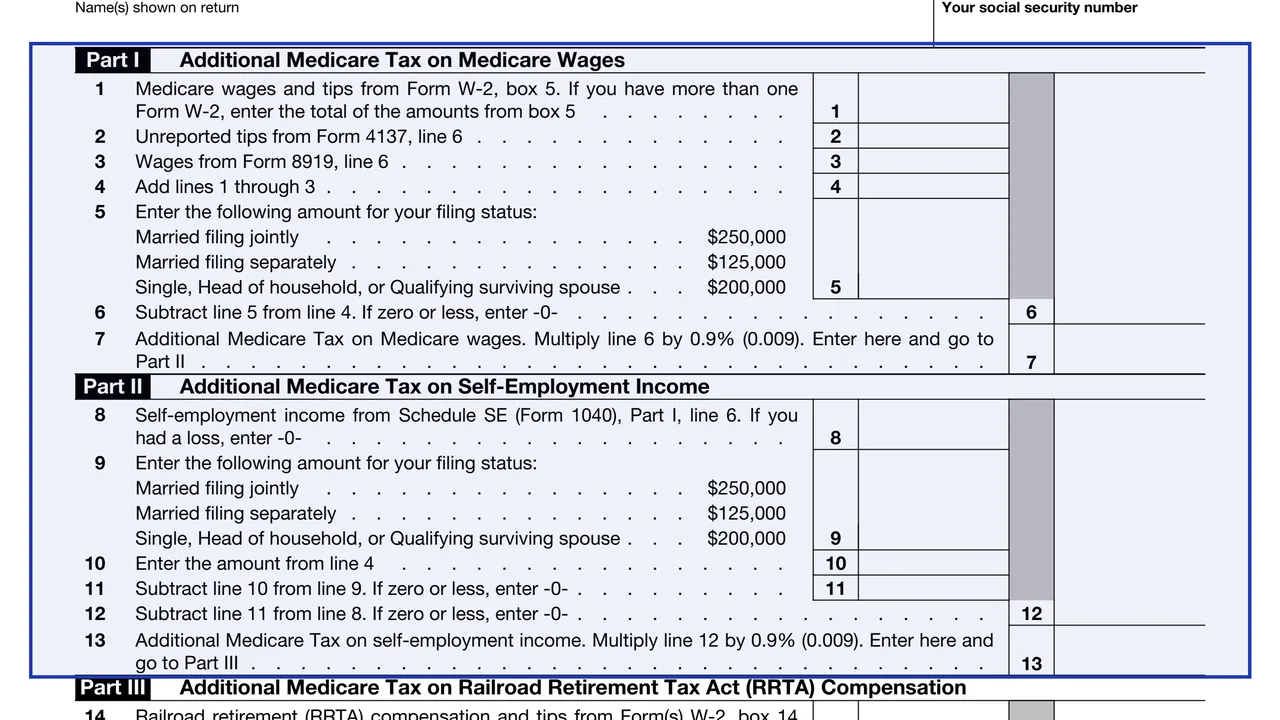
Lines 1 to 7 add Medicare wages and tips from Form W-2, unreported tips from Form 4137 and wages from Form 8919, subtract the threshold and multiply by 0.9%.
8959
Additional Medicare Tax
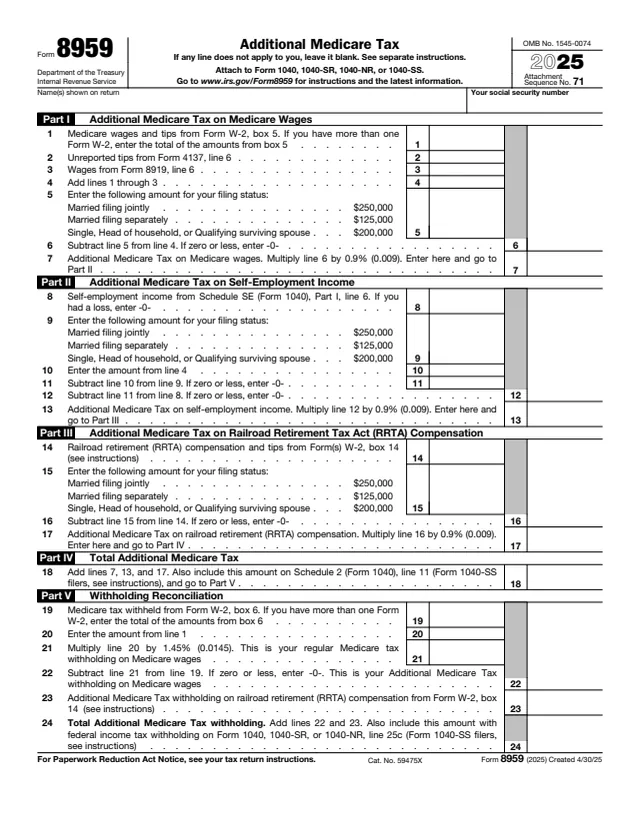
Form 8959 is used to figure the amount of Additional Medicare Tax owed and the amount of Additional Medicare Tax withheld by an employer, if any. This page covers the 2025 form. The instructions say a 0.9% Additional Medicare Tax applies to Medicare wages, Railroad Retirement Tax Act (RRTA) compensation and self-employment income above a threshold amount.
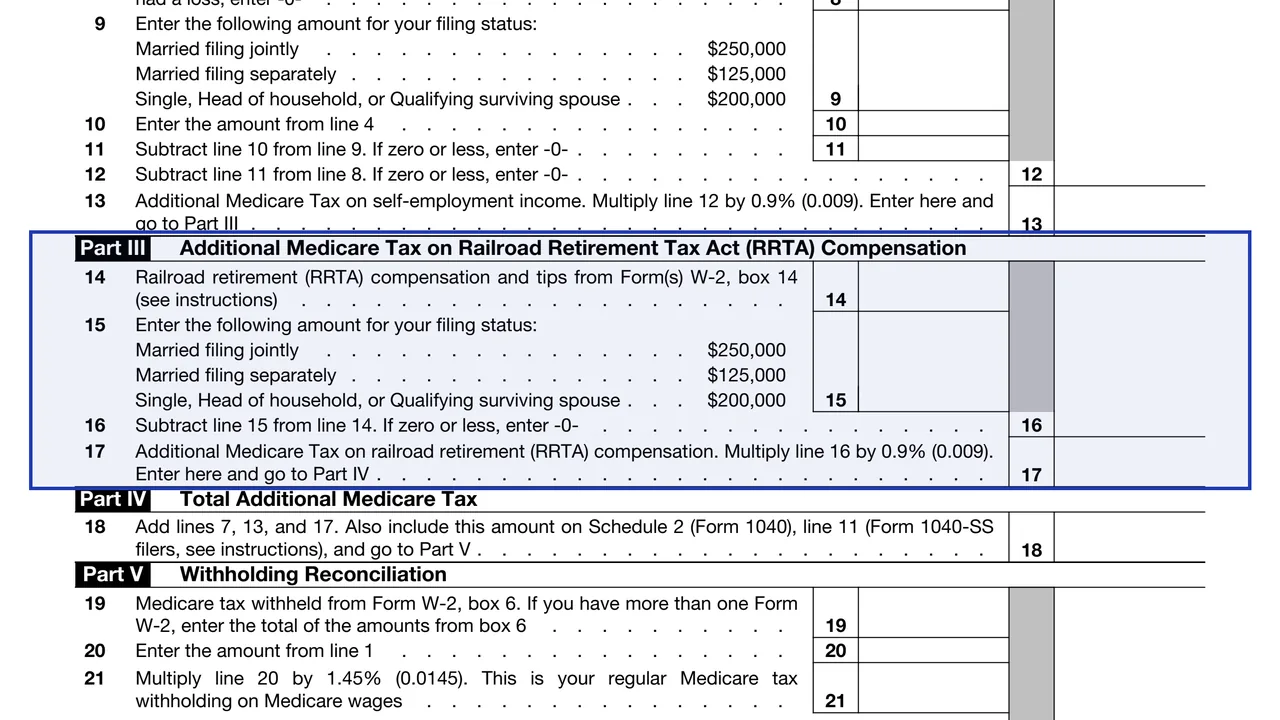
The form prints the threshold for each filing status: $250,000 for married filing jointly, $125,000 for married filing separately, and $200,000 for single, head of household or qualifying surviving spouse. The instructions note these amounts are not indexed for inflation. Wages and self-employment income are combined against the threshold, while RRTA compensation is compared separately.
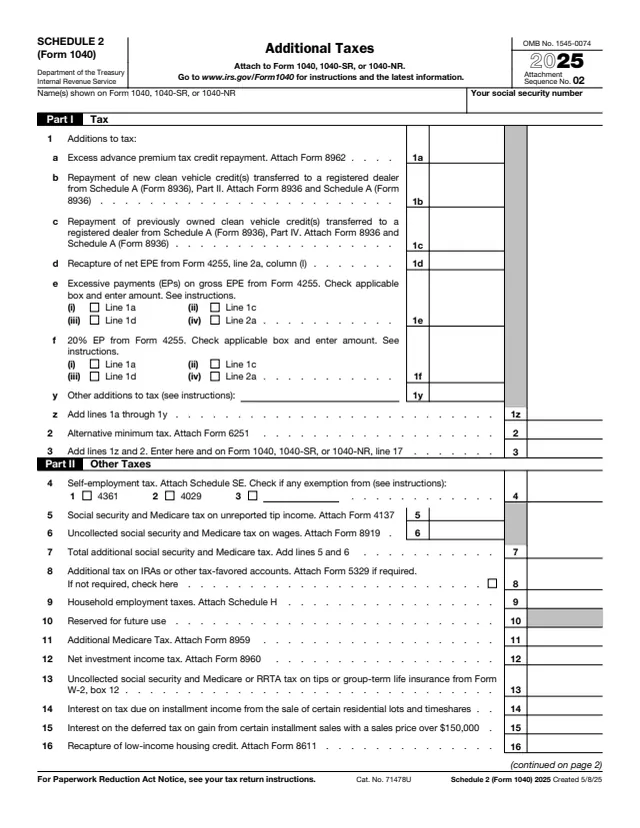
The form is attached to Form 1040, 1040-SR, 1040-NR or 1040-SS. The total tax goes to Schedule 2 (Form 1040) and the withholding goes to line 25c of the return. You can fill out Form 8959 free in your browser on this page and download the result without an account.
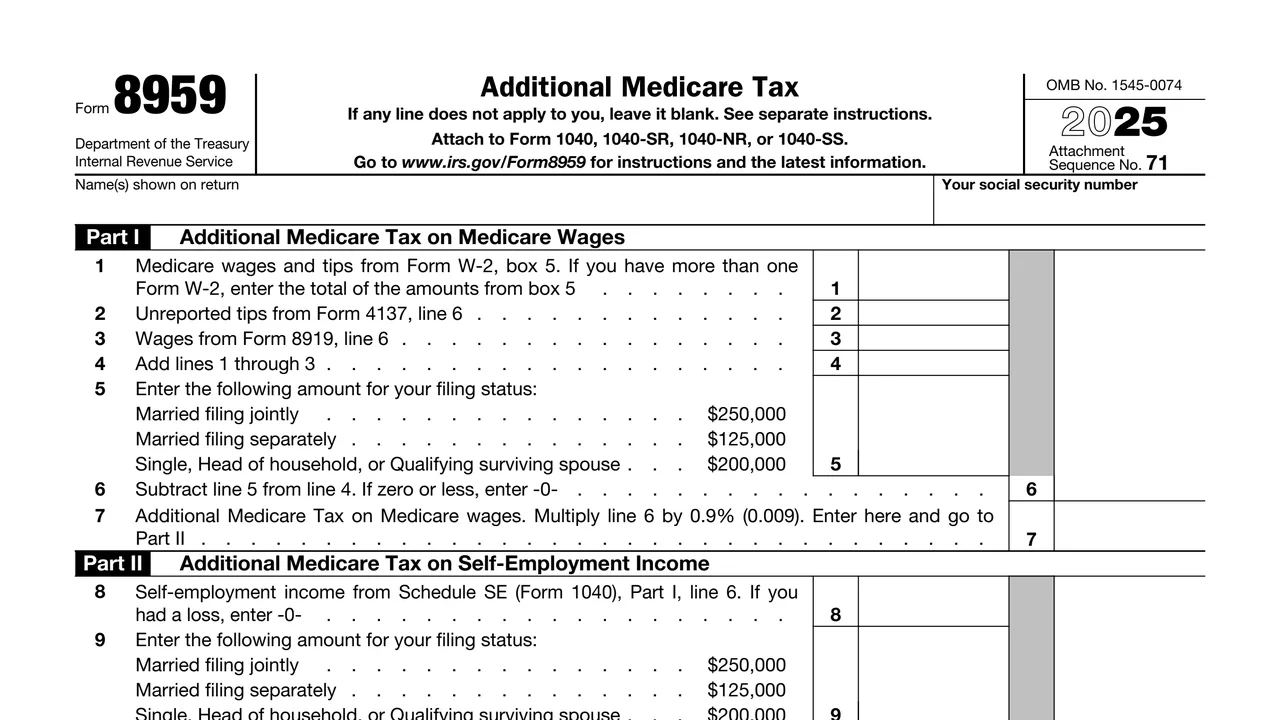
Lines 1 to 7 add Medicare wages and tips from Form W-2, unreported tips from Form 4137 and wages from Form 8919, subtract the threshold and multiply by 0.9%.
Lines 8 to 13 take self-employment income from Schedule SE, reduce the threshold by the Medicare wages on line 4, and multiply the excess by 0.9%.
Lines 14 to 17 take railroad retirement compensation and tips from Form W-2, box 14, subtract the threshold and multiply by 0.9%.
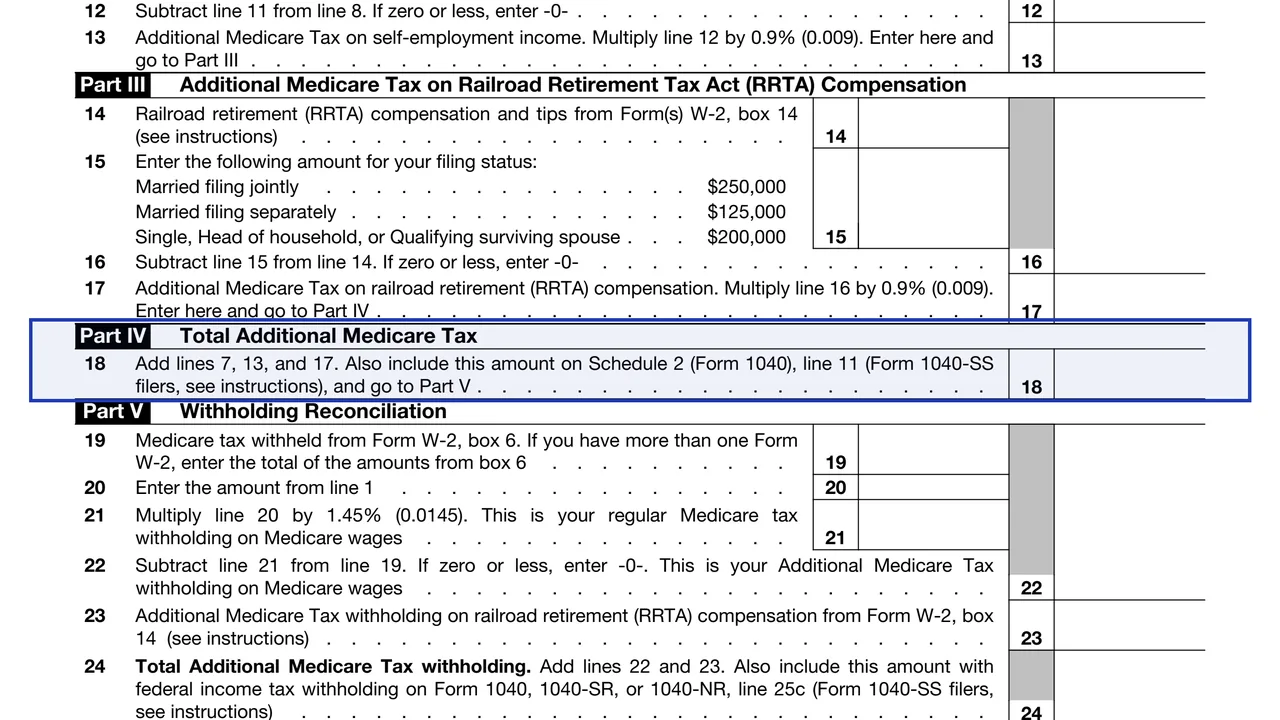
Line 18 adds lines 7, 13 and 17. The form says to include it on Schedule 2 (Form 1040), line 11.
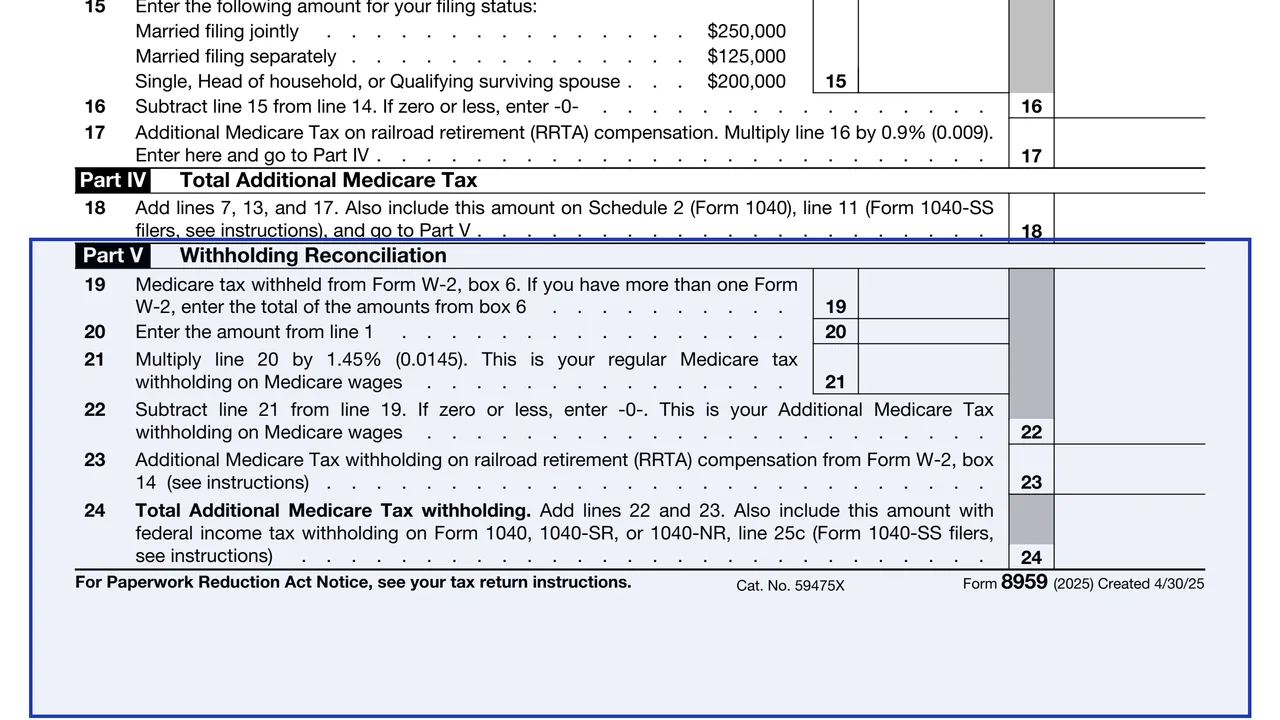
Lines 19 to 24 separate regular Medicare tax withholding at 1.45% from Additional Medicare Tax withholding on wages and RRTA compensation.
Enter the name or names exactly as on your return. On a joint return, the instructions say to enter the first social security number shown on the return.
Enter the total of box 5 from all Forms W-2, line 6 of Form 4137 and line 6 of Form 8919, including a spouse's amounts on a joint return. Enter the threshold for your filing status, subtract it and multiply by 0.9%.
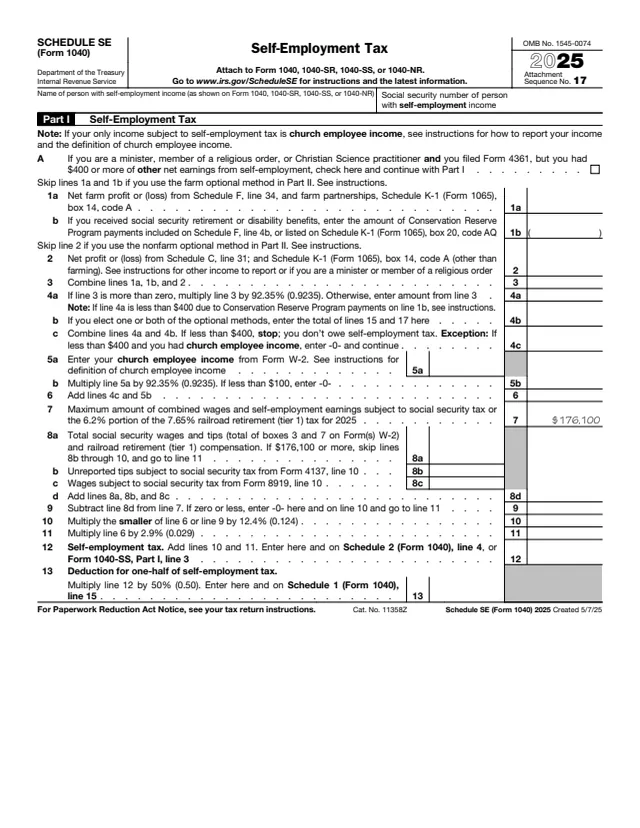
Enter self-employment income from Schedule SE, Part I, line 6, or -0- for a loss. Subtract line 4 wages from the threshold, then multiply the remaining excess by 0.9%.
Enter RRTA compensation and tips from box 14 of all Forms W-2. The instructions say an employee representative uses line 2 of Form CT-2. Subtract the threshold and multiply by 0.9%.
Add lines 7, 13 and 17. The instructions say this goes on Schedule 2 (Form 1040), line 11, or on line 5 of Part I of Form 1040-SS.
Enter Medicare tax withheld from box 6 of all Forms W-2, subtract 1.45% of line 1 wages, and add RRTA Additional Medicare Tax withheld from box 14. Line 24 goes on line 25c of Form 1040, 1040-SR or 1040-NR, or line 11a of Part I of Form 1040-SS.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR, 1040-NR or 1040-SS. It carries Attachment Sequence No. 71.
The instructions say an employer withholds the 0.9% Additional Medicare Tax on wages or RRTA compensation it pays in excess of $200,000 in a calendar year, regardless of filing status or wages paid by another employer.
If Medicare wages, RRTA compensation or self-employment income is adjusted, the instructions say to attach a corrected Form 8959 to the original or amended return, plus Form W-2 or Form W-2c when wages or RRTA compensation are corrected.
The instructions say references to Form W-2 also apply to Forms W-2AS, W-2CM, W-2GU, W-2VI and 499R-2/W-2PR. On Form 499R-2/W-2PR, Medicare wages and tips are in box 22 and Medicare tax withheld is in box 23.
The instructions say tips not reported to an employer as required may bring a penalty equal to 50% of the social security, Medicare and Additional Medicare taxes due on those tips, unless due to reasonable cause.
The instructions point to Form 1040-ES and Pub. 505 for estimated tax payments, and to Form 2210 for the estimated tax penalty.
1040
63 fields, 2 pages
1040
27 fields, 2 pages
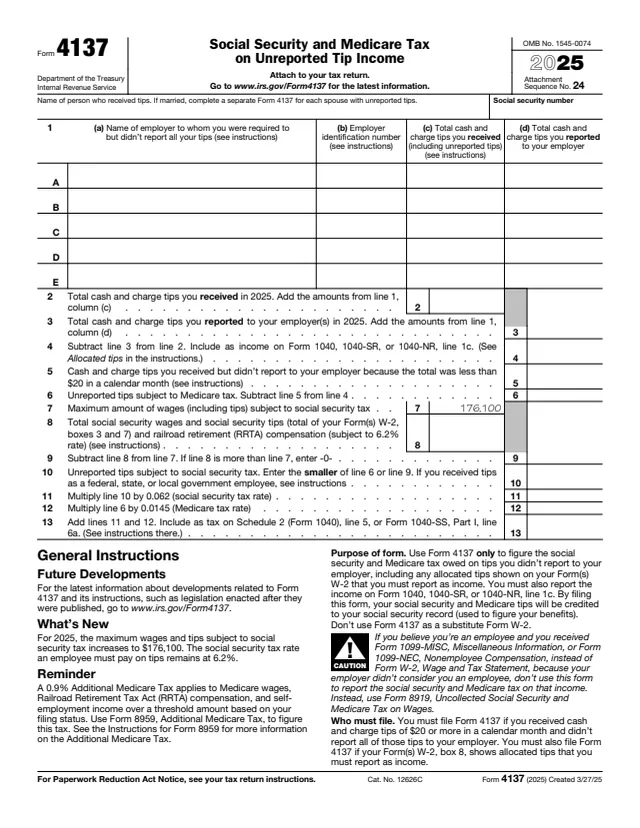
4137
34 fields, 2 pages
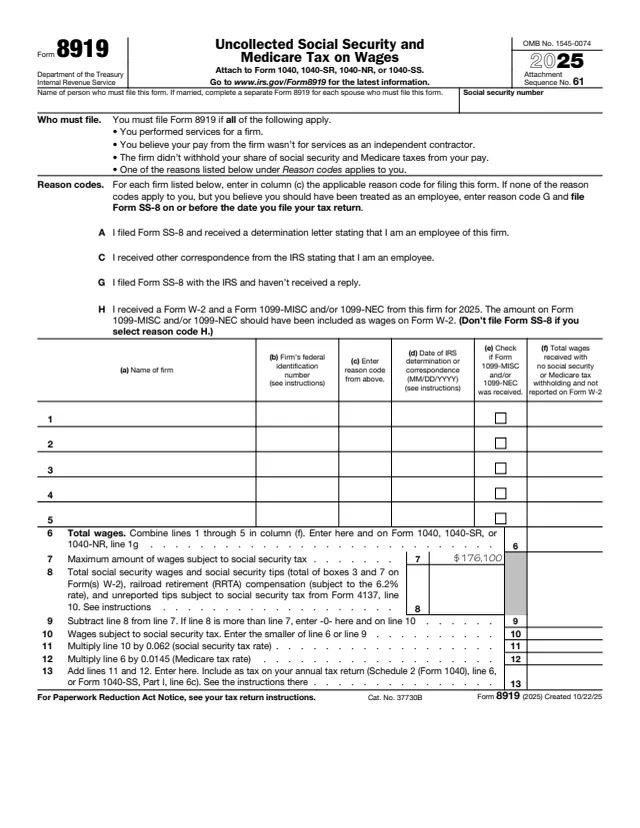
8919
40 fields, 2 pages
W-2
568 fields, 11 pages

1040
199 fields, 2 pages
The instructions list the situations in which an individual files Form 8959 with their own income tax return.
No tool matches that search.
The form and instructions say 0.9% (0.009) of Medicare wages, RRTA compensation and self-employment income above the threshold for your filing status.
The form prints $250,000 for married filing jointly, $125,000 for married filing separately, and $200,000 for single, head of household or qualifying surviving spouse. The instructions say they are not indexed for inflation.
No. The instructions say Medicare wages and self-employment income are combined, but RRTA compensation is compared to the threshold separately.
The instructions say you can claim a credit for withheld Additional Medicare Tax against the total tax on your return by filing Form 8959.
The instructions say you cannot ask your employer to stop Additional Medicare Tax withholding if it is required to withhold it.
Line 18 goes on Schedule 2 (Form 1040), line 11. Line 24 is included with federal income tax withholding on line 25c of Form 1040, 1040-SR or 1040-NR. Form 1040-SS filers use the lines the instructions name.