Donee information
The charitable organization's name, employer identification number and address.
8899
Notice of Income From Donated Intellectual Property
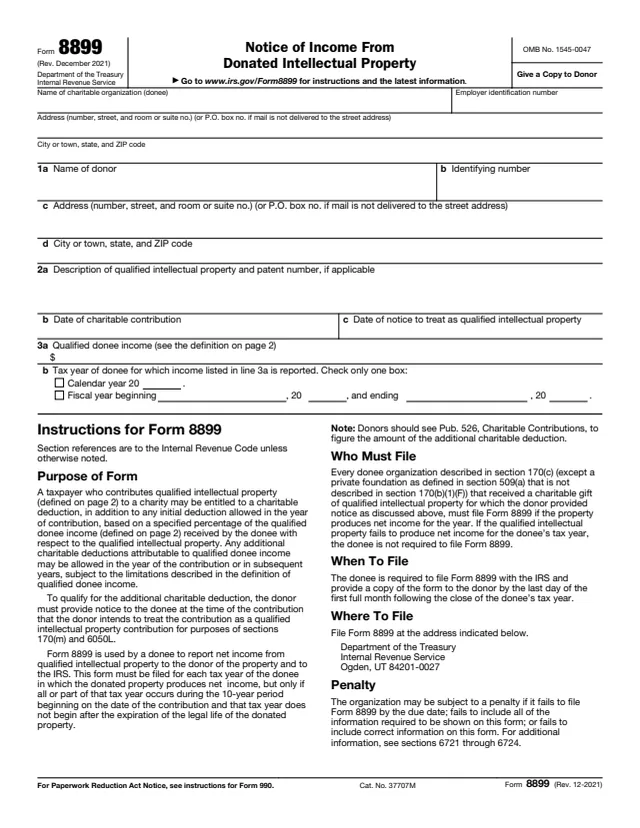
Form 8899 is the notice a charitable organization (the donee) uses to report net income from qualified intellectual property to the donor of the property and to the IRS. The About page describes it that way, and the form is marked "Give a Copy to Donor."
The instructions explain why it exists: a donor who contributes qualified intellectual property to a charity may be entitled to an additional charitable deduction based on a specified percentage of the qualified donee income the charity receives from that property. To qualify, the donor gives notice to the donee at the time of the contribution. The donee then files Form 8899 for each tax year in which the property produces net income, but only for a tax year that falls at least partly in the 10-year period beginning on the date of the contribution and does not begin after the legal life of the property expires.
The instructions point donors to Pub. 526, Charitable Contributions, to figure the additional deduction. You can fill out the PDF free in your browser on this page and download it without an account.
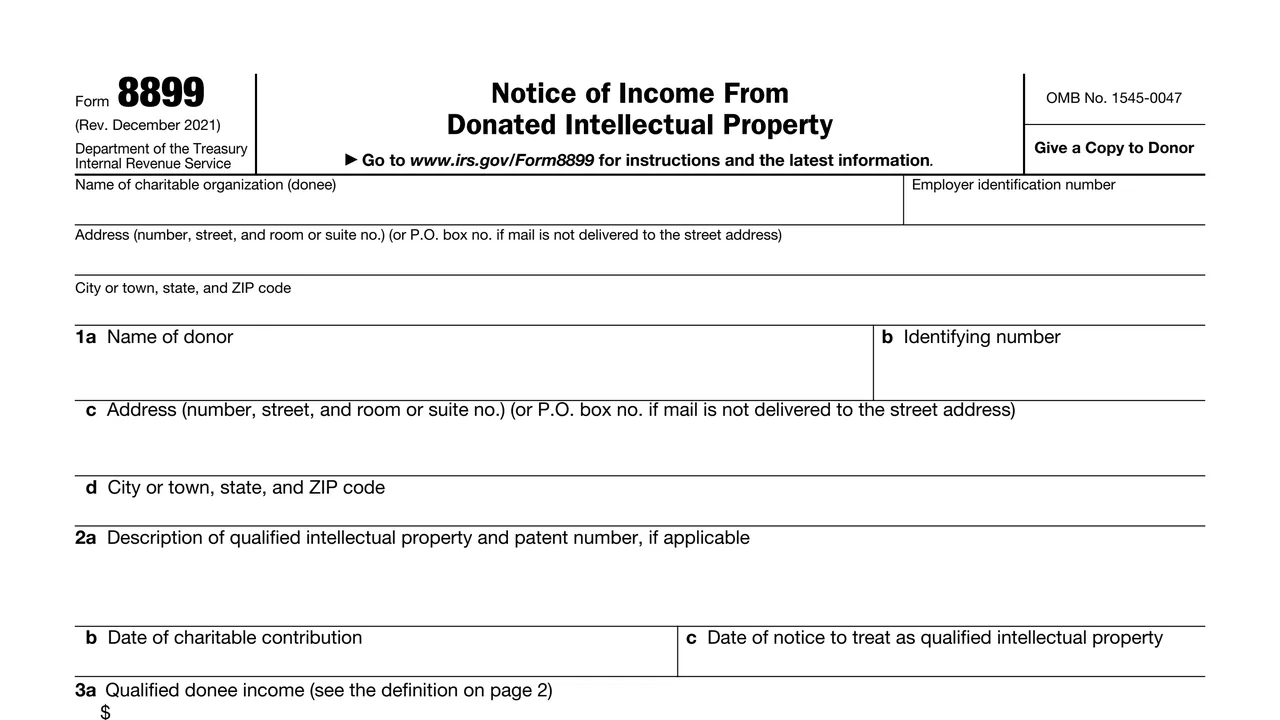
The charitable organization's name, employer identification number and address.
The donor's name, identifying number and address. The identifying number is a social security number for individual donors and an employer identification number for other donors.
A description of the qualified intellectual property with the patent number if applicable, the date of the charitable contribution, and the date of the notice to treat it as qualified intellectual property.
Line 3a holds the qualified donee income in dollars. Line 3b marks the donee's tax year as a calendar year or a fiscal year with its beginning and ending dates.
Enter the charity's name, EIN and address. The form says to use a P.O. box only if mail is not delivered to the street address.
Enter the donor's name, identifying number and address. The instructions say the donee may ask the donor to complete Form W-9 to get the identifying number.
Describe the qualified intellectual property, add the patent number if there is one, and enter the contribution date and the date of the donor's notice.
Enter the qualified donee income: net income received or accrued by the donee that is properly allocable to the property for the donee's tax year ending within or with the donor's tax year.
Check only one box: calendar year, with the year, or fiscal year, with the beginning and ending dates.
The instructions say some property is not qualified intellectual property, such as computer software readily available to the general public under a nonexclusive license and not substantially modified, and copyrights held by the taxpayer whose personal efforts created them.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the donee files Form 8899 with the IRS and gives a copy to the donor by the last day of the first full month following the close of the donee's tax year.
Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0027.
The form is filed for each tax year of the donee in which the donated property produces net income, within the 10-year period and the legal life limits in the instructions.
The instructions say the organization may be subject to a penalty for filing late, leaving out required information or including incorrect information, and point to sections 6721 through 6724.
The donee organization files the form and gives a copy to the donor. The donor does not file it.
No tool matches that search.
The donee, a charitable organization described in section 170(c) that received qualified intellectual property, other than certain private foundations. The donor gets a copy.
No. The donor receives a copy from the charity. The instructions point donors to Pub. 526 to figure the additional charitable deduction.
The instructions say by the last day of the first full month following the close of the donee's tax year.
The instructions say the donee is not required to file Form 8899 for a tax year in which the property fails to produce net income.
The instructions say generally any patent, copyright, trademark, trade name, trade secret, know-how, software or similar property, or applications or registrations of such property, with listed exceptions.
Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0027.