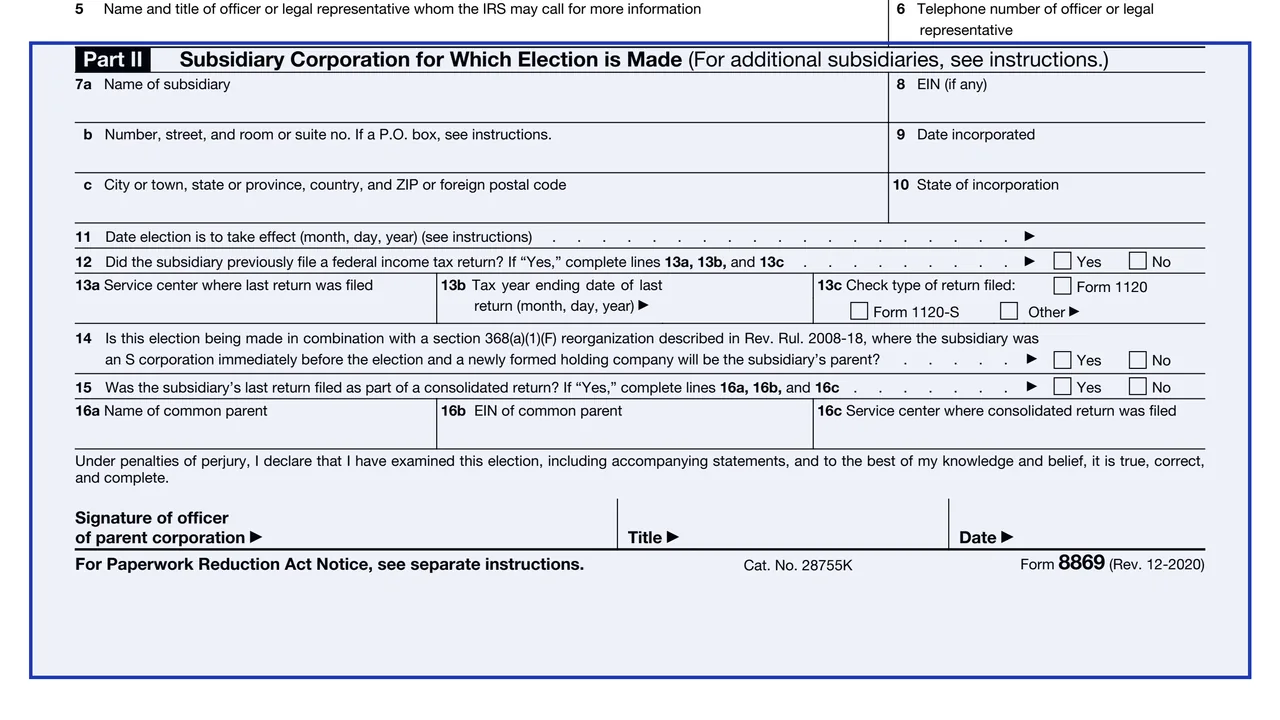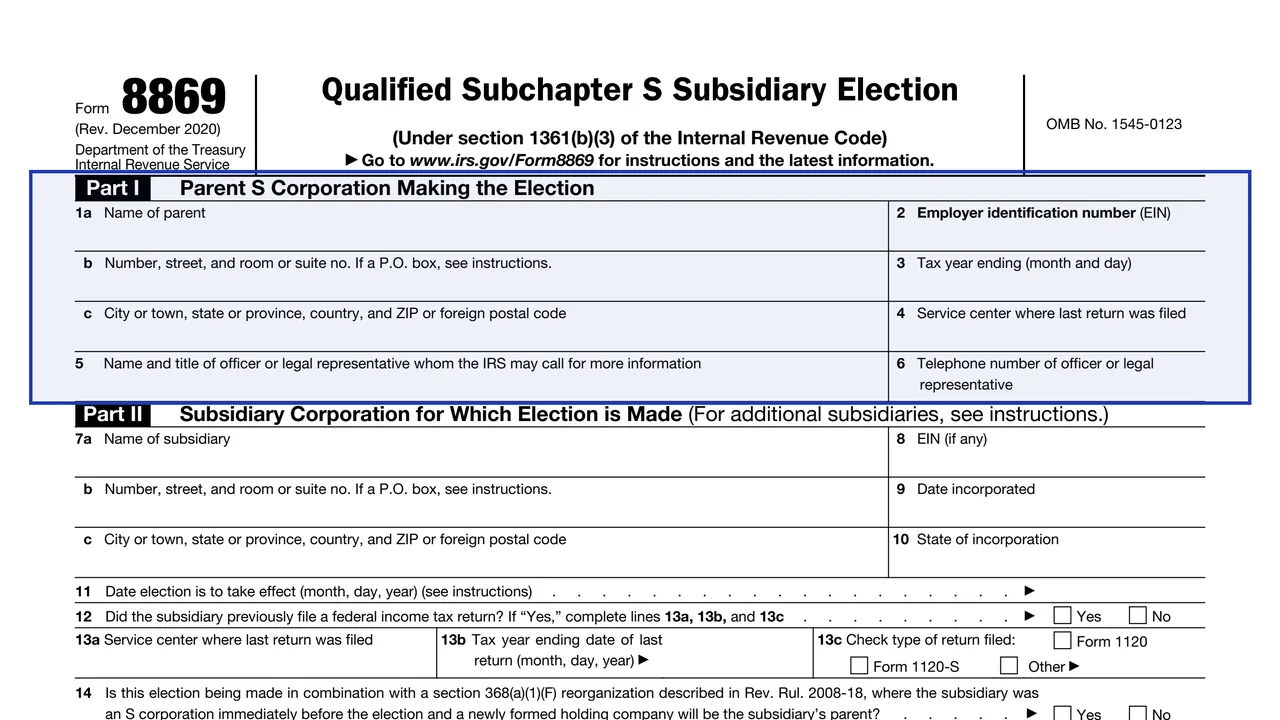
Part I, lines 1 to 4: parent
The parent's name and address, EIN, tax year ending (month and day) and the service center where its last return was filed.
8869
Qualified Subchapter S Subsidiary Election
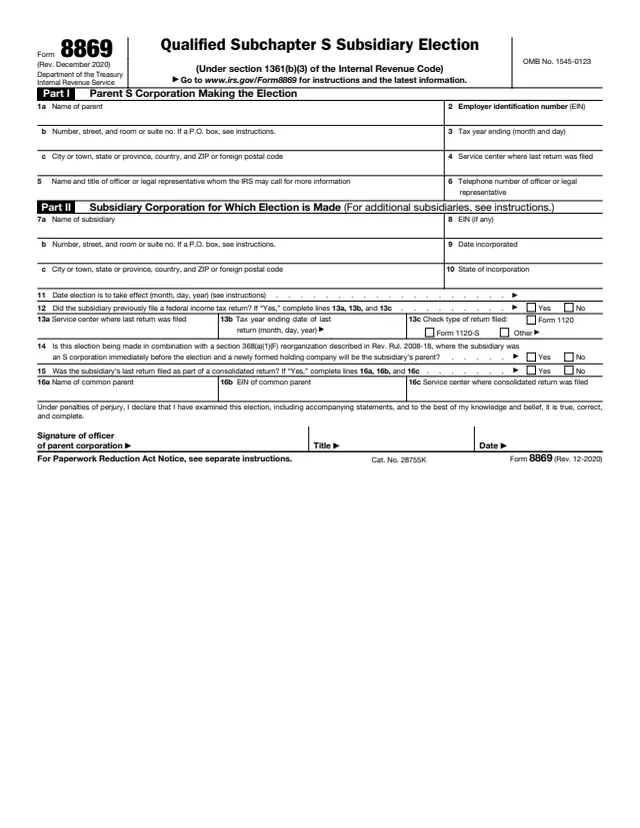
Form 8869, Qualified Subchapter S Subsidiary Election, is the form a parent S corporation uses to elect to treat one or more of its eligible subsidiaries as a qualified subchapter S subsidiary (QSub). The form notes that the election is made under section 1361(b)(3) of the Internal Revenue Code.
The instructions say the QSub election results in a deemed liquidation of the subsidiary into the parent. After that, for federal tax purposes, the QSub is not treated as a separate corporation, and all of its assets, liabilities, and items of income, deduction, and credit are treated as those of the parent. Because the liquidation is deemed, the instructions say not to file Form 966.
The form has a part for the parent S corporation, a part for the subsidiary and a signature by an officer of the parent. You can fill it out free in your browser on this page and download the result without an account.
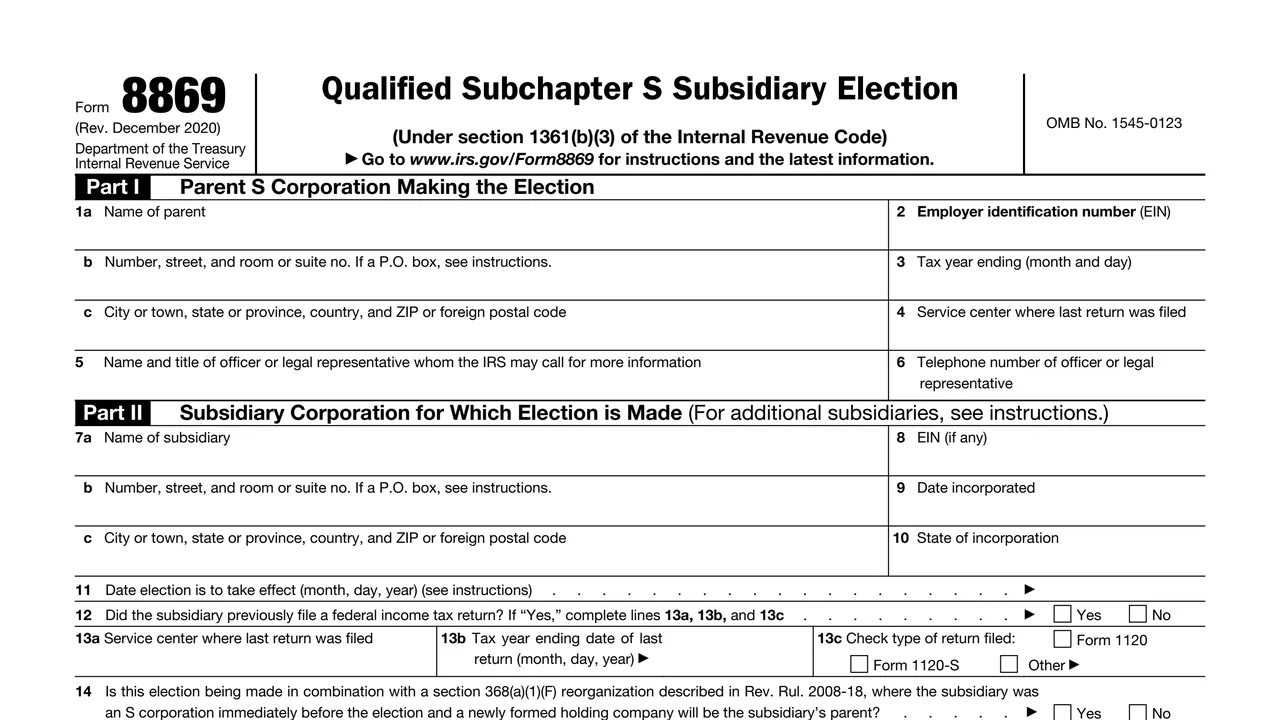
The parent's name and address, EIN, tax year ending (month and day) and the service center where its last return was filed.
The name and title of the officer or legal representative whom the IRS may call for more information, and that person's telephone number.
The subsidiary's name and address, EIN (if any), date incorporated and state of incorporation.
The date the election is to take effect, as month, day and year.
Whether the subsidiary filed a federal income tax return before (service center, tax year end and Form 1120, 1120-S or other), the line 14 reorganization question, and whether its last return was part of a consolidated return.
A declaration under penalties of perjury, then the signature of an officer of the parent corporation, the title and the date.
Include the suite, room or other unit number after the street address. Show a P.O. box only if the post office does not deliver to the street address. If the subsidiary has the same address as the parent, enter "Same as parent" in Part II.
The instructions say a QSub may not be required to have an EIN. Enter "N/A" if it has none, the EIN it used on earlier returns if it has one, or "Applied For" if an EIN was requested but not yet received.
A parent that forms a new subsidiary and wants the election effective upon formation enters the formation date. For an existing subsidiary, enter the requested effective date.
Check Yes if the election is made under a reorganization under section 368(a)(1)(F) and Rev. Rul. 2008-18. The instructions say no Form 2553 is required to be filed by the parent in that case.
Attach a separate sheet for each additional subsidiary, using the same size, format and line numbers as Part II, with the parent's name and EIN at the top of each sheet.
An authorized officer of the parent S corporation signs, enters a title and dates the election.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
With the service center where the subsidiary filed its most recent return. If the parent forms a subsidiary and makes a valid election effective upon formation, the instructions say to submit it where the parent filed its most recent return.
The instructions say the requested effective date generally cannot be more than 12 months after the date the election is filed, or 2 months and 15 days before the date it is filed.
An election filed more than 2 months and 15 days after the requested effective date generally is late. The instructions say it is accepted as timely if the corporation shows reasonable cause, and point to Rev. Proc. 2013-30 for relief.
The instructions say a determination generally arrives within 60 days. If there is no notice of acceptance or nonacceptance within 2 months of the date of filing, they say to call 800-829-4933.
The instructions accept a timely postmarked certified or registered mail receipt, a Form 8869 with an accepted stamp or a stamped IRS received date, or an IRS letter stating it has been accepted.
The election stays in effect until terminated. After a termination, IRS consent generally is required for another QSub election for the former QSub for any tax year before the fifth tax year after the termination took effect.
2553
100 fields, 4 pages
SS-4
89 fields, 2 pages
966
29 fields, 2 pages
1120-S
390 fields, 5 pages
1120
481 fields, 6 pages
The parent S corporation files it, and an officer of the parent signs it. It goes to an IRS service center.
No tool matches that search.
No. The instructions say that because the liquidation is a deemed liquidation, Form 966 is not filed. A final return for the subsidiary may have to be filed if it was a separate corporation before the deemed liquidation.
The instructions say a QSub may not be required to have an EIN for federal tax purposes. If it has none, enter "N/A" on line 8.
Yes. The instructions say to attach a separate sheet for each additional subsidiary in the Part II format. For a tiered group effective on the same date, the parent may specify the order of the deemed liquidations.
A corporate officer authorized to sign the parent's S corporation return, such as the president, vice president, treasurer, assistant treasurer, chief accounting officer or tax officer.
The instructions say the corporation should generally receive a determination within 60 days after filing Form 8869.
With the service center where the subsidiary filed its most recent return, or where the parent filed its most recent return when the subsidiary is newly formed and the election is effective upon formation.