8855

Election To Treat a Qualified Revocable Trust as Part of an Estate

Agency
IRS
Revision
Rev. December 2020
Fillable fields
23
Pages
4
Official source
IRS form page
Checked
October 21, 2026
Fill 8855 online
Page 1 of form 8855

Form 8855: Election To Treat a Qualified Revocable Trust as Part of an Estate

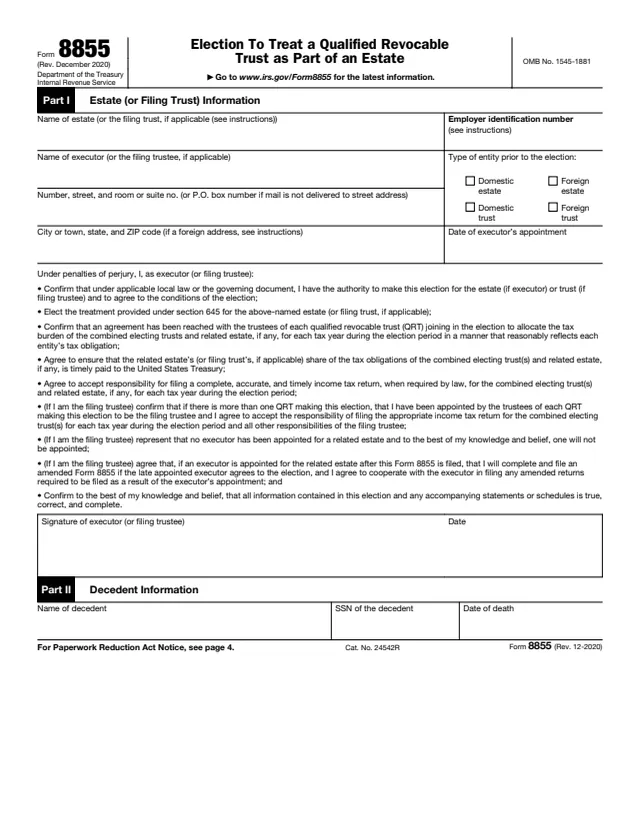
Form 8855 is how the trustees of each qualified revocable trust (QRT) and the executor of the related estate, if any, make a section 645 election. The IRS says this election allows a QRT to be treated and taxed, for income tax purposes, as part of its related estate during the election period, and that once the election is made it cannot be revoked.

The instructions define a QRT as a trust, or part of a trust, that on the day the decedent died was treated as owned by the decedent under section 676 by reason of a power to revoke. During the election period, the electing trusts and the related estate file one combined income tax return and are treated as one estate for that return. The form is completed by fiduciaries: the executor or a filing trustee in Part I, and the trustee of each QRT in Part III. The instructions are printed on pages 3 and 4 of the form.

You can fill out Form 8855 free in your browser on this page and download it without an account.

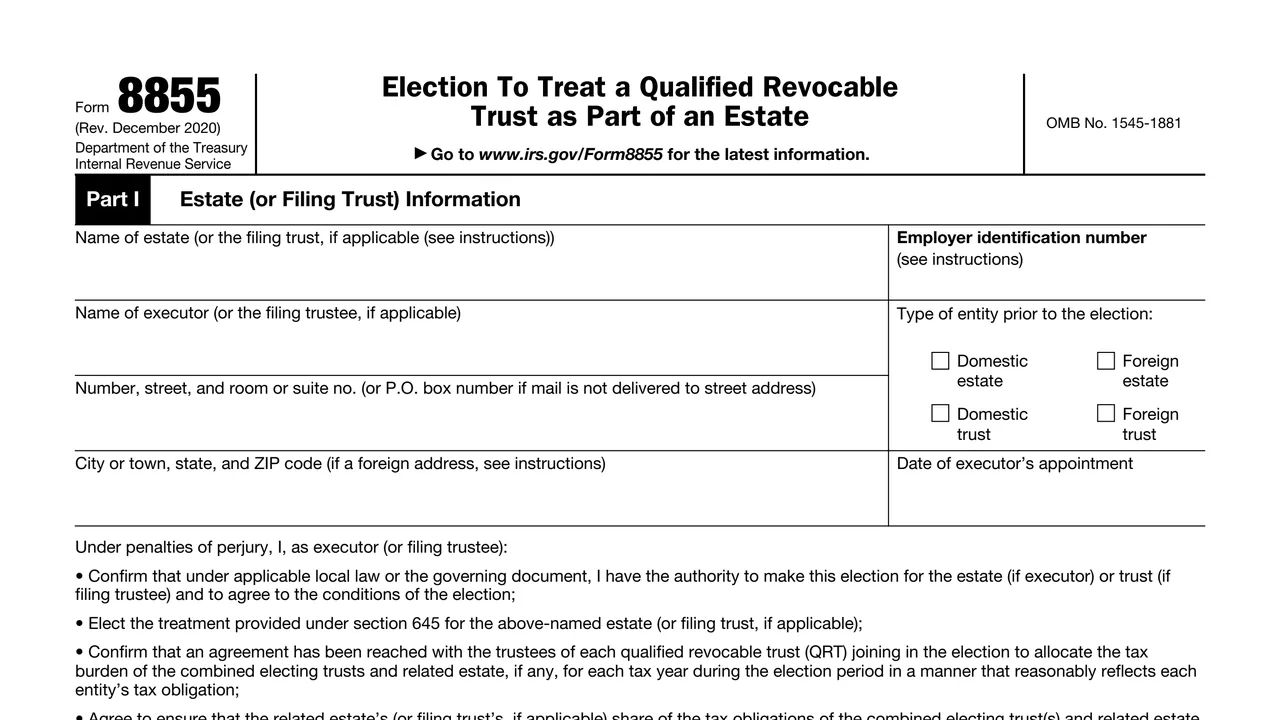
Top of page 1 of Form 8855: Election To Treat a Qualified Revocable Trust as Part of an Estate, as printed by IRS

What's on Form 8855

Part I: Estate (or Filing Trust) Information

Name and EIN of the estate or filing trust, the executor or filing trustee and address, the type of entity before the election (domestic or foreign estate or trust) and the date of the executor's appointment.
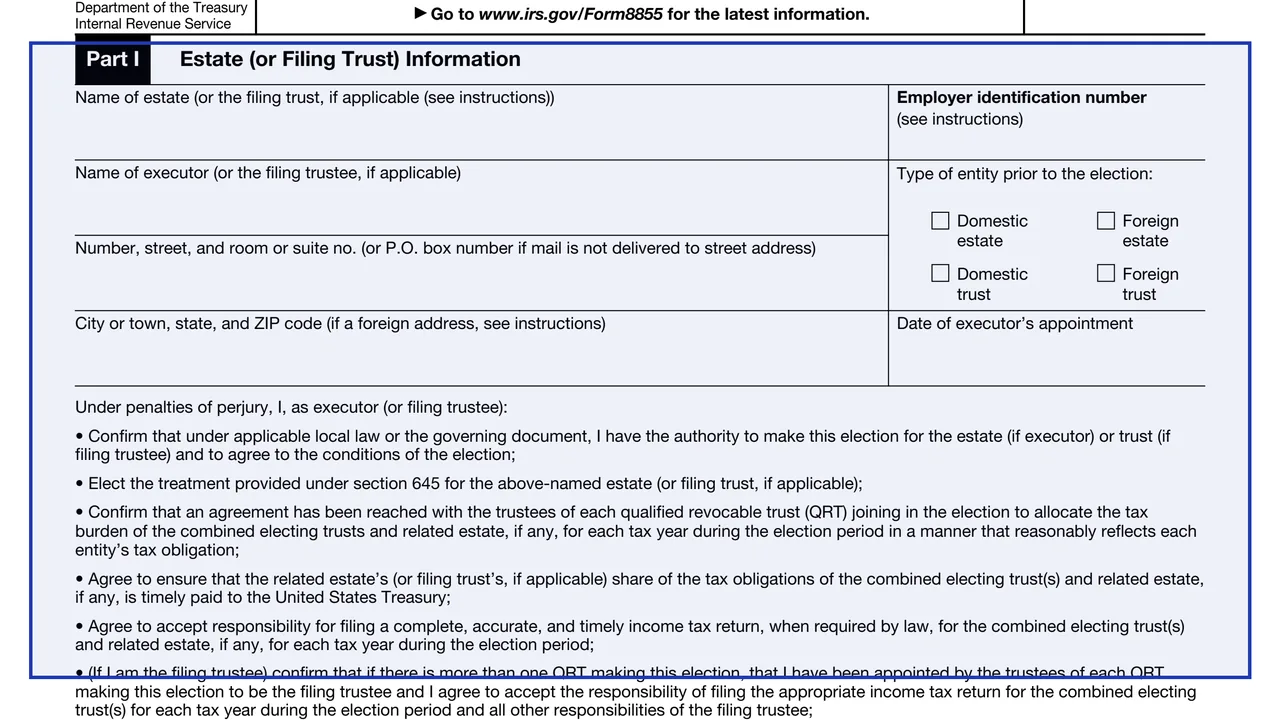
Part I: executor's statements and signature

Statements made under penalties of perjury about authority, the tax burden allocation agreement, payment and filing responsibility, followed by the signature and date.

Part II: Decedent Information

The decedent's name, Social Security number and date of death.

Part III: Qualified Revocable Trust Information

For each QRT, the trust name and EIN, trustee name and address, and the trustee's statements and signature. Page 2 has room for two trusts.

How to fill out Form 8855

  1. 1

    Get the EINs first

    The instructions say the trustee of a QRT obtains a new EIN for the trust upon the decedent's death, and Parts I and III ask for that new EIN. The executor obtains an EIN for the estate before filing.

  2. 2

    Part I

    The executor, or the filing trustee if there is no executor, enters the estate or filing trust details, checks the entity type, and signs and dates. For a foreign address, enter city, province or state, and country, without abbreviating the country name.

    Part I on page 1 of Form 8855: Election To Treat a Qualified Revocable Trust as Part of an Estate, as printed by IRS
  3. 3

    Part II

    The executor, or filing trustee if there is no executor, enters the decedent's name, SSN and date of death.

  4. 4

    Part III for each trust

    The trustee of each QRT joining the election enters the trust details and signs and dates. With extra Part III pages, the executor or filing trustee notes on the first Part III page how many pages are attached and the total number of QRTs.

  5. 5

    Amended election

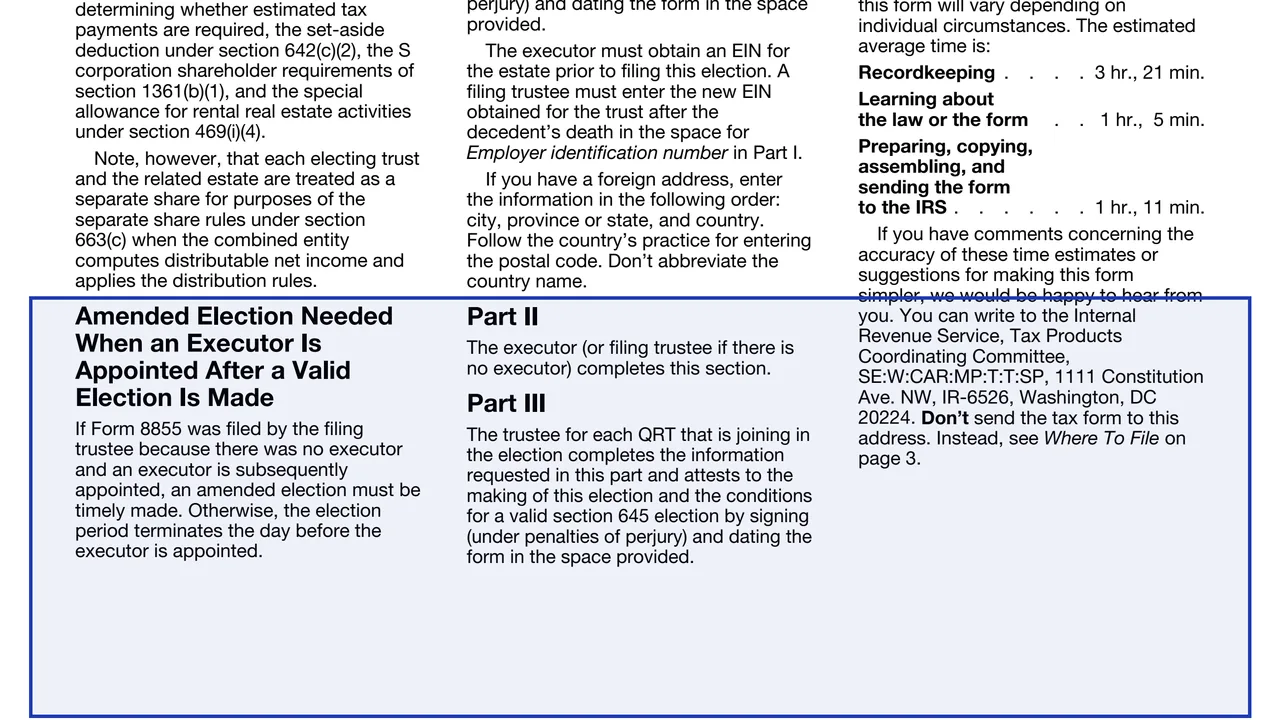
    If a filing trustee filed and an executor is appointed later, the executor and trustees file a new Form 8855 with "AMENDED ELECTION" written at the top, within 90 days of the executor's appointment.

    Amended election on page 4 of Form 8855: Election To Treat a Qualified Revocable Trust as Part of an Estate, as printed by IRS

Why fill Form 8855 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

When and where to file, and what to keep

When to file

The instructions say to file the election by the due date, including extensions, of the Form 1041 (or Form 1040-NR) for the first tax year of the related estate or filing trust, even if no Form 1041 is otherwise required.

General due date

The instructions say the due date for the first income tax return is generally the 15th day of the 4th month after the close of the first tax year of the related estate, with exceptions in Regulations section 1.6072-1(c).

Where to file

The form's chart sends it to the Internal Revenue Service Center in Kansas City, MO 64999 or Ogden, UT 84201, depending on the state where you are located. The About page also lists mailing addresses by state.

Election period

It begins on the date of death and ends on the earlier of the day all electing trusts and the estate have distributed all assets or the day before the applicable date, which depends on whether a Form 706 is required.

Keep a copy

The instructions say the executor and the trustee of each electing trust keep a copy of the completed Form 8855, any amended form, and proof that it was timely filed.

Who completes Form 8855?

  • Executor of the related estate

    Completes Part I and Part II and signs under penalties of perjury. The instructions say the executor obtains an EIN for the estate before filing the election.

  • Filing trustee when there is no executor

    A trustee appointed by the trustees of each electing trust to file the combined returns. If there is no executor and only one QRT, the trustee of that trust is the filing trustee.

  • Trustee of each QRT joining the election

    Completes and signs a Part III for the trust. Space is provided for two QRTs, and additional Parts III are used for more.

  • One signer per entity

    The instructions say that where an estate has more than one executor or a trust more than one trustee, only one signs for the entity unless local law or the governing document requires otherwise.

The form is signed by fiduciaries of the estate and the trusts, not by beneficiaries.

Official sources and the blank

Do it all with indox

View all 94 tools

Questions about Form 8855

Can the section 645 election be revoked?

No. The IRS says that once the election is made, it cannot be revoked.

How long does the election last?

The instructions say the election period starts on the date of death. If no Form 706 is required, the applicable date is 2 years after the date of death. If one is required, it is the later of 2 years after death or 6 months after the final determination of estate tax liability.

What return is filed during the election period?

The instructions say all electing trusts and the related estate, if any, file one combined income tax return, Form 1041 or Form 1040-NR for a foreign estate.

What if there is no executor?

A filing trustee appointed by the trustees of each electing trust completes Part I. If an executor is appointed later, the instructions call for an amended election within 90 days of the appointment.

Does a revocable trust need a new EIN?

The instructions say the trustee of a QRT obtains a new EIN for the trust upon the decedent's death and enters it on the form.