Consenting corporation
The name of the consenting corporation and its employer identification number.
8848
Consent To Extend the Time To Assess the Branch Profits Tax Under Regulations Sections 1.884-2(a) and (c)
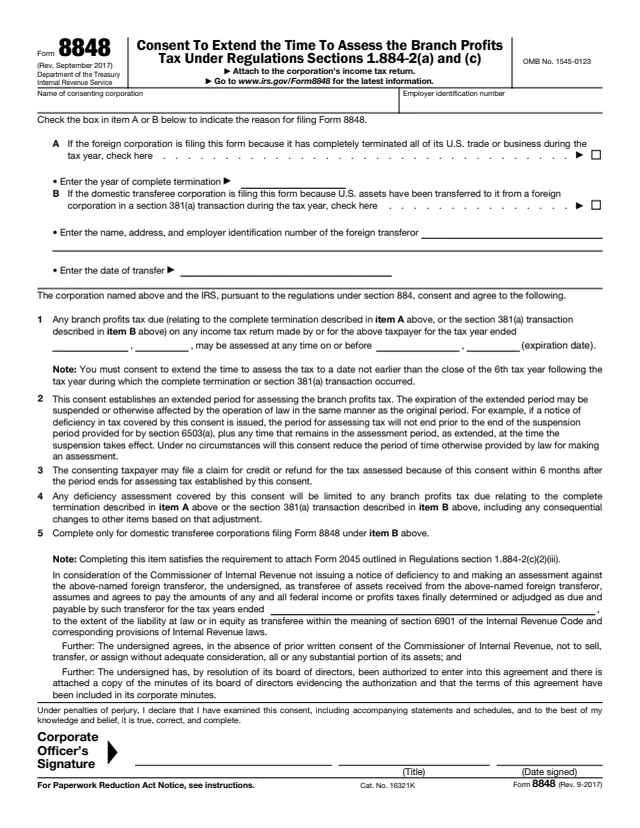
Form 8848, Consent To Extend the Time To Assess the Branch Profits Tax Under Regulations Sections 1.884-2(a) and (c), is a corporate form. The consenting corporation and the IRS agree, under the regulations under section 884, that branch profits tax related to a complete termination or a section 381(a) transaction may be assessed up to an expiration date entered on the form.
The IRS About page says foreign corporations file it if they have completely terminated all of their U.S. trade or business according to Temporary Regulations section 1.884-2T(a) during the tax year. A domestic transferee corporation files it if U.S. assets were transferred to it from a foreign corporation in a section 381(a) transaction, if the foreign corporation was engaged (or deemed engaged) in a U.S. trade or business immediately before the transaction.
The form is attached to the corporation's income tax return, and its instructions are on page 2. This page hosts the September 2017 revision. You can fill out Form 8848 free in your browser on this page and download the result without an account.
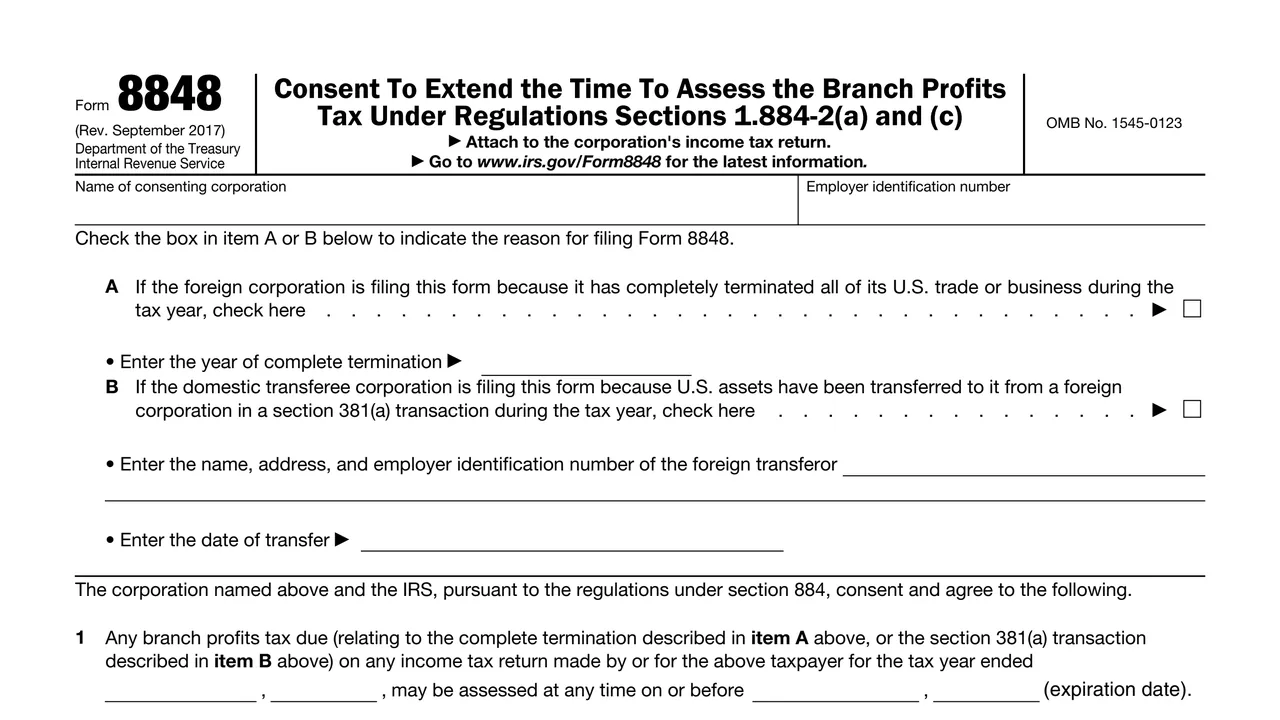
The name of the consenting corporation and its employer identification number.
Item A asks for the year of complete termination. Item B asks for the foreign transferor's name, address and EIN and the date of transfer.
The tax year covered and the expiration date on or before which any related branch profits tax may be assessed.
How the extended period works, a 6-month window for a claim for credit or refund, and the limit of any deficiency assessment to the related branch profits tax.
For domestic transferee corporations under item B only. The transferee assumes and agrees to pay the foreign transferor's federal income or profits taxes for the tax years entered, to the extent of its liability as transferee.
A declaration under penalties of perjury, the corporate officer's signature, title and date signed.
Enter the name of the consenting corporation and its employer identification number.
Check item A and enter the year of complete termination, or check item B and enter the foreign transferor's name, address and EIN and the date of transfer.
Enter the tax year end and the expiration date. The note on the form says the extension runs to a date not earlier than the close of the 6th tax year following the tax year in which the complete termination or section 381(a) transaction occurred.
A domestic transferee corporation filing under item B enters the tax years covered. The form says completing this item satisfies the requirement to attach Form 2045 under Regulations section 1.884-2(c)(2)(iii), and refers to an attached copy of the board of directors' minutes authorizing the agreement.
The corporate officer signs, enters a title and dates the form. An agent signing for the corporation includes a copy of the power of attorney.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8848 to the corporation's return for the tax year during which the complete termination or section 381(a) transaction occurred.
The instructions say it is filed on or before the due date (including extensions) for the corporation's income tax return.
The instructions say a corporation that timely filed without executing the consent may still execute it by filing an amended return within 6 months of the due date of the original return (excluding extensions).
Attach Form 8848 to the amended return, write "Filed pursuant to section 301.9100-2" at the top of Form 8848, and file the amended return at the same address as the original.
Item 3 says the consenting taxpayer may file a claim for credit or refund for tax assessed because of the consent within 6 months after the extended assessment period ends.
The form and its About page name two kinds of corporations. The filer checks the box in item A or item B to show the reason for filing.
No tool matches that search.
The form says a foreign corporation that completely terminated all of its U.S. trade or business during the tax year, or a domestic transferee corporation that received U.S. assets from a foreign corporation in a section 381(a) transaction.
It is a consent between the corporation and the IRS that establishes an extended period for assessing the branch profits tax related to the termination or transaction.
The instructions say on or before the due date (including extensions) of the corporation's income tax return, attached to the return for the year of the termination or transaction.
The note on the form says the extension runs to a date not earlier than the close of the 6th tax year following the tax year in which the complete termination or section 381(a) transaction occurred.
The instructions say it may still be executed by filing an amended return within 6 months of the original due date (excluding extensions), with "Filed pursuant to section 301.9100-2" written at the top of Form 8848.
The person authorized to sign the corporation's income tax returns, including an agent under a power of attorney. An agent includes a copy of the power of attorney.