Lines A to C: parent
The parent's name and social security number, and a box for the parent's filing status. The form says to see the instructions before completing them.
8615
Tax for Certain Children Who Have Unearned Income
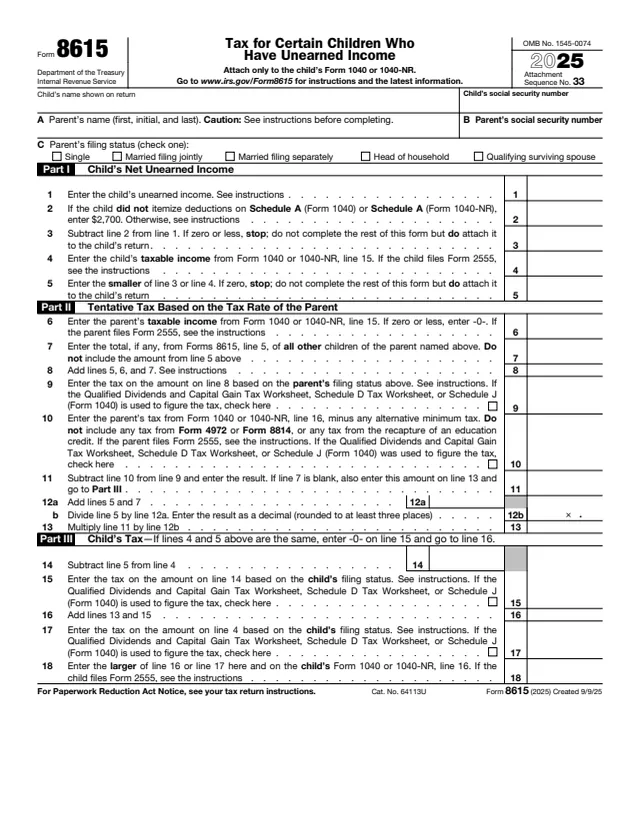
Form 8615, Tax for Certain Children Who Have Unearned Income, figures a child's tax when part of the child's unearned income is taxed at a parent's rate. The 2025 instructions say that for children under age 18 and certain older children, unearned income over $2,700 is taxed at the parent's rate if the parent's rate is higher than the child's, and that Form 8615 is used to figure the child's tax when the child's unearned income is more than $2,700.
The instructions describe unearned income as generally all income other than salaries, wages, and other amounts received as pay for work actually performed, such as taxable interest, dividends, capital gains, rents and royalties. The form is part of the child's own return: it says "Attach only to the child's Form 1040 or 1040-NR."
This is the 2025 edition. You can fill out Form 8615 free in your browser on this page and download it without an account.
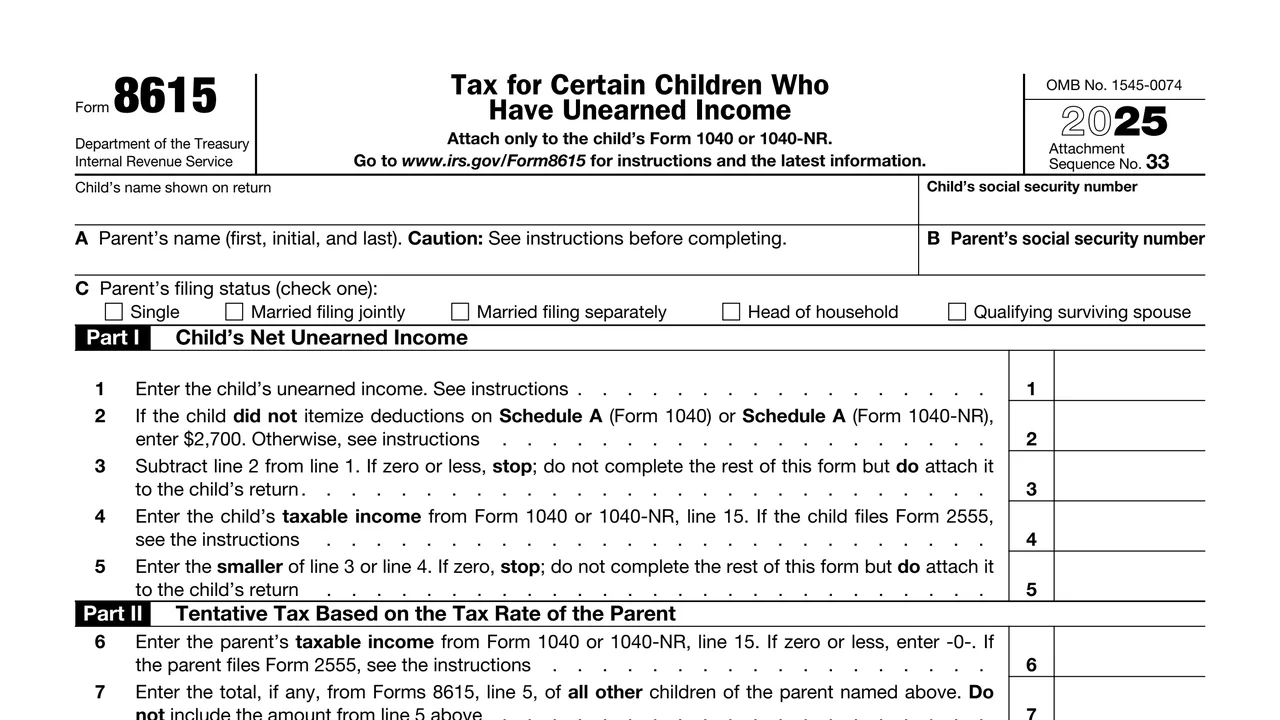
The parent's name and social security number, and a box for the parent's filing status. The form says to see the instructions before completing them.
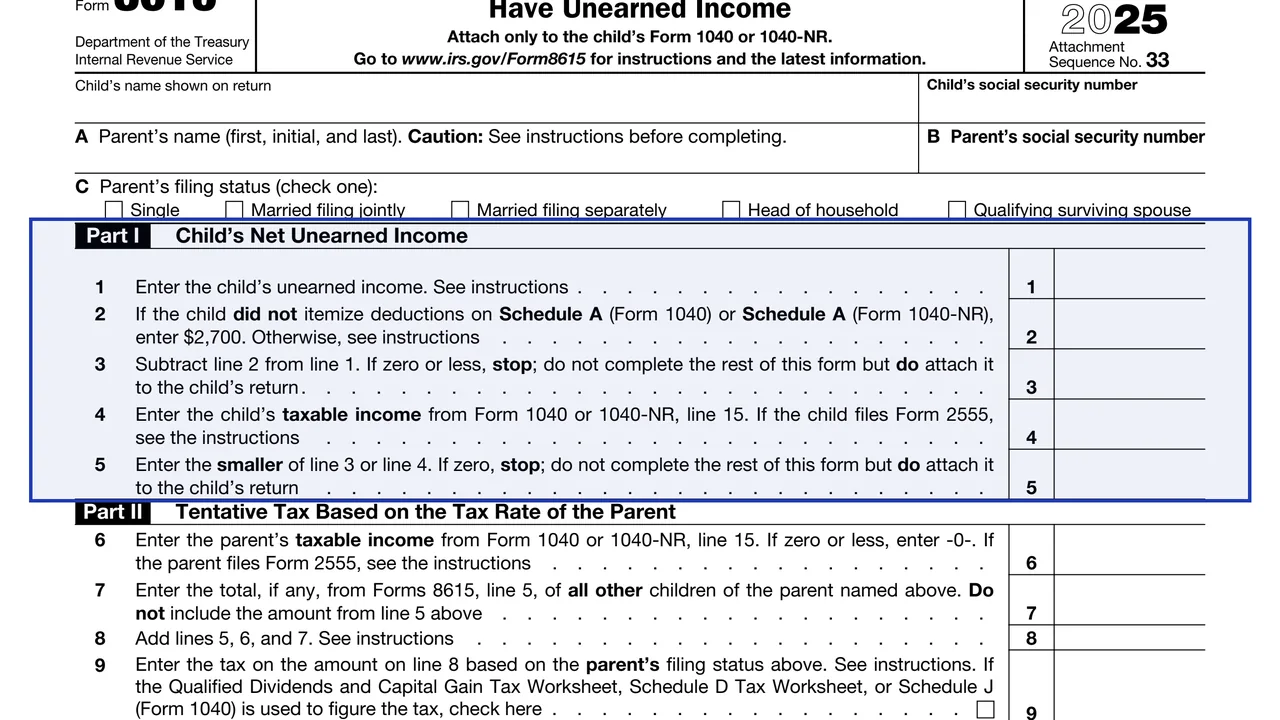
Lines 1 to 5: the child's unearned income, minus $2,700 or an itemized amount, limited to the child's taxable income.
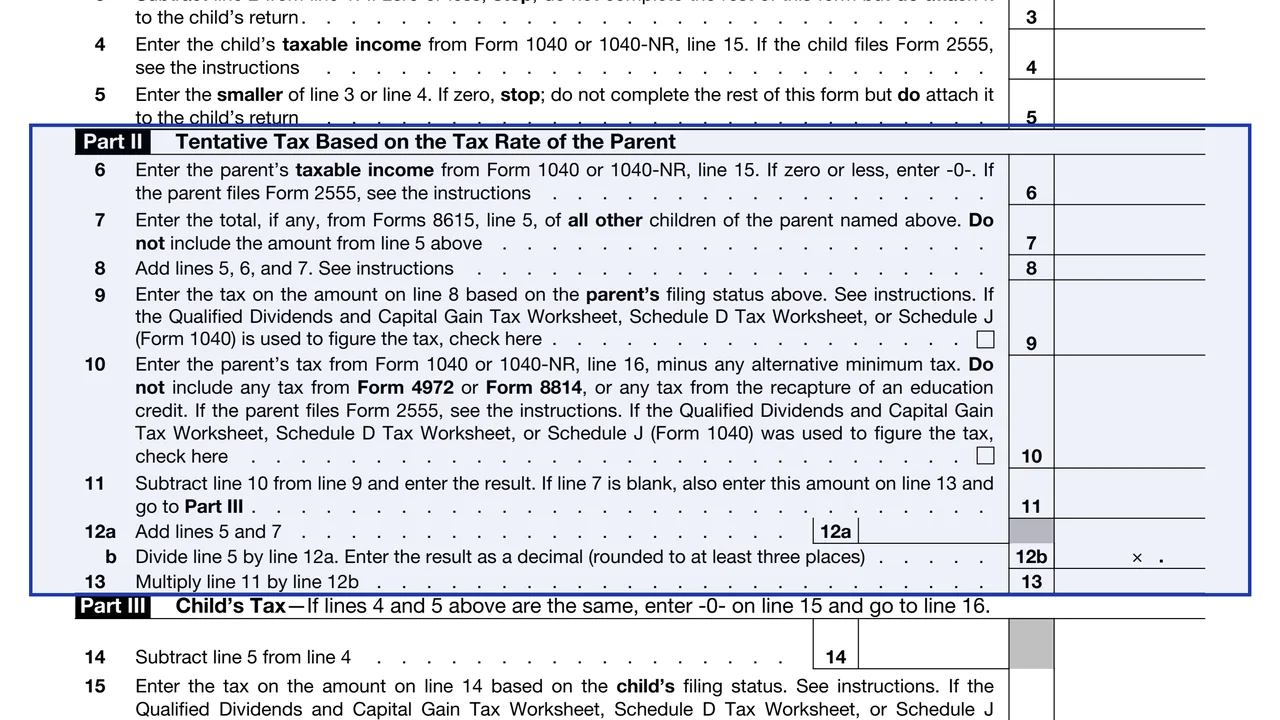
Lines 6 to 13: the parent's taxable income and tax, other children's net unearned income, and the child's share of the tentative tax.
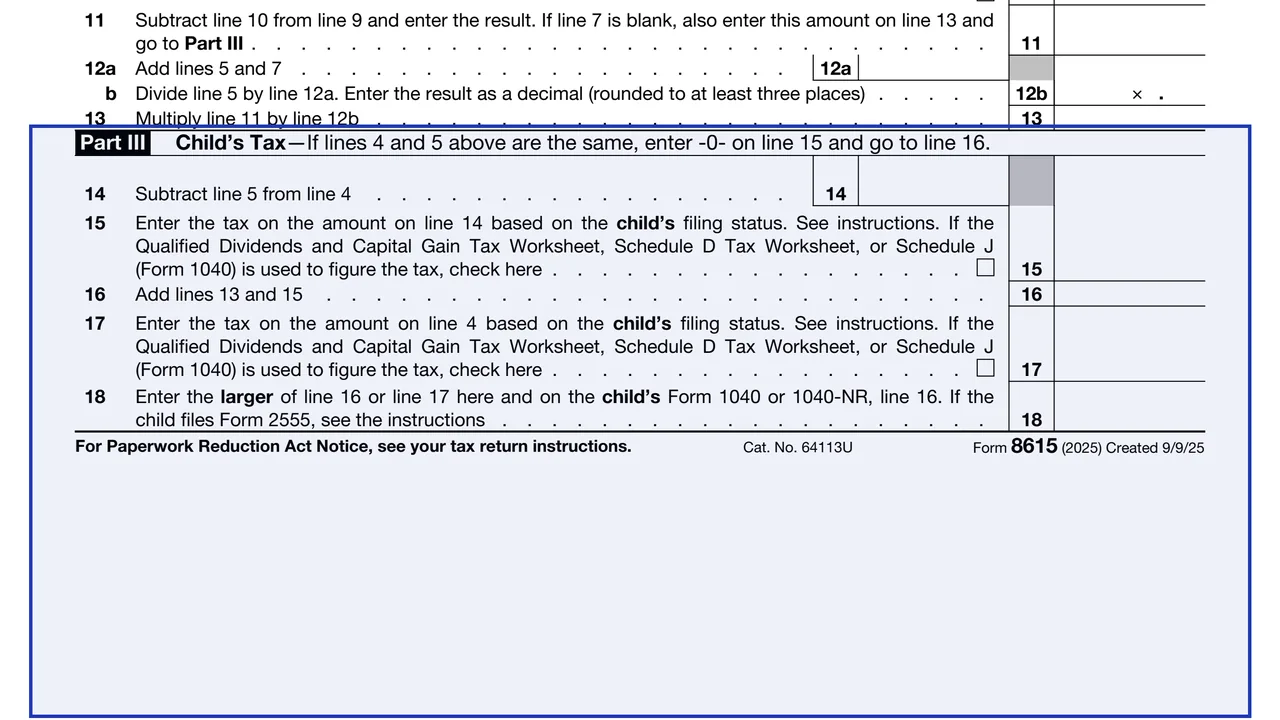
Lines 14 to 18: tax on the rest of the child's taxable income, then the larger of two tax figures, carried to the child's Form 1040 or 1040-NR, line 16.
Parents filing jointly: the parent listed first on the joint return. Married filing separately: the parent with the higher taxable income. Unmarried parents: generally the parent the child lived with most of the year.
With no earned income, enter the child's adjusted gross income from Form 1040 or 1040-NR, line 11b. With earned income, use the Child's Unearned Income Worksheet in the instructions.
Enter $2,700 if the child did not itemize deductions. If the child itemizes, the instructions say to enter the larger of $1,350 plus directly connected itemized deductions, or $2,700.
Subtract line 2 from line 1, then enter the smaller of line 3 or the child's taxable income on line 4. If line 3 is zero or less, or line 5 is zero, the form says to stop but still attach it to the child's return.
Enter the parent's taxable income and tax, add other children's line 5 amounts on line 7, and figure the tentative tax. Lines 12a and 12b split it among the children when line 7 has an amount.
Figure tax on the child's other taxable income and on all of line 4 at the child's rate. Line 18 is the larger of line 16 or line 17 and goes on the child's Form 1040 or 1040-NR, line 16.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
With the child's Form 1040 or 1040-NR. The form says to attach it only to the child's return.
The instructions say the child should request an extension with Form 4868 if the parent's information isn't known by the original due date, and that an extension of time to file isn't an extension of time to pay.
After the end of the tax year, the child or the child's legal representative can send a signed, written request to the Internal Revenue Service Center where the parent's return will be filed.
If the parent's income or another child's net unearned income changes, the instructions say the child's tax is refigured, and Form 1040-X is filed if it changes.
The instructions say the child may be subject to the alternative minimum tax (Form 6251) or the 3.8% net investment income tax (Form 8960).
8814
26 fields, 1 page

1040
199 fields, 2 pages
1040-NR
171 fields, 2 pages
4868
17 fields, 4 pages
1040-X
166 fields, 2 pages
2555
160 fields, 3 pages
The instructions list conditions a child meets for Form 8615 to be filed. The form is attached to the child's return, not the parent's, and uses the parent's tax information.
No tool matches that search.
The instructions say it is generally all income other than pay for work actually performed, including taxable interest, dividends, capital gains, rents, royalties, pension and annuity income, unemployment compensation and alimony.
For a joint return, the parent listed first. For married parents filing separately, the one with the higher taxable income. For unmarried parents, generally the custodial parent. The instructions also cover remarriage.
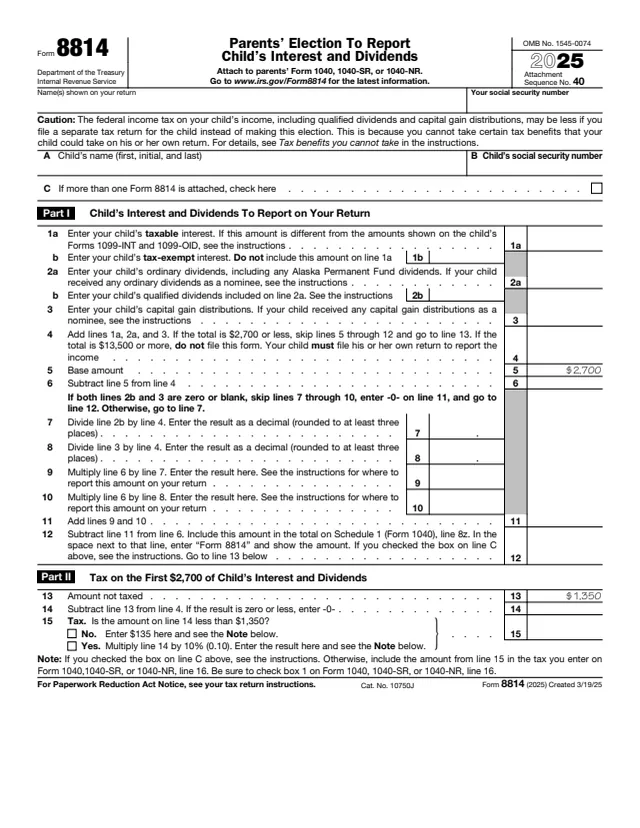
The instructions say a parent may be able to elect to report the child's interest, ordinary dividends and capital gain distributions using Form 8814, and that the tax may be higher if this election is made.
The instructions say the term "child" includes a legally adopted child and a stepchild, whether or not the child is a dependent.
If line 3 is zero or less, or line 5 is zero, the form says to stop and not complete the rest, but to attach Form 8615 to the child's return.
The instructions say these rules don't apply if neither of the child's parents were living at the end of the year.