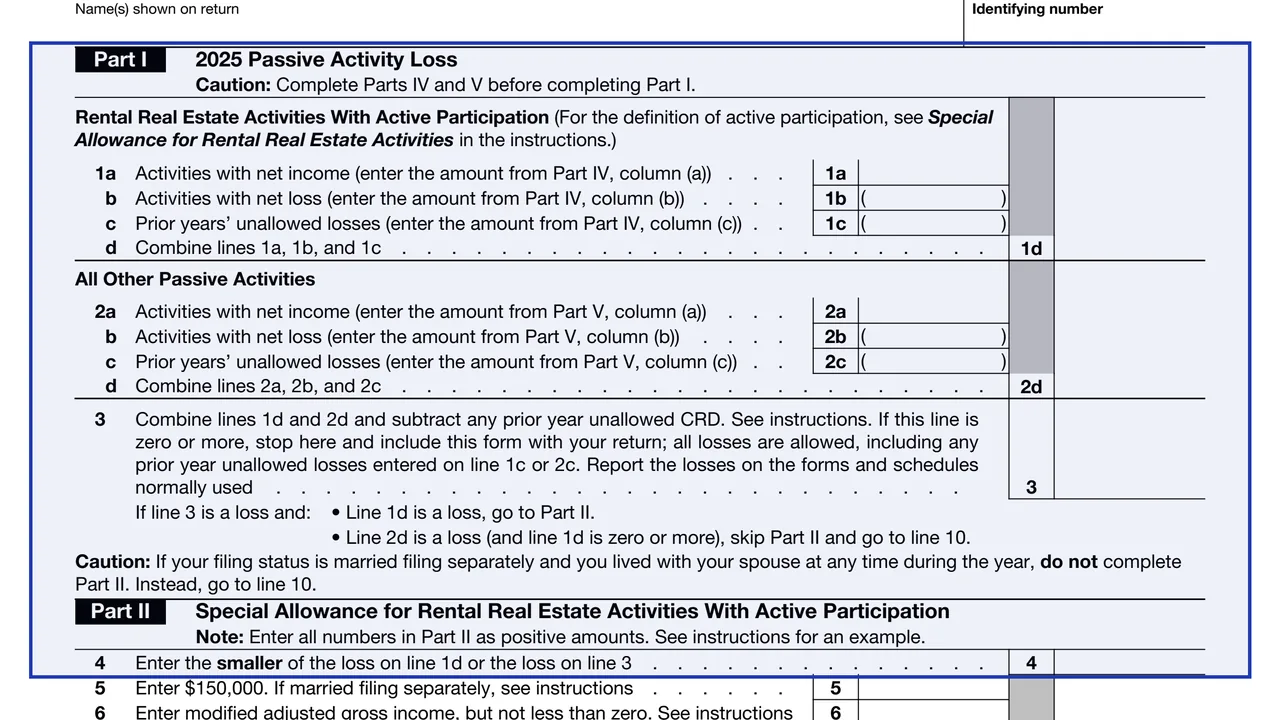
Part I: 2025 Passive Activity Loss
Lines 1a to 1d for rental real estate with active participation, lines 2a to 2d for all other passive activities, and line 3 combining them. The form says to complete Parts IV and V first.
8582
Passive Activity Loss Limitations
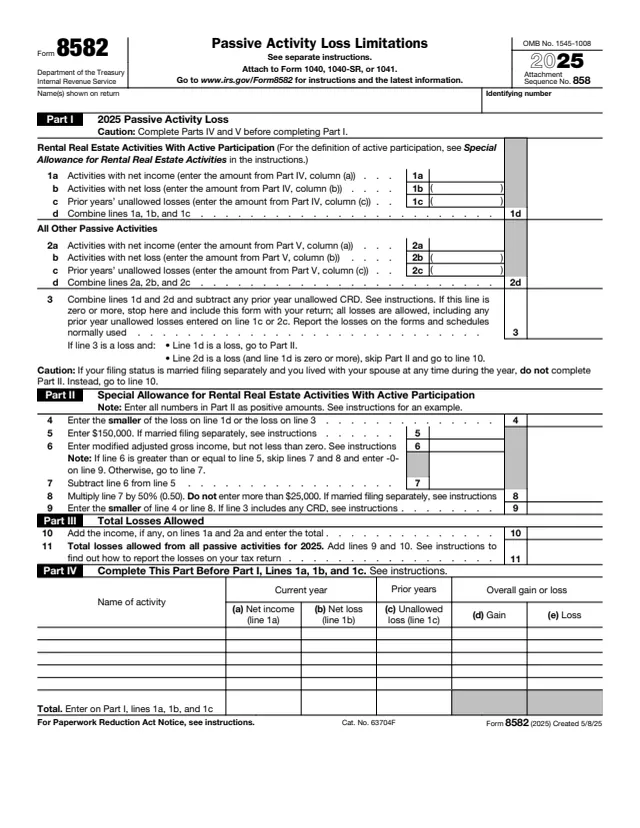
Form 8582, Passive Activity Loss Limitations, is used by noncorporate taxpayers to figure the amount of any passive activity loss (PAL) for the current tax year and to report the application of prior-year unallowed PALs. The instructions say a PAL occurs when total losses from all passive activities, including prior-year unallowed losses, exceed the total income from all passive activities.
The instructions say passive activities generally include trade or business activities in which the taxpayer did not materially participate, and rental activities regardless of participation. Losses not allowed in the current year are carried forward. The form is attached to Form 1040, 1040-SR or 1041. Corporations use Form 8810 instead.
This page has the 2025 form. You can fill out the PDF free in your browser on this page and download it without an account.
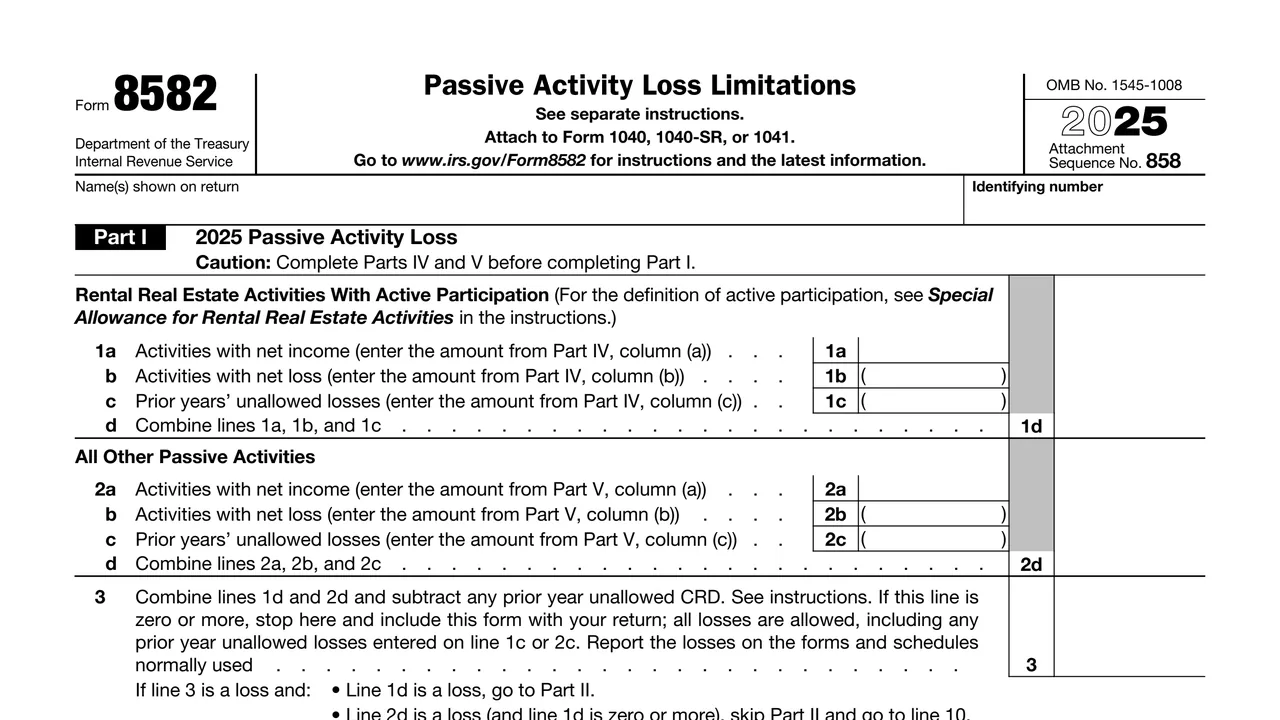
Lines 1a to 1d for rental real estate with active participation, lines 2a to 2d for all other passive activities, and line 3 combining them. The form says to complete Parts IV and V first.
Lines 4 to 9 figure the special allowance for rental real estate activities with active participation, using $150,000 on line 5 and modified adjusted gross income on line 6.
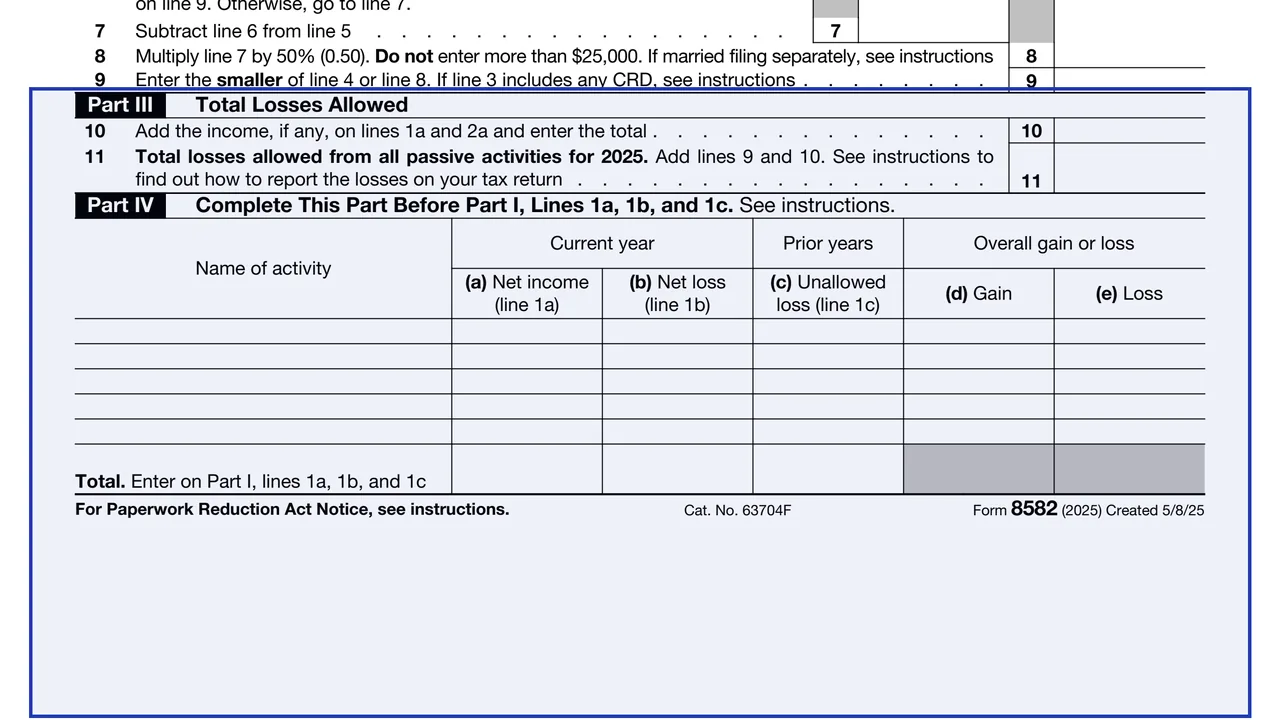
Line 10 adds the income on lines 1a and 2a, and line 11 gives the total losses allowed from all passive activities for 2025.
One row per activity with current year net income, net loss and prior years' unallowed loss, plus the overall gain or loss. Part IV is for rental real estate with active participation and Part V for all other passive activities.
Part VI allocates the special allowance on line 9 among rental real estate activities. Part VII allocates the unallowed losses among activities by ratio.
Part VIII shows the unallowed and allowed loss for each activity. Part IX is for activities with losses reported on two or more forms or schedules.
List each activity with its current year net income in column (a), net loss in column (b) and prior-year unallowed loss in column (c). The instructions say the prior-year amounts come from Part VII, column (c), of the 2024 Form 8582. Enter the overall gain or loss in column (d) or (e).
Enter the column totals on lines 1a to 1c and 2a to 2c and combine them. The form says that if line 3 is zero or more, stop and include the form with the return, because all losses are allowed.
Enter all numbers as positive amounts. Line 4 is the smaller of the loss on line 1d or line 3, line 5 is $150,000 ($75,000 for married filing separately and living apart all year), and line 6 is modified adjusted gross income. Line 8 is 50% of line 7, not more than $25,000.
Add the income on lines 1a and 2a on line 10, then add lines 9 and 10 on line 11 for the total losses allowed for 2025.
Allocate the special allowance and the unallowed losses among activities by ratio, then figure each activity's allowed loss. The instructions say to keep a record of the unallowed losses in Part VIII, column (b), to figure the PAL next year.
The instructions say to report allowed losses on the forms and schedules normally used, such as Schedule C, E or F, Form 4797 or Form 8949, and to enter "PAL" beside certain entries.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR or 1041. It is filed with that return rather than on its own.
The instructions say losses not allowed in the current year are carried forward until they are allowed against passive income, against the special allowance, or when the entire interest is sold or exchanged in a fully taxable transaction to an unrelated party.
The instructions say passive activity losses are generally subject to other limits, such as basis and at-risk limitations (Form 6198), first. Allowable business losses may then be limited on Form 461.
The form says that if the filing status is married filing separately and the spouses lived together at any time during the year, Part II is not completed.
The instructions say not to report passive income, gains or losses from a publicly traded partnership (PTP) on Form 8582, and give separate rules for PTPs.
The instructions say that if more lines are needed for Parts IV through IX, attach copies of the pages or a schedule in the same format.
8582-CR
52 fields, 2 pages
6198
34 fields, 1 page
461
18 fields, 1 page
1040
185 fields, 2 pages
4797
182 fields, 2 pages
8810
20 fields, 1 page
The instructions say Form 8582 is filed by individuals, estates and trusts who have passive activity deductions, including prior year unallowed losses.
No tool matches that search.
The instructions say individuals, estates and trusts who have passive activity deductions, including prior year unallowed losses, file it, unless the rental real estate exception applies.
No. The instructions say corporations subject to the passive activity rules use Form 8810.
The instructions say a taxpayer who actively participated in a passive rental real estate activity may be able to deduct up to $25,000 of loss from nonpassive income. It is limited above $100,000 of modified adjusted gross income, and generally there is none at $150,000 or more ($50,000 and $75,000 if married filing separately).
The instructions say they come from Part VII, column (c), of the 2024 Form 8582.
The form says to stop and include the form with the return. All losses are allowed, including prior year unallowed losses on line 1c or 2c.
No. The instructions say passive income, gains and losses from a PTP are not reported on Form 8582 and follow separate rules.